
Inquire Now
Key Strategic Points
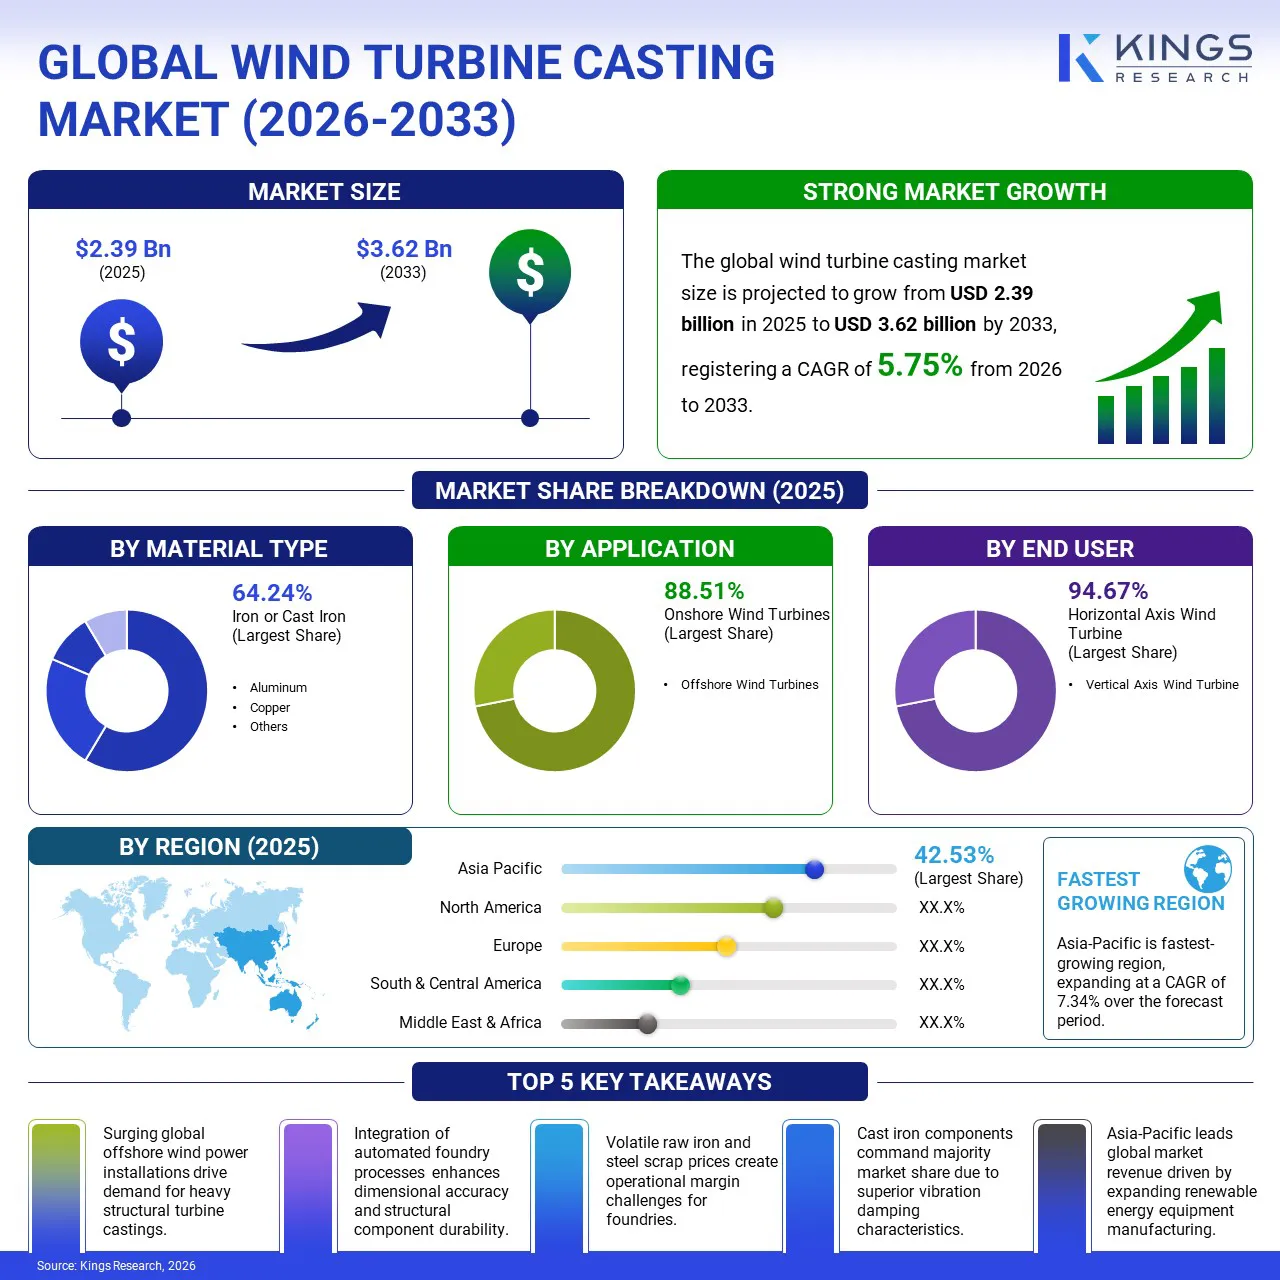
According to Kings Research, the global wind turbine casting market size was valued at USD 2.39 billion in 2025 and is projected to reach USD 3.62 billion by 2033, exhibiting a CAGR of 5.75% during the forecast period (2026-2033).
The market encompasses heavy-duty structural cast components, including rotor hubs, main frames, gearbox housings, rotor shafts, and blade adapters engineered for onshore and offshore wind energy installations. The report explores key drivers of market development, offering detailed regional analysis and a comprehensive overview of the competitive landscape shaping future opportunities.
The market is expanding steadily, driven by increasing global investments in renewable energy infrastructure, offshore wind farm expansions, and the transition toward higher-capacity multi-megawatt wind turbines. The trend toward larger and more powerful turbines is increasing the demand for advanced casting solutions, as larger turbines require robust, high-integrity cast components capable of withstanding extreme mechanical loads and severe environmental conditions.
Major companies operating in the wind turbine casting industry include DHI Group, Vestas, Premier Heavy Engineering, Elyria Foundry Company, SHW Casting Technologies GmbH & Co. KG, Somaschini S.p.A., Castings PLC, Goldwind, General Electric, Siemens Gamesa Renewable Energy, S.A., and Envision Group.
In June 2026, the Global Wind Energy Council (GWEC) reported that more than 9 GW of new offshore wind capacity was grid-connected globally in 2025, bringing cumulative offshore wind capacity to 92.5 GW. GWEC also noted that more than 50 GW of offshore wind projects were under construction worldwide, supporting continued demand for large-scale, durable components used in offshore wind infrastructure.
The global wind turbine casting market is experiencing steady expansion, driven by the global transition toward larger, higher-capacity multi-megawatt wind turbines. Larger turbines harness more energy from stronger winds at higher altitudes, requiring larger, highly durable structural castings such as main frames and rotor hubs.
This shift toward offshore projects requires specialized turbine castings designed to endure harsh marine environments, salt spray corrosion, and cyclic fatigue. Wind turbine casting involves manufacturing essential components, such as blades, hubs, and towers, from materials including iron, steel, aluminum, or specialized alloys. Casting enables production of intricate, large-scale components essential for efficient wind turbine operation, enhancing system reliability and performance globally.
In December 2025, Baettr India broke ground on a major expansion of its wind turbine casting facility near Chennai, Tamil Nadu. The expansion is expected to increase annual production capacity for saleable castings from 27,500 tonnes to 95,040 tonnes, nearly quadrupling capacity, to meet rising demand from wind turbine OEMs for large structural components such as hubs and mainframes.
A primary restraint facing the wind turbine casting market involves price volatility in key raw materials, particularly pig iron, scrap steel, aluminum, and specialized alloy inoculants. Energy-intensive foundry operations face rising electricity tariffs and environmental compliance costs related to carbon emissions and sand casting waste management.
Furthermore, transporting extra-large casting components (often weighing over 30 to 50 metric tons) from foundries to turbine assembly plants presents complex logistical challenges, axle-weight transport restrictions, and high freight costs, constraining supply chain flexibility for remote wind farm developments.
The market is undergoing significant technological evolution driven by the adoption of high-strength ductile cast iron (SG iron) formulations, 3D sand mold printing, and advanced non-destructive testing (NDT) techniques. Heavy-section ductile iron offers exceptional fatigue strength and impact resistance at low temperatures, making it the preferred material for offshore main frames and hubs.
Simultaneously, 3D sand printing of casting molds eliminates traditional patternmaking lead times, allowing foundries to produce complex prototype geometries and large structural castings with higher precision and lower material waste. Advanced ultrasonic and X-ray NDT methods ensure zero-defect casting integrity before machining.
In January 2025, GE Vernova commenced operations at a new wind-turbine manufacturing facility in Pune, India, producing key components including nacelles and hubs. The facility strengthens India's domestic wind manufacturing ecosystem and supports the growing demand for locally manufactured turbine components.
|
Segmentation |
Details |
|
By Material Type |
Iron or Cast Iron, Aluminum, Copper, and Others |
|
By Application |
Onshore Wind Turbines and Offshore Wind Turbines |
|
By End User |
Horizontal Axis Wind Turbine and Vertical Axis Wind Turbine |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, the UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, U.A.E., Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South and Central America: Brazil, Argentina, and the rest of South and Central America |
Based on material type, the market is categorized into iron or cast iron, aluminum, copper, and others. The iron or cast-iron segment has the highest market share of 64.24% in the wind turbine casting market in 2025.
The segment is essential for manufacturing critical components like hubs and mainframes. Known for its strength and durability, cast iron meets the rigorous demands of larger and more efficient turbines. Advancements in casting techniques and material technologies continue to enhance performance and reliability while optimizing production costs.
As global efforts intensify to shift toward sustainable energy, the iron segment remains pivotal in meeting the increasing demand for robust wind turbine components. Its continuous evolution underscores its essential role in advancing renewable energy solutions globally.
Based on application, the market is divided into onshore wind turbines and offshore wind turbines. The onshore wind turbines segment captured the largest wind turbine casting market share of 88.51% in 2025.
As nations accelerate their shift toward renewable energy, onshore wind energy has emerged as a major solution due to its cost-effectiveness and scalability. The expansion of this segment is fueled by advancements in turbine technology, enabling the development of larger, more efficient turbines that require durable casting solutions for components such as blades, hubs, and towers.
Supported by favorable government policies and incentives, these projects drive demand for high-performance casting materials capable of withstanding the rigorous conditions of wind energy generation farms. Hence, the onshore wind turbine segment is at the forefront of driving innovation and market expansion in renewable energy infrastructure.
Based on end-user, the market is categorized into horizontal-axis wind turbines and vertical-axis wind turbines. The horizontal-axis wind turbine segment has the highest market share of 94.67% in 2025. These turbines are favored for their efficiency and versatility across both onshore and offshore applications.
As global demand for renewable energy escalates, spurred by environmental concerns and energy security, horizontal axis turbines stand out for their ability to efficiently harness energy from wind. Advancements in technology continue to enhance these turbines, enabling larger and more reliable designs that require robust casting solutions for components like blades, hubs, and nacelles.
Government incentives and policies supporting renewable energy further propel market expansion, making horizontal-axis wind turbines integral to meeting the rising global demand for sustainable energy solutions.
The market is segmented into North America, Europe, Asia Pacific, the Middle East & Africa, and South and Central America.
Asia Pacific held the dominant market share of 42.53% in 2025 and is anticipated to have the fastest growth of 7.34% in the forecasting period. According to Kings Research, regional dominance is driven by massive wind energy capacity expansions in China, India, and Japan, alongside a dense domestic ecosystem of heavy foundries and turbine OEMs.
Recent advancements in turbine casting technology and supportive government incentives are accelerating adoption of wind turbine casting solutions across Asia. These developments underscore Asia-Pacific's pivotal role in driving market growth and innovation.
According to Kings Research, North America is anticipated to witness significant growth during the forecast period. Expansion is driven by the US Inflation Reduction Act (IRA) tax incentives for domestic clean energy manufacturing, expanding utility-scale onshore wind farms in the US Midwest, and emerging offshore projects along the Atlantic coast.
According to Kings Research, Europe represents a major revenue hub in the global wind turbine casting market, driven by pioneering offshore wind developments in the North Sea, strict EU decarbonization directives, and established casting technology providers in Germany, Denmark, and the UK.
The Middle East & Africa region is witnessing gradual market expansion, supported by national renewable energy diversification programs and utility-scale wind projects in South Africa, Egypt, and Saudi Arabia.
South and Central America is experiencing steady growth in wind turbine casting demand, led by Brazil and Chile, propelled by favorable wind resource conditions, expanding auction frameworks, and regional industrial infrastructure investments.
The global wind turbine casting market report provides valuable insight into the fragmented nature of the industry. Prominent players are focusing on several key business strategies such as partnerships, mergers and acquisitions, product innovations, and joint ventures to expand their product portfolio and increase their market shares across different regions.
Companies are implementing strategic initiatives, including service expansion, R&D investment, new delivery centers, and process optimization, to strengthen foundry efficiency and meet multi-megawatt casting requirements.
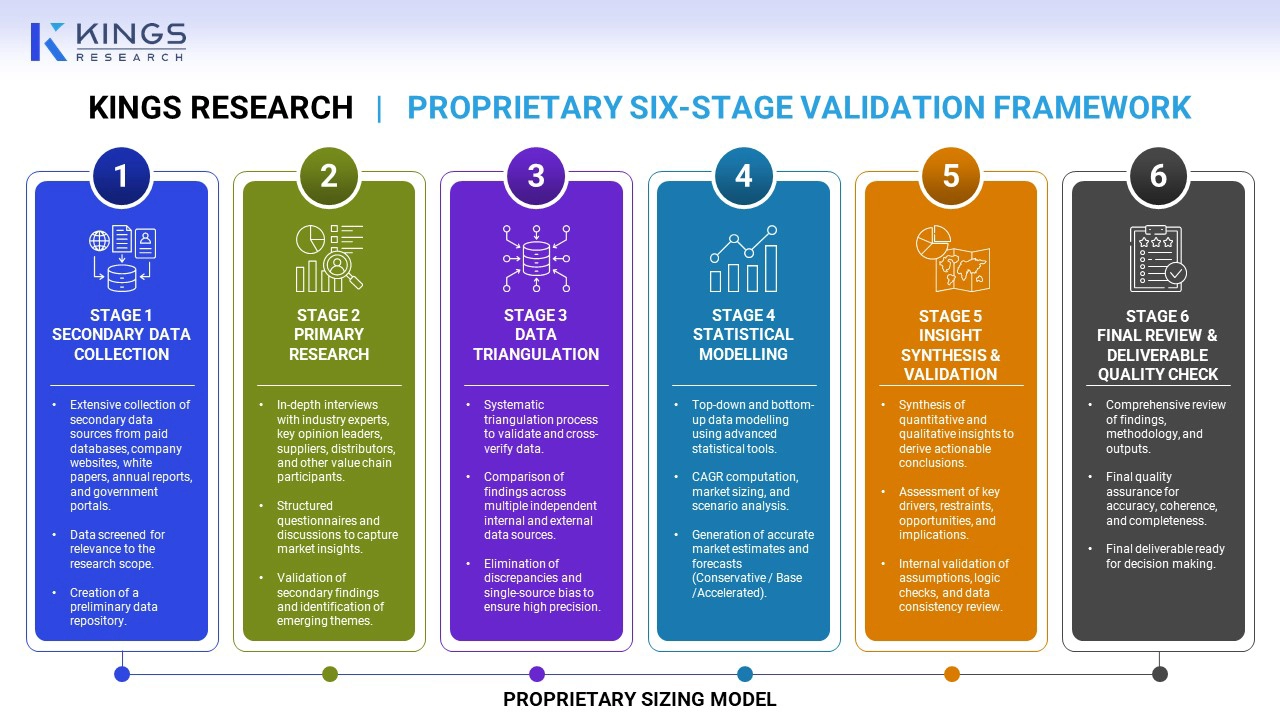
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
We deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Swati is a committed research analyst with a passion for optimizing systems and processes across industries, specializing in healthcare but also bringing valuable expertise to sectors such as consumer goods, life sciences, and more. Her cross-domain research approach allows her to generate clear, actionable reports that inform strategic decisions in a variety of fields. Swati is committed to staying ahead of evolving trends, leveraging her broad understanding of different sectors to provide insights that are relevant to a range of industries. In her personal time, she enjoys music and spending quality time with her family, which inspires her creativity and enriches her professional approach. Her systematic methodology ensures that every report is both thorough and practical. Swati's ability to bridge regulatory frameworks with market realities gives her recommendations a distinct edge. She collaborates seamlessly with cross-functional teams, distilling complex data into straightforward narratives. Her proactive monitoring of policy and technological shifts keeps her analysis forward-looking.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


