Inquire Now
Key Strategic Points
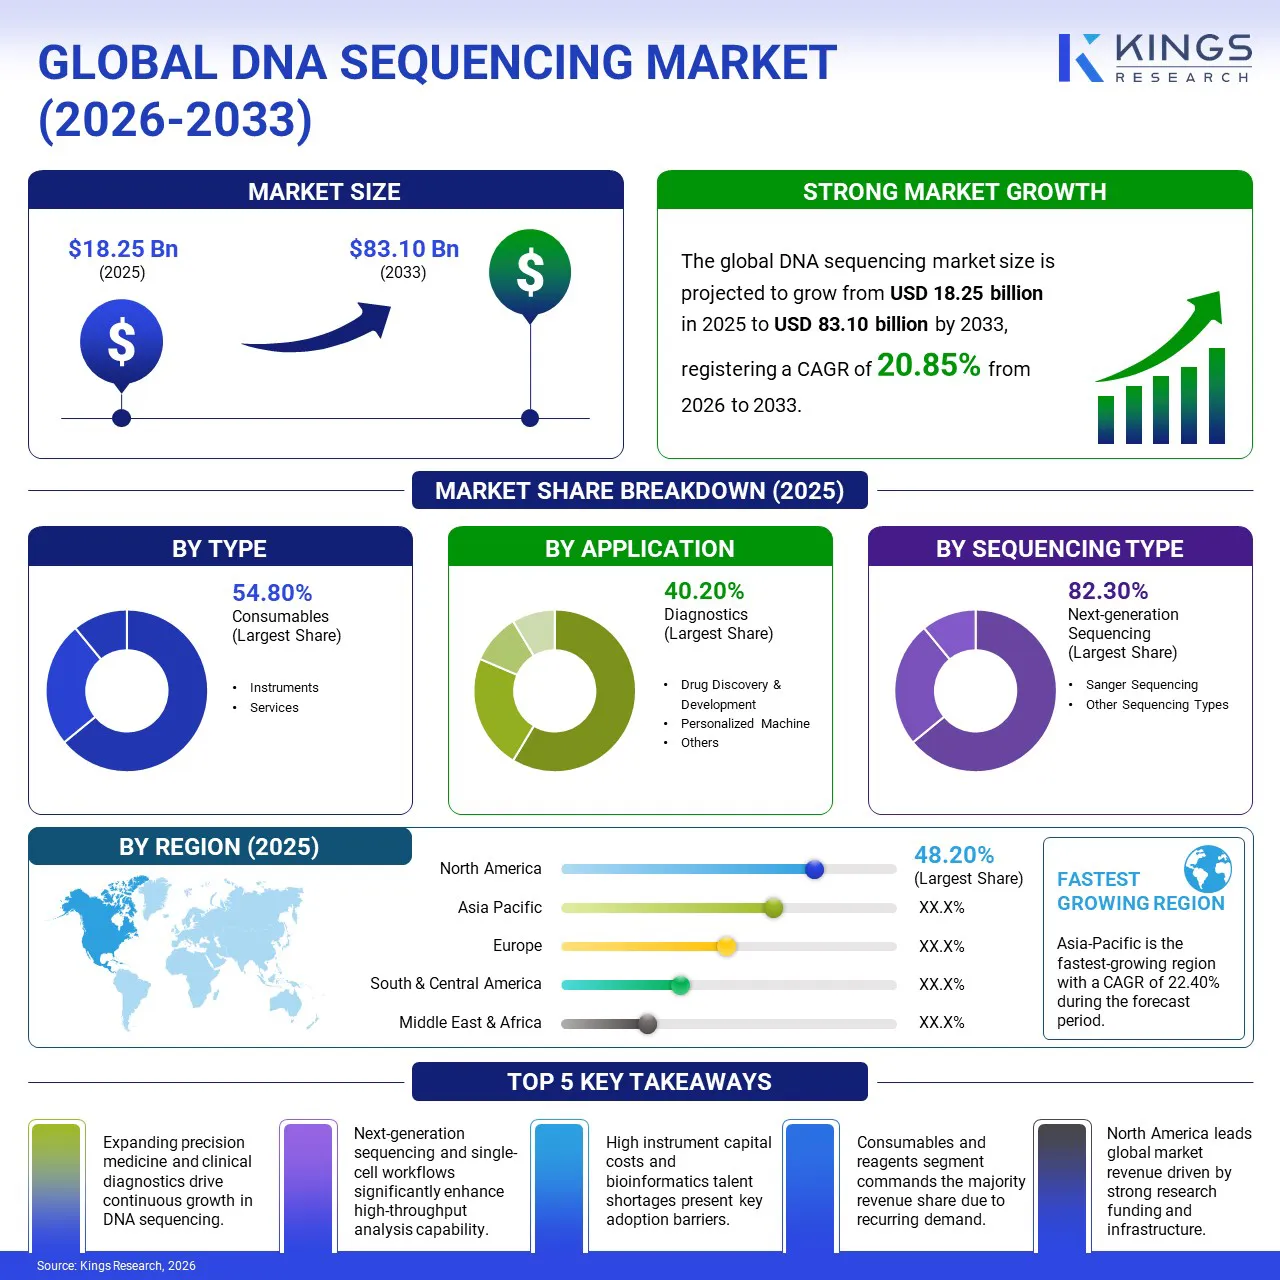
According to Kings Research, the global DNA sequencing market size was valued at USD 18.25 billion in 2025 and is projected to reach USD 83.10 billion by 2033, exhibiting a CAGR of 20.85% during the forecast period (2026–2033).
The market encompasses sequencing platforms, reagents, consumables, and bioinformatics software utilized across oncology diagnostics, hereditary disease testing, agricultural genomics, and reproductive health. The report explores key drivers of market development, offering detailed regional analysis and a comprehensive overview of the competitive landscape shaping future opportunities.
The market is expanding rapidly, driven by the surging demand for precision medicine, ongoing technological advancements in Next-Generation Sequencing (NGS) and long-read sequencing platforms, and expanding applications in oncology and infectious disease surveillance. Increased funding for genomic research and rising clinical adoption of non-invasive prenatal testing (NIPT) are further catalyzing market expansion.
Major companies operating in the DNA sequencing market include Illumina, Inc., Thermo Fisher Scientific, Inc., Agilent Technologies, Inc., QIAGEN N.V., F. Hoffmann-La Roche Ltd., Macrogen, Inc., PerkinElmer Genomics, Pacific Biosciences of California, Inc. (PacBio), BGI Group, and Bio-Rad Laboratories, Inc.
The global DNA sequencing market is experiencing rapid expansion, driven primarily by the integration of genomic profiling into precision medicine and oncology diagnostics. DNA sequencing enables precise diagnoses and targeted therapies by decoding disease mechanisms at the genetic level.
These personalized approaches enhance treatment effectiveness and patient outcomes, establishing DNA sequencing as a crucial tool in modern medicine. Growing reliance on DNA sequencing to understand and combat these diseases is driving market growth, as healthcare providers and researchers invest in advanced technologies to meet demand for personalized solutions.
In May 2026, Illumina introduced a whole-genome sequencing solution for molecular residual disease (MRD) research, designed to enable highly sensitive detection of residual cancer following treatment. The solution supports genomic profiling of solid tumors and blood cancers and represents Illumina's expansion into whole-genome sequencing applications for oncology research, further strengthening the role of DNA sequencing in precision cancer care.
A primary restraint facing the DNA sequencing market involves high capital expenditure for high-throughput sequencing instruments and complex downstream bioinformatics infrastructure. Acquiring and maintaining state-of-the-art benchtop or ultra-high-throughput sequencers requires significant financial commitments, posing a financial barrier for smaller diagnostic laboratories and academic institutions.
Furthermore, interpreting vast volumes of complex genomic data requires specialized bioinformatics talent and cloud storage infrastructure, creating data processing bottlenecks. Stringent regulatory frameworks governing patient genetic data privacy and varying reimbursement policies for genomic panel testing also complicate commercial expansion.
The market is undergoing a technological shift driven by long-read sequencing adoption, single-cell multi-omics, and artificial intelligence (AI) integration in variant interpretation. Long-read technologies (such as nanopore and single-molecule real-time sequencing) complement short-read systems by resolving complex structural variations, repetitive genomic regions, and full-length transcript isoforms.
Simultaneously, AI and machine learning algorithms are accelerating tertiary data analysis, automating variant classification, and reducing report turnaround times for clinicians. These investments are driving the development of advanced, efficient, and cost-effective sequencing methods that enhance the accuracy and speed of genetic analysis.
In May 2026, PacBio announced the global availability of its SPRQ-Nx sequencing chemistry for the Revio HiFi sequencing platform, enabling lower-cost whole-genome sequencing while incorporating enhanced methylation detection and improvements to DeepConsensus, an AI-powered consensus algorithm developed with Google. The technology is designed to improve sequencing accuracy, yield, and biological insights while making long-read sequencing more accessible for large-scale genomic studies.
|
Segmentation |
Details |
|
By Type |
Consumables, Instruments, and Services |
|
By Application |
Drug Discovery & Development, Diagnostics, Personalized Medicines, and Others |
|
By End User |
Biotechnology & Pharmaceutical Companies, Contract Research Organizations (CROs), Academic & Research Institutes, and Others |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South & Central America: Brazil, Argentina, and the rest of South & Central America |
Based on type, the DNA sequencing market is categorized into consumables, instruments, and services. The consumables segment garnered the highest market share of 54.80% in 2025. This growth is propelled by the increasing adoption of DNA sequencing technologies across various applications such as clinical diagnostics, research, and agriculture.
As the demand for personalized medicine and precision healthcare grows, there's an increasing need for consumables that facilitate these advanced sequencing techniques. Additionally, ongoing advancements in sequencing platforms and the introduction of high-throughput systems require a constant supply of consumables, thereby presenting expansion opportunities for manufacturers.
Based on application, the market is divided into drug discovery & development, diagnostics, personalized medicine, and others. The diagnostics segment captured the largest DNA sequencing market share of 44.20% in 2025, supported by the growing clinical application of DNA sequencing for identifying disease-causing genetic variants, diagnosing rare disorders, and detecting cancer-associated mutations. The FDA recognizes NGS tests as important clinical tools for identifying genetic variants used to diagnose and understand human diseases.
Based on end-user, the market is categorized into biotechnology & pharmaceutical companies, contract research organizations (CROs), academic & research institutes, and others. The biotechnology & pharmaceutical companies segment is expected to garner the highest revenue share in 2025.
These companies utilize DNA sequencing technologies extensively to enhance understanding of disease mechanisms, identify therapeutic targets, and develop precision medicines tailored to individual genetic profiles. The segment benefits from substantial investments in research and development aimed at leveraging genomic data for innovative therapies and diagnostics.
Additionally, collaborations between biotech firms, major pharmaceutical corporations, and academic institutions expand the application of sequencing technologies across diverse therapeutic areas, including oncology, rare diseases, and infectious diseases. As genomic insights continue to reshape drug discovery and clinical practices, the biotechnology and pharmaceutical companies segment is witnessing substantial growth.
Based on region, the global market is classified into North America, Europe, Asia-Pacific, MEA, and South and Central America.
North America held the leading market share of 48.20% in 2025. According to Kings Research, this dominant position is driven by high healthcare expenditure, early adoption of advanced genomic technologies, and a strong presence of major sequencing providers (such as Illumina, Thermo Fisher Scientific, Inc., and PacBio). Strong federal research funding through the National Institutes of Health (NIH), expanding clinical insurance coverage for NGS cancer panels, and strategic collaborations between biotech firms, major pharmaceutical corporations, and academic institutions further reinforce regional leadership.
Asia Pacific is anticipated to register the fastest CAGR of 22.40% during the forecast period from 2026 to 2033. According to Kings Research, growth is driven by expanding healthcare infrastructure, rising prevalence of chronic diseases, and increasing government investments in national population genomics initiatives across China, Japan, India, and South Korea. Rising demand for affordable clinical diagnostics is presenting expansion opportunities for manufacturers across regional markets.
According to Kings Research, Europe accounts for a major share of the global DNA sequencing market, supported by well-funded public genomic programs (such as Genomics England), centralized healthcare systems, and strong academic research infrastructure across Germany, the UK, and France.
The Middle East & Africa region is witnessing progressive market expansion, driven by national genomic research initiatives (such as the Emirati Genome Program) and investments in centralized diagnostic reference laboratories across GCC economies. South and Central America is experiencing steady market growth, led by Brazil and Mexico, propelled by expanding private diagnostic laboratory networks, rising adoption of NIPT testing, and growing academic research partnerships.
The global DNA sequencing market report will provide valuable insight with an emphasis on the fragmented nature of the industry. Prominent players are focusing on several key business strategies such as partnerships, mergers and acquisitions, product innovations, and joint ventures to expand their product portfolio and increase their market shares across different regions.
Companies are implementing impactful strategic initiatives, such as expanding services, investing in research and development (R&D), establishing new service delivery centers, and optimizing their service delivery processes, which are likely to create new opportunities for market growth.
Key Industry Development
How We Gather This Information
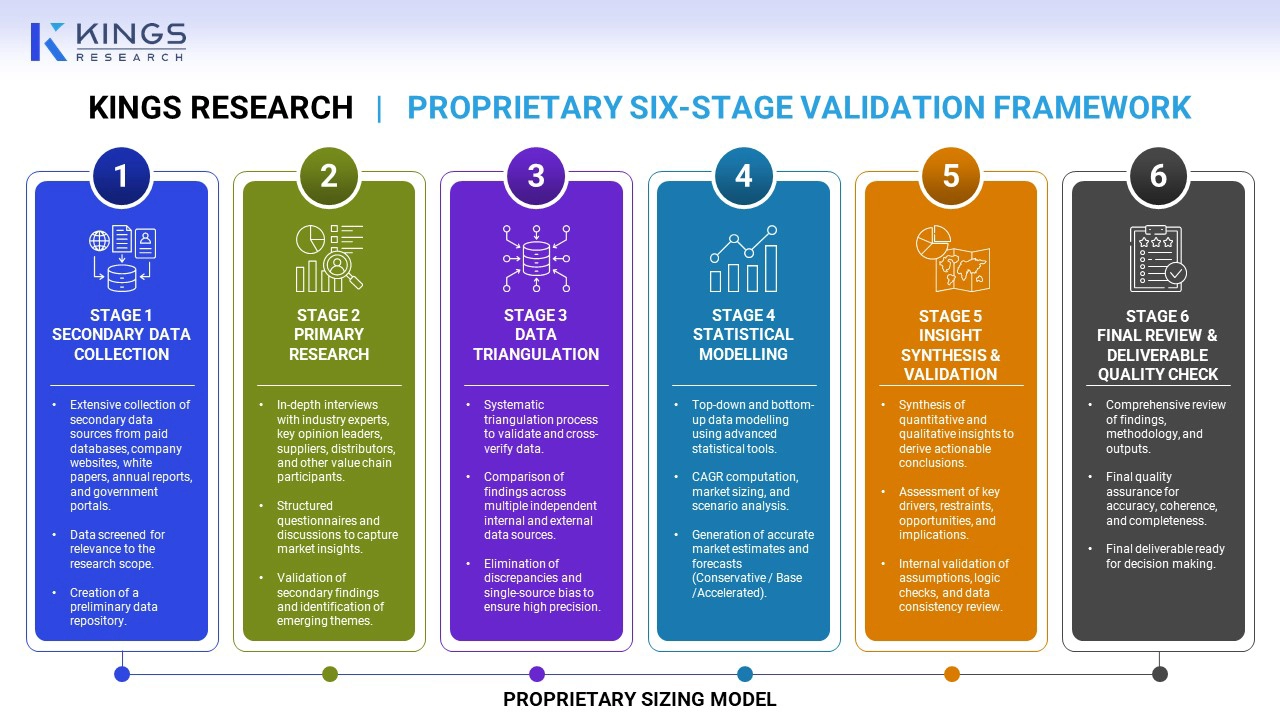
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
 Why Kings Research?
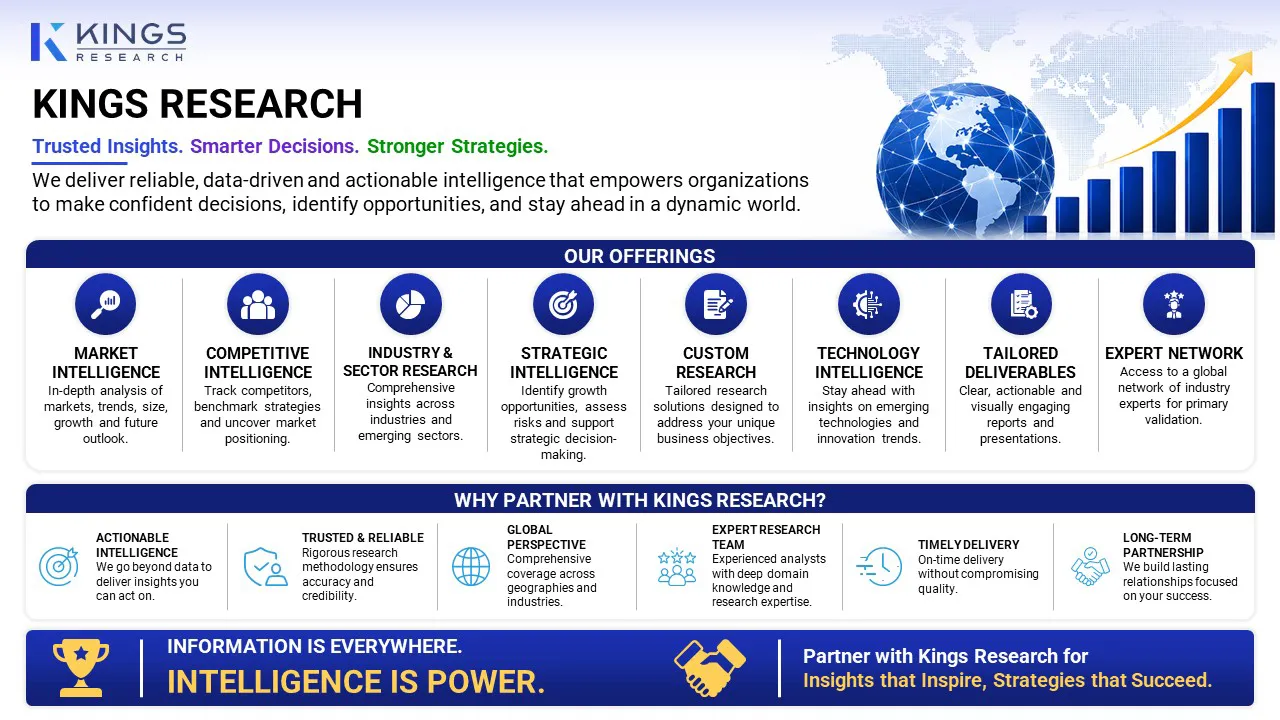
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Swati is a committed research analyst with a passion for optimizing systems and processes across industries, specializing in healthcare but also bringing valuable expertise to sectors such as consumer goods, life sciences, and more. Her cross-domain research approach allows her to generate clear, actionable reports that inform strategic decisions in a variety of fields. Swati is committed to staying ahead of evolving trends, leveraging her broad understanding of different sectors to provide insights that are relevant to a range of industries. In her personal time, she enjoys music and spending quality time with her family, which inspires her creativity and enriches her professional approach. Her systematic methodology ensures that every report is both thorough and practical. Swati's ability to bridge regulatory frameworks with market realities gives her recommendations a distinct edge. She collaborates seamlessly with cross-functional teams, distilling complex data into straightforward narratives. Her proactive monitoring of policy and technological shifts keeps her analysis forward-looking.
With many years of consulting experience across global pharma, biotech, and MedTech markets, Minaz brings deep domain expertise, strategic clarity, and analytical rigor to every engagement. She has led 130+ consulting assignments spanning market entry, competitive landscaping, and portfolio prioritization, helping clients navigate complex, high-stakes decisions with confidence. Known for her ability to synthesize primary and secondary research into executive-ready recommendations, Minaz has built forecasting models and market sizing frameworks that have informed multi-million dollar investment decisions in oncology, diagnostics, and peptide therapeutics. Beyond her analytical strength, Minaz is a trusted client partner, translating complex datasets into clear, actionable insights for senior stakeholders. She currently leads a team of research analysts, driving business expansion, and shaping client engagement strategy.