
Inquire Now
Key Strategic Points
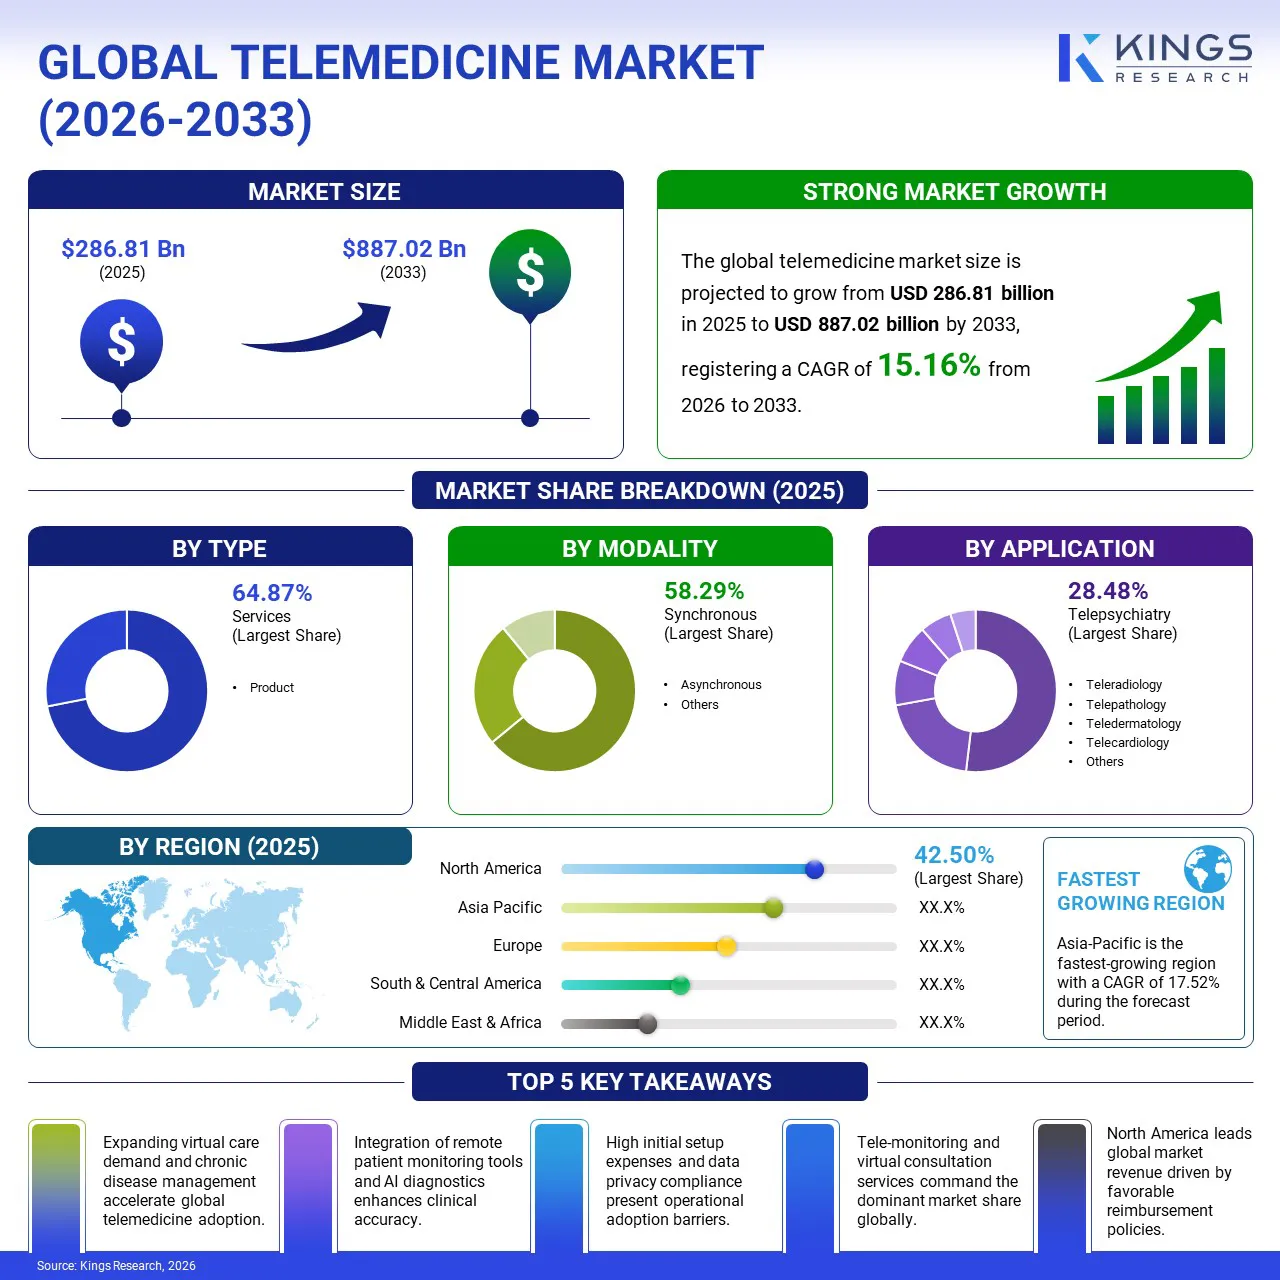
According to Kings Research, the global telemedicine market size was estimated at USD 286.81 billion in 2025 and is projected to reach USD 887.02 billion by 2033, exhibiting a CAGR of 15.16% during the forecast period (2026-2033).
The market encompasses teleconsulting, telemonitoring, teleeducation, teleradiology, telepsychiatry, telecardiology, and virtual care platforms engineered for healthcare facilities, homecare settings, and independent clinical practices. The report explores key drivers of market development, offering detailed regional analysis and a comprehensive overview of the competitive landscape shaping future opportunities.
The market is expanding rapidly, driven by the increasing adoption of virtual care solutions, the rising prevalence of chronic conditions, expanding broadband and 5G connectivity, and supportive reimbursement frameworks. This digital transformation has made healthcare more convenient and accessible, encouraging patients and healthcare providers to integrate telemedicine into routine medical care and drive market growth.
Major companies operating in the telemedicine market include Teladoc Health, Inc., Amwell (American Well Corporation), Doximity, Inc., GoodRx, Inc., MDLIVE (Cigna), Pfizer, Inc., Amazon Pharmacy, Oracle Health (Cerner), Epic Systems Corporation, and McKesson Corporation.
In April 2026, Johns Hopkins Medicine and the American Telemedicine Association launched the Licensure Innovation for Telehealth Transformation (LIFTT) Initiative to address interstate licensing barriers and improve access to telehealth services. The initiative aims to support continuity of virtual care and access to specialized medical expertise, particularly for rural and underserved patient populations, reinforcing the industry's focus on expanding scalable telemedicine delivery.
The global telemedicine market is experiencing accelerated expansion, driven primarily by the rising prevalence of chronic medical conditions requiring continuous clinical management, such as diabetes, cardiovascular disease, and mental health disorders. Telemedicine platforms enable remote patient monitoring (RPM) and virtual consultations, significantly reducing hospital readmission rates and overall healthcare delivery costs.
In the U.S., the Centers for Medicare & Medicaid Services (CMS) governs telemedicine reimbursement under Medicare and Medicaid, ensuring accessibility and compliance. The Office for Civil Rights (OCR) under the U.S. Department of Health and Human Services (HHS) enforces the Health Insurance Portability and Accountability Act (HIPAA), establishing strict patient data privacy standards for virtual care platforms.
A primary restraint facing the telemedicine market involves complex regulatory compliance frameworks governing patient data privacy, cybersecurity standards, and cross-border medical licensing. Complying with strict regulations like HIPAA in the United States and GDPR in the European Union requires significant capital investment in encrypted cloud infrastructure and secure video transmission architecture.
Additionally, fragmented state-level medical licensing requirements in North America restrict physician flexibility to deliver virtual consultations across state borders. Limited high-speed broadband infrastructure in rural and underdeveloped regions also creates a digital divide, constraining telemedicine adoption among underserved patient populations.
The market is undergoing a major technological transformation driven by artificial intelligence (AI) integration, asynchronous (store-and-forward) diagnostic workflows, and wearable remote patient monitoring devices. AI-powered algorithms are increasingly integrated into virtual triage systems, aiding clinicians in early disease detection, automated symptom checking, and personalized treatment planning.
Simultaneously, asynchronous modalities allow patients to transmit medical history, imaging, and diagnostic data securely to specialists for review outside real-time video sessions, optimizing clinical workflows and reducing provider burnout.
|
Segmentation |
Details |
|
By Type |
Product and Services |
|
By Modality |
Asynchronous, Synchronous, and Others |
|
By Application |
Teleradiology, Telepathology, Teledermatology, Telepsychiatry, Telecardiology, and Others |
|
By End User |
Healthcare Facilities, Homecare, and Others |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South and Central America: Brazil, Argentina, and the rest of South and Central America |
Based on type, the market is categorized into products and services. Services command the largest market share of 64.87% in 2025, propelled by expanding clinical consultation volumes and remote chronic disease management programs. Products represent the fastest-growing sub-segment, supported by healthcare provider investments in EHR-integrated telehealth software platforms.
Based on modality, the market is categorized into synchronous, asynchronous, and others. Synchronous telemedicine holds the largest share of 58.29% in 2025 due to widespread patient preference for real-time video and audio consultations with physicians. Asynchronous telemedicine represents the fastest-growing sub-segment, driven by its flexibility in store-and-forward medical imaging, dermatology, and diagnostic report transmission.
Based on application, the market is categorized into telepsychiatry, telecardiology, teleradiology, telepathology, teledermatology, and others. Telepsychiatry accounts for the largest application share of 28.48% in 2025, supported by high demand for outpatient behavioral health services and reduced stigma surrounding virtual therapy. Telecardiology represents the fastest-growing application sub-segment, propelled by rising cardiovascular disease rates and advancements in wearable ECG and remote blood pressure monitoring devices.
Based on end user, the market is categorized into healthcare facilities, homecare, and independent practices. Healthcare facilities (hospitals and health systems) generate the largest revenue share in 2025, utilizing integrated telehealth platforms to expand outpatient access and manage bed capacity. Homecare represents the fastest-growing end-user segment, driven by senior patient preferences for aging-in-place and continuous remote patient monitoring.
By region, the market has been classified into North America, Europe, Asia Pacific, the Middle East & Africa, and South and Central America.
North America held the largest regional revenue share of 42.50% in 2025, with a valuation of USD 121.89 billion, and is projected to expand at a CAGR of 16.82% through 2033. According to Kings Research, regional leadership is driven by mature digital health infrastructure, favorable Medicare/Medicaid reimbursement coverage, high smartphone and 5G penetration, and a strong presence of major market leaders like Teladoc Health, Amwell, and Doximity. Strong regulatory support from HHS and CMS further solidifies North America's dominant position.
According to Kings Research, Asia Pacific is projected as the fastest-growing regional market with a CAGR of 17.52% over the forecast period from 2026 to 2033. Growth is fueled by rapid digital infrastructure expansion, government-backed e-health initiatives in China, India, and Japan, rising chronic disease rates, and expanding rural populations seeking specialized remote medical consultations.
According to Kings Research, Europe represents a major revenue hub, supported by centralized national healthcare systems, increasing integration of digital health tools in primary care across the UK, Germany, and France, and strict EU GDPR compliance standards ensuring secure patient health data transfer. The Middle East & Africa region is witnessing progressive market expansion, driven by GCC government investments in smart hospital infrastructure, national digital transformation agendas, and expanding mobile health app adoption in urban centers. South and Central America is experiencing steady growth in telemedicine adoption, led by Brazil and Mexico, propelled by healthcare access expansion initiatives in remote communities, rising smartphone adoption, and private health sector investments in virtual consultation platforms.
The telemedicine industry is characterized by a large number of participants, including established corporations and rising organizations. Competition in the market is driven by technological advancements, strategic partnerships, mergers and acquisitions, and continuous product innovations.
Companies are focusing on expanding their service offerings, enhancing user experience, and integrating AI, ML, and cloud-based solutions to improve telehealth efficiency.
Market participants are increasingly investing in R&D to enhance telemedicine capabilities, such as real-time data analytics, remote surgery, and personalized virtual consultations. Additionally, collaborations with healthcare institutions, insurance providers, and government agencies are expanding the accessibility of telemedicine.
Competition in the telemedicine market is expected to intensify as consumer demand for convenient and cost-effective healthcare continues to rise, leading to further advancements and market growth.
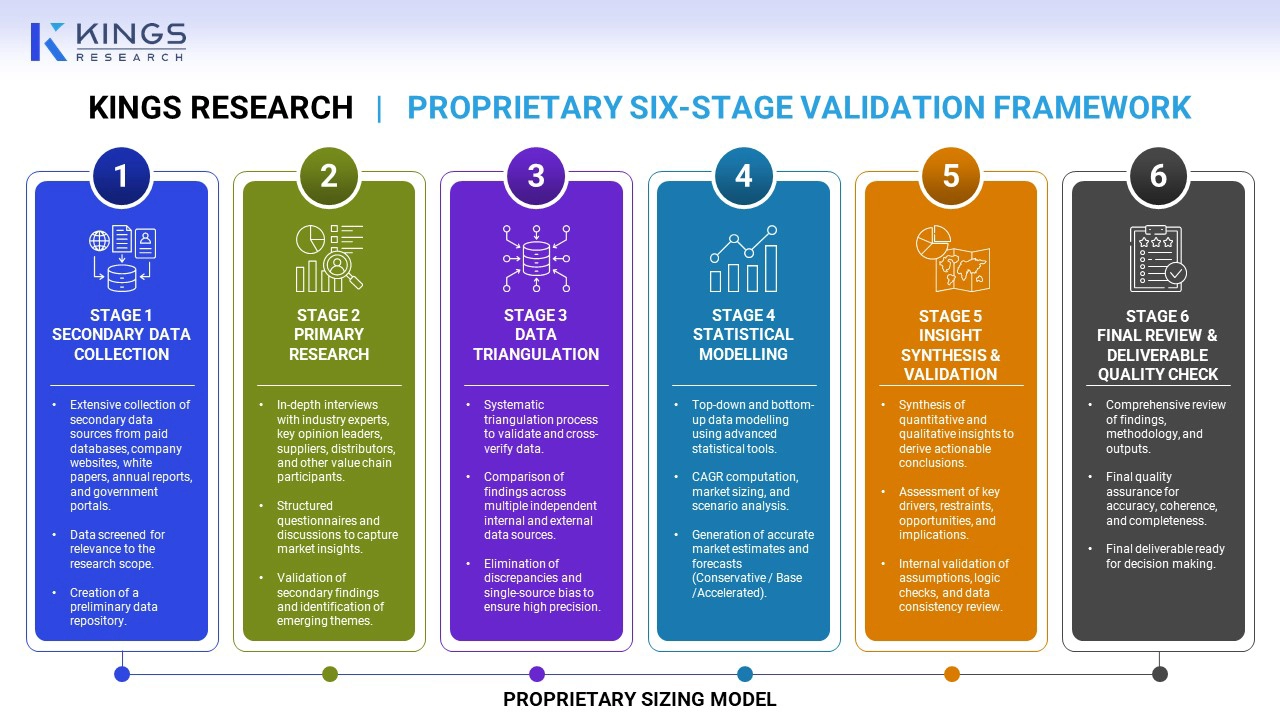
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
We deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Antriksh is an experienced analyst specializing in cross-domain research across diverse industries. With a strong foundation in data analysis and statistical interpretation, he delivers insightful market reports that guide strategic decision-making. Antriksh excels in conducting primary research, with a focus on identifying trends and understanding consumer behavior. Thriving in dynamic and high-pressure environments, he combines analytical expertise with a commitment to delivering impactful outcomes. Beyond his professional pursuits, Antriksh's passion for travel fuels his curiosity and broadens his perspectives, enriching his ability to uncover unique insights that enhance his research capabilities. He is equally adept at synthesizing quantitative findings with qualitative context, which allows him to present holistic viewpoints to clients. His disciplined work ethic and intellectual agility make him a trusted partner in navigating market uncertainties. He consistently seeks out new methodologies to refine his analytical toolkit, and his ability to communicate complex insights clearly ensures stakeholders act confidently on his recommendations.
With many years of consulting experience across global pharma, biotech, and MedTech markets, Minaz brings deep domain expertise, strategic clarity, and analytical rigor to every engagement. She has led 130+ consulting assignments spanning market entry, competitive landscaping, and portfolio prioritization, helping clients navigate complex, high-stakes decisions with confidence. Known for her ability to synthesize primary and secondary research into executive-ready recommendations, Minaz has built forecasting models and market sizing frameworks that have informed multi-million dollar investment decisions in oncology, diagnostics, and peptide therapeutics. Beyond her analytical strength, Minaz is a trusted client partner, translating complex datasets into clear, actionable insights for senior stakeholders. She currently leads a team of research analysts, driving business expansion, and shaping client engagement strategy.


