
Inquire Now
Key Strategic Points
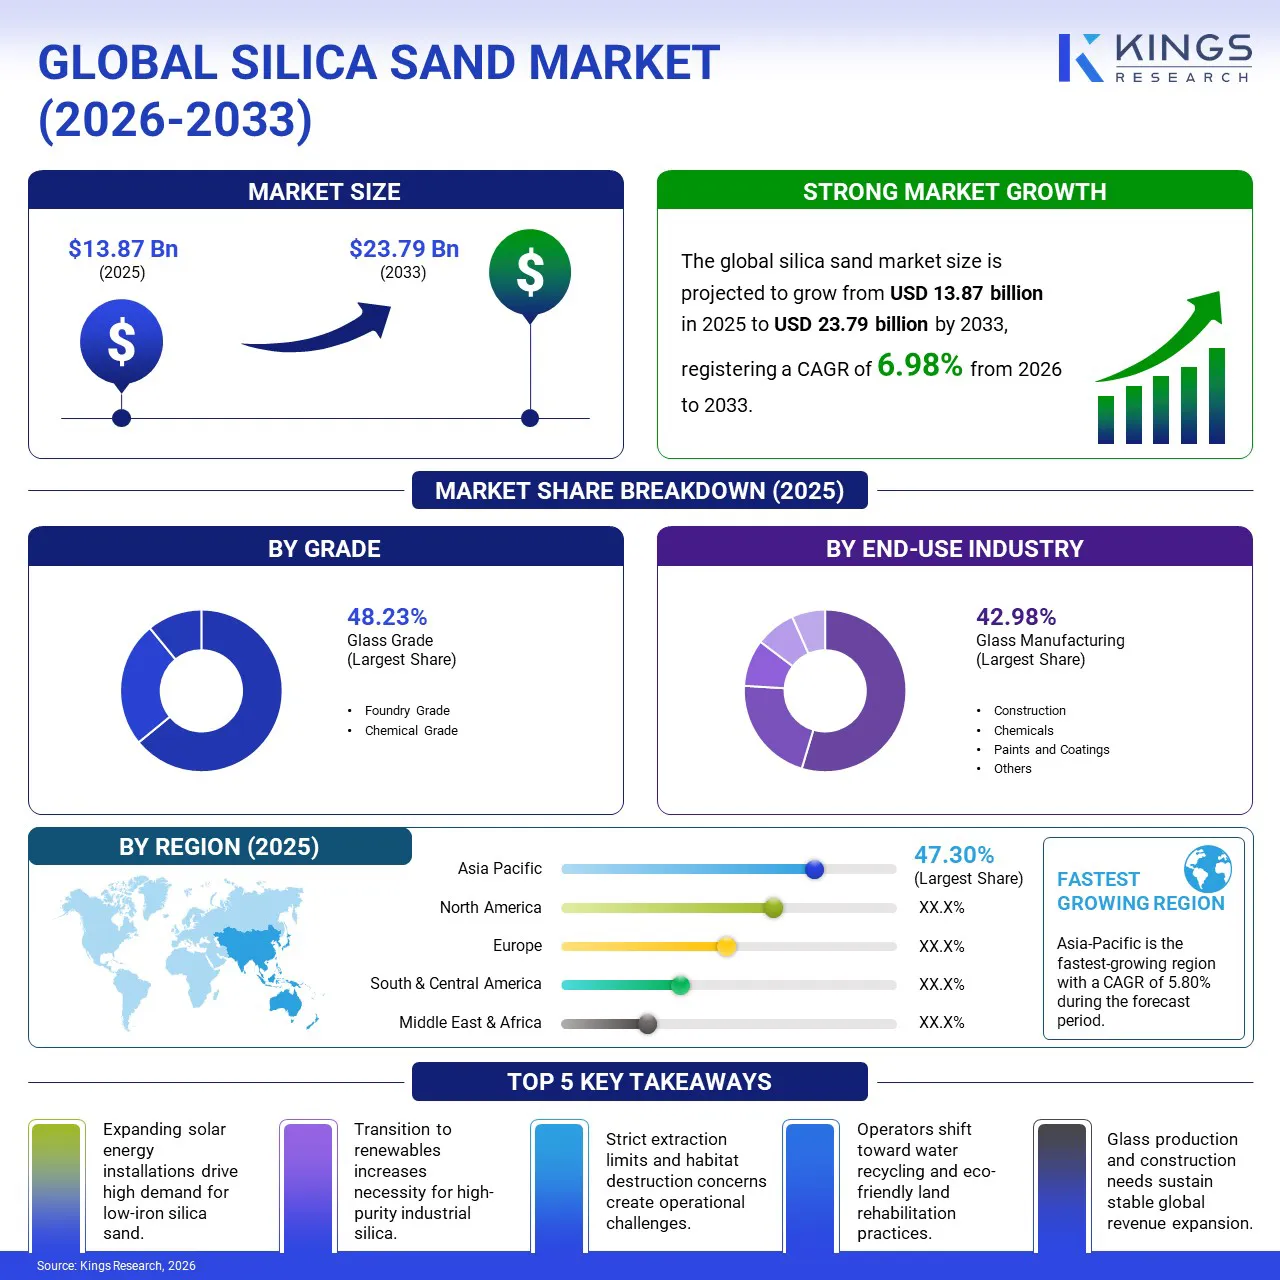
According to Kings Research, the global silica sand market size was valued at USD 13.87 billion in 2025 and is projected to grow to USD 23.79 billion by 2033, exhibiting a CAGR of 6.98% during the 2026-2033 forecast period, with Asia Pacific accounting for 47.30% of the global market value in 2025.
The increasing adoption of solar energy globally is driving demand for ultra-clear, low-iron silica sand, essential for high-quality solar panel glass production, positioning it as a key driver of the market.
Major companies operating in the silica sand industry, selected for their production scale, purity specialization, and geographic reach, include Covia Holdings LLC, APEX Geoscience Ltd, Mitsubishi Corporation, Sil Industrial Minerals, Sibelco, JFE Mineral & Alloy Company, Ltd, Quarzwerke GmbH, Badger Mining Corporation, Preferred Sands, Inc., Holcim, McLaren Minerals Limited, Srinath Enterprises, Zillion Sawa Minerals Pvt. Ltd., Indus Minechem, and Uma Minerals.
Growth is registering significant momentum driven by rising demand for high-purity silica (>99.6% SiO₂), essential in manufacturing solar glass, semiconductors, and energy storage technologies. The need for ultra-clear glass and advanced electronic components increases as the adoption of clean energy accelerates globally.
The market is poised for expansion, supported by innovations in extraction and processing, as well as increasing investments in green infrastructure. The role of high-grade silica sand in enabling low-carbon technologies positions it as a critical industrial material for the future.
The increasing adoption of solar energy is driving demand for ultra-clear, low-iron silica sand, a vital raw material for producing high-quality solar panel glass. This surge in demand is supported by the rapid expansion of solar power installations and the increasing need for more efficient and durable solar panels.
According to the International Energy Agency (IEA), global solar PV additions rose by almost 30% year-on-year in 2024, reaching approximately 550 GW, while total installed solar PV capacity worldwide reached an estimated 2.2 TW. Solar PV and wind together accounted for 95% of overall renewable capacity growth in 2024, highlighting the continued expansion of the solar industry and its associated demand for high-quality solar glass materials.
The continued expansion of solar PV installations is directly supporting demand for premium-grade silica sand with minimal iron content among solar glass manufacturers, as low-iron silica is required to produce highly transparent glass that allows greater transmission of sunlight. Recent developments in the solar industry are further reinforcing this demand.
In October 2025, the IEA reported that solar PV is expected to account for around 80% of global renewable power capacity growth over the following five years, driven by declining costs and faster permitting. These developments are expected to sustain demand for high-purity, low-iron silica sand as solar manufacturers continue expanding photovoltaic production and capacity.
Rising construction activity and urbanization are fueling steady demand for silica sand across concrete production, architectural glass, and infrastructure development. As urban populations expand globally, particularly across Asia Pacific, the need for construction-grade silica sand continues to rise alongside broader building material demand.
The exponentially growing demand for consumer electronics and semiconductor chips, most of which are made from silicon derived from silica sand, is driving demand for ultra-high-purity grades. This trend is reinforcing the market's positioning beyond traditional glass and construction applications into advanced electronics manufacturing.
Innovations in extraction and processing technologies are improving yield, purity consistency, and cost-efficiency for silica sand producers. These advancements are enabling companies to access previously uneconomical reserves and meet the tightening purity specifications required for solar glass and semiconductor applications.
Environmental concerns pose a significant challenge to the silica sand market, as mining operations can result in habitat destruction, water pollution, and excessive land use. These environmental impacts often lead to stricter regulations, community opposition, and delays in project approvals. Companies can adopt sustainable mining practices, such as implementing water recycling systems, using less invasive extraction methods, and restoring mined lands.
Additionally, investing in environmentally friendly technologies and complying with regulatory standards can help minimize environmental damage and ensure long-term market viability. Established mining regions face gradually depleting high-purity reserves, increasing reliance on discoveries and geographically distant deposits to sustain supply.
This dynamic is reflected in Australia's position as a major exporter of high-purity sand despite contributing only around 1% of global production volume, underscoring how reserve quality, rather than production scale alone, increasingly shapes competitive positioning and long-term supply security.
A key trend in the market is the increasing focus on sustainability and rehabilitation. Mining companies are adopting environmentally friendly practices, prioritizing rehabilitation-focused mining methods to minimize ecological disruption. These practices not only help mitigate environmental impacts but also ensure compliance with stringent regulatory requirements, facilitating the approval process for projects.
Amid growing environmental concerns, this trend is becoming crucial for securing long-term operational licenses, maintaining community support, and meeting the demands of environmentally conscious investors and consumers. In January 2024, VRX Silica focused on addressing the growing global demand for silica sand, crucial for glass, concrete, and electronics production. With urbanization and population growth, the company's strategic Western Australian projects aim to meet rising global demand.
|
Segmentation |
Details |
|
By Grade |
Glass Grade, Foundry Grade, Chemical Grade |
|
By End-Use Industry |
Glass Manufacturing, Construction, Chemicals, Paints and Coatings, Others |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South and Central America: Brazil, Argentina, and the rest of South and Central America |
Based on grade, the market is categorized into glass grade, foundry grade, and chemical grade. The glass grade segment holds the largest share of 48.23% in the market, driven by rising demand for high-quality silica sand in flat, container, and solar glass manufacturing globally.
Based on end-use industry, the market is segmented into glass manufacturing, construction, chemicals, paints and coatings, and others. The glass manufacturing segment holds the largest share of 42.98% in the market, supported by expanding automotive and construction industries and increasing demand for architectural and automotive glass products.
The construction segment is expected to witness the highest growth, supported by sustained infrastructure development and rising demand for concrete and building materials, while chemicals, paints, and coatings represent smaller but stable demand pools driven by silica sand's use as a filler and functional additive in industrial formulations.
Based on region, the global market has been classified into North America, Europe, Asia Pacific, the Middle East & Africa, and South & Central America.
Asia Pacific accounted for a market share of around 47.30% in 2025 and has the highest growth rate of 7.12% CAGE in the forecasting period. It is largely due to rapid industrialization, growing construction activities, and strong demand from manufacturing sectors like glass, ceramics, and electronics.
The region benefits from a high concentration of silica sand reserves, coupled with well-established supply chains and cost-effective production. According to the Queensland Government, Australia possesses extensive silica sand resources, including some of the world's highest quality deposits, predominantly located in Queensland and Western Australia.
Although Australia contributes roughly 1% to global production, it stands out as a major exporter due to its high-purity sand and robust export infrastructure. Additionally, rising urbanization, infrastructure development, and expansion of the renewable energy sector, particularly in solar power, contribute to Asia Pacific's position as a leader in both consumption and production of silica sand.
North America is poised for considerable growth over the forecast period. North America is becoming a rapidly growing hub for the silica sand industry, driven by increasing demand from industries such as construction, glass manufacturing, and renewable energy.
The region benefits from abundant high-quality silica sand reserves, making it a key player in the global supply chain. Several industries are focusing on sustainability and technological advancements, particularly in the solar and clean energy sectors. North America's strategic location and access to resources position it as a critical market for silica sand production and innovation.
South & Central America is emerging as a strategically important source of high-purity silica, anchored by discoveries such as Homerun Resources' Belmonte project in Bahia, Brazil. This growing resource base positions the region as a rising supplier to global glass and semiconductor manufacturing supply chains, complementing more established production hubs in Asia Pacific and North America.
Europe's market is supported by established glass manufacturing capacity and regulatory frameworks under EU Directive 2006/21/EC governing extractive waste management, which shapes how producers across France, Germany, and the broader region manage environmental compliance alongside steady industrial demand.
Middle East & Africa remains an earlier-stage market, with growth expected to be supported by rising construction activity and gradual investment in domestic glass and industrial manufacturing capacity across the region.
Companies in the silica sand market are actively expanding their operations to meet rising global demand, particularly from the glass, solar, and construction industries. They are investing in acquiring high-purity silica sources, enhancing processing capabilities, and improving logistics networks.
Many are also focusing on sustainability, ensuring low environmental impact and regulatory compliance. These strategic efforts aim to secure long-term supply chains and cater to emerging applications in renewable energy and advanced manufacturing.
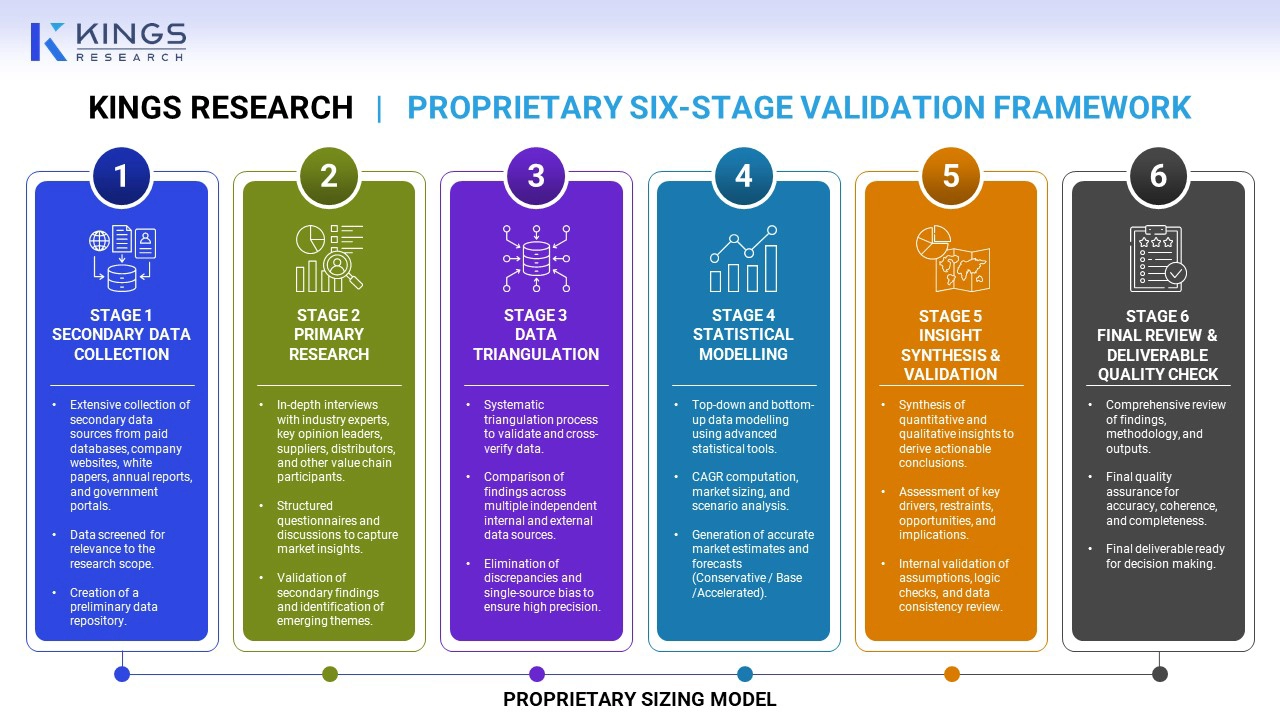
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Sharmishtha is a budding research analyst with a strong commitment to achieving excellence in her field. She brings a meticulous approach to every project, delving deep into details to ensure comprehensive and insightful outcomes. Passionate about continuous learning, she strives to enhance her expertise and stay ahead in the dynamic world of market research. Beyond work, Sharmishtha enjoys reading books, spending quality time with friends and family, and engaging in activities that foster personal growth. Her dedication to precision ensures that no critical detail is overlooked, and her analytical rigor consistently produces reliable, evidence-based conclusions. Sharmishtha's proactive curiosity drives her to explore emerging research methodologies, which she readily applies to deliver fresh perspectives on complex market questions. Her collaborative nature and openness to constructive feedback make her a dependable team player. She balances technical accuracy with clear communication, ensuring her insights are actionable for clients and stakeholders alike.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


