
Inquire Now
Key Strategic Points
According to Kings Research, the global rare earth metals recycling market size was valued at USD 311.4 million in 2025 and is projected to reach USD 679.5 million by 2033, exhibiting a CAGR of 10.30% during the 2026-2033 forecast period.
Kings Research attributes this growth to increasing demand for rare earth metals in industries such as electronics, renewable energy, and electric vehicles. Governments and industries are also implementing stricter regulations on waste management and recycling, leading to the widespread adoption of advanced recycling technologies.
Major companies operating in the global rare earth metals recycling industry include Solvay, Hitachi, Ltd., Umicore, Lynas Rare Earths Ltd., Geomega Resources Inc., Shenghe Resources Holding Co., Ltd., Nissan Motor Co., Ltd., Mitsubishi Electric Corporation, Avalon Advanced Materials Inc., MP Materials Corp., Energy Fuels Inc., OSRAM SYLVANIA Inc., REEcycle, Inc., and American Rare Earths Limited.
The shift toward sustainable technologies is highlighting the need for efficient recycling to reduce dependence on mining and minimize environmental impact. The volatility of rare earth metal prices and the geopolitical risks associated with their supply are prompting companies to seek secondary sources, further fueling market growth.
In January 2026, Cyclic Materials secured USD 75 million in Series C funding to accelerate the development of a secure and resilient rare earth supply chain. The investment is expected to support the company’s expansion of rare earth recycling operations and commercial-scale facilities, strengthening the recovery of critical rare earth elements from end-of-life products and reducing dependence on primary sources.
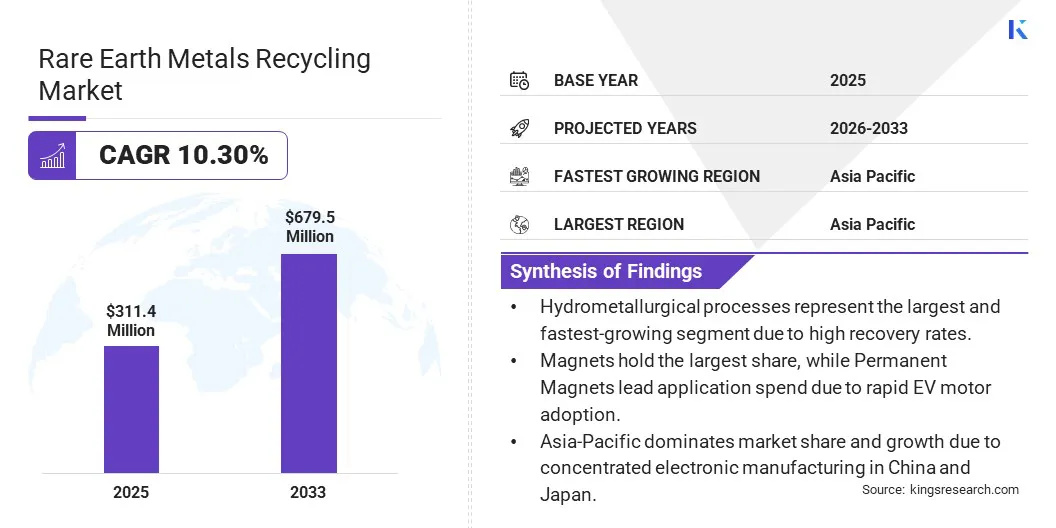
Advancements in recycling technologies have significantly improved rare earth metal recovery. Hydrometallurgy, which uses aqueous solutions for metal separation, and pyrometallurgy, which employs high temperatures for refining, have increased efficiency and purity, propelling growth in the rare earth metals recycling market. Hydrometallurgical processes in particular represent the largest and fastest-growing technology segment, owing to their high recovery rates relative to alternative processes.
Additionally, innovations in solvent extraction, bioleaching, and ion-exchange processes enable more precise recovery from complex waste, expanding the range of materials that can be economically processed.
In June 2026, USA Rare Earth commissioned a hydrometallurgical demonstration facility in Colorado to advance heavy rare earth oxide production, with the facility also testing rare earth magnet swarf recycling.
As industries and governments adopt sustainable practices, the circular economy model promotes material reuse, refurbishment, and recycling to extend product life cycles and reduce waste. This reflects a broader shift away from the traditional take-make-dispose approach toward recovering rare earth metals from end-of-life products such as electronics, wind turbines, and EV batteries for reintegration into the supply chain.
This approach minimizes environmental impact and reduces reliance on resource-intensive primary mining.
In December 2024, Cyclic Materials Inc. partnered with Circulor, a leading supply chain traceability provider, to establish the first end-to-end traceability for rare earth elements. This partnership sets a new standard for transparent REE recycling, promoting responsible, sustainable, and secure sourcing.
Governments worldwide are strengthening regulatory frameworks and offering financial incentives to expand domestic rare earth recycling capacity, reducing reliance on primary mining and imported supply. Programs supporting critical minerals recovery are helping recyclers scale operations and secure long-term offtake agreements with downstream manufacturers.
The volatility of rare earth metal prices and geopolitical risks associated with concentrated global supply are prompting manufacturers to diversify sourcing strategies. Companies across electronics, automotive, and renewable energy sectors are increasingly turning to secondary, recycled sources to secure stable, domestically available rare earth supply, reducing exposure to trade restrictions and single-region dependency.
Rare earth elements are widely used in electronic devices, batteries, magnets, and fluorescent lights, often in small quantities and complex alloys. Their integration through advanced manufacturing complicates separation and extraction during recycling, impeding progress in the rare earth metals recycling market.
The need for specialized equipment, such as automated sorting systems or chemical leaching processes, further increases the difficulty and cost of recycling. Additionally, the low concentration of rare earth metals in products necessitates processing large waste volumes to recover minimal amounts, reducing overall efficiency.
This challenge can be addressed through significant advancements in technology and process optimization. Key strategies include developing efficient and selective separation methods, such as advanced chemical leaching, hydrometallurgical processes, and solvent extraction, to isolate specific rare earth elements. Standardizing product structures and using fewer, more easily separable materials can also streamline recycling, while cross-industry collaboration and closed-loop recycling systems can improve e-waste and scrap collection infrastructure.
Recyclers face constraints from limited and inconsistent access to end-of-life rare earth-bearing products. Meaningful volumes of end-of-life electric vehicle motors, a major future feedstock source, are not yet entering recycling streams at scale, leaving recyclers reliant on production scrap, spent magnets, and batteries in the near term. This feedstock uncertainty can limit capacity utilization and complicate long-term investment planning for recycling infrastructure.
The rare earth metals recycling market is evolving into a strategically important secondary supply source as manufacturers and governments seek to reduce dependence on concentrated primary supplies. Hydrometallurgical processing is gaining prominence due to its higher recovery rates, while supply chain traceability is becoming increasingly important for demonstrating the provenance and sustainability of recycled rare earth materials. Strategic partnerships among recyclers, refiners, and OEMs are also expected to strengthen as feedstock availability improves. Among applications, permanent magnets are positioned for strong growth, while batteries represent a rapidly expanding source of recyclable rare earth materials.
|
Segmentation |
Details |
|
By Technology |
Hydrometallurgical, Pyrometallurgical |
|
By Source |
Fluorescent lamps, Magnets, Batteries, Others (Industrial process, Permanent Magnet Scrap) |
|
By Application |
Alloy, Catalyst, Permanent Magnets, Ceramics, Others (Phosphor, Polishing materials, Glass) |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, Rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South & Central America: Brazil, Argentina, Rest of South & Central America |
Based on technology, the market is categorized into hydrometallurgical and pyrometallurgical processes. The hydrometallurgical segment represents both the largest and fastest-growing technology segment, due to its high recovery rates and efficient, environmentally friendly extraction of rare earth metals from electronic waste and other sources.
Based on source, the market is segmented into fluorescent lamps, magnets, batteries, and others (industrial process, permanent magnet scrap). The magnets segment holds the largest share, attributed to strong demand for rare earth metals in producing high-performance permanent magnets for electric motors, wind turbines, and other high-tech applications. The batteries segment is the fastest-growing source segment, driven by rising volumes of end-of-life NiMH and lithium-ion batteries entering recycling streams.
Based on application, the market is segmented into alloy, catalyst, permanent magnets, ceramics, and others (phosphor, polishing materials, glass). The permanent magnets segment leads both in current application spend and forecast growth, owing to rapid EV motor adoption and rising demand for rare earth metals in energy-efficient motors and renewable energy technologies such as wind turbines.
Based on region, the global market is classified into North America, Europe, Asia-Pacific, MEA, and South & Central America.
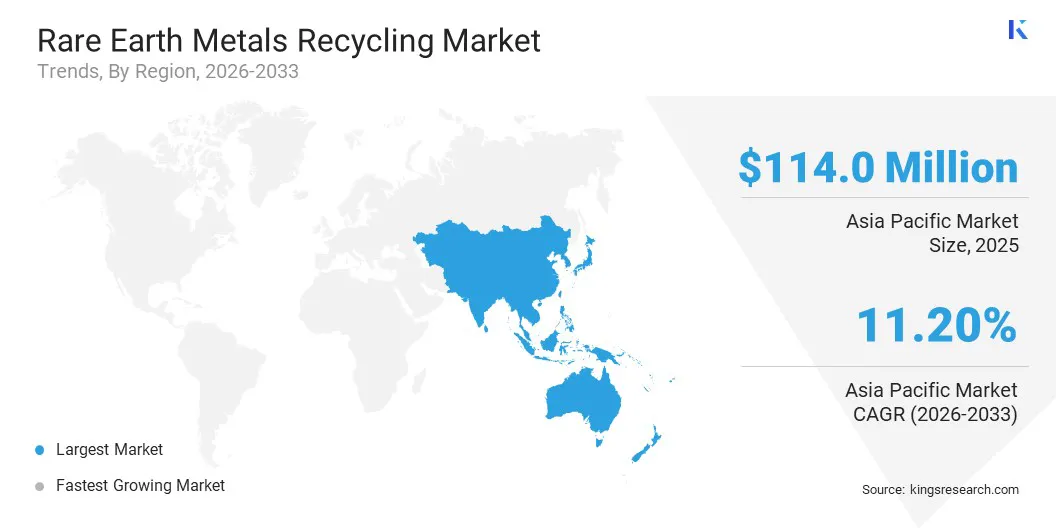
Asia-Pacific's rare earth metals recycling market share stood at around 36.61% in 2025, valued at USD 114.0 million, and the region is anticipated to grow at the fastest CAGR of 11.20% over the forecast period. This regional dominance is attributed to concentrated electronic manufacturing in China and Japan, alongside the region's strong manufacturing base across electronics, automotive, and renewable energy sectors.
China, Japan, and South Korea are at the forefront of rare earth metal production and recycling, supported by technological advancements and large-scale recycling facilities. Growing emphasis on circular economy practices and government incentives are further stimulating regional market growth.
North America's rare earth metals recycling industry continues to grow, bolstered by increasing government support for sustainability initiatives and the need for secure domestic supply chains.
The U.S., in particular, is prioritizing reduced reliance on foreign sources for critical raw materials such as rare earth metals, which are essential to electronics, defense, and clean energy applications. Rising demand for electric vehicles and renewable energy systems, which require rare earth metals for batteries, motors, and magnets, is further fueling the need for recycling solutions, and private sector investment is increasing as companies recognize the economic and environmental benefits of rare earth metal recycling.
In July 2026, the U.S. government authorized measures to restrict exports of e-waste containing critical minerals, including rare earth-bearing materials, with the aim of directing more mineral-rich waste toward domestic recycling. The move is intended to strengthen U.S. critical-mineral supply chains, reduce dependence on foreign sources, and support domestic recovery and recycling capacity.
Across Europe, MEA, and South & Central America, the rare earth recycling market is gaining momentum as regions seek to strengthen critical-mineral supply security and reduce dependence on concentrated global sources. Europe is emphasizing circular recovery and recycling infrastructure, while MEA is attracting investment to develop domestic critical-mineral value chains
The competitive landscape of the rare earth metals recycling market is marked by a mix of established players, emerging innovators, and new entrants focused on advancing recycling technologies and securing sustainable supply chains.
Companies are leveraging hydrometallurgy, pyrometallurgy, and chemical leaching to improve the efficiency and cost-effectiveness of rare earth metal recovery. There is a strong emphasis on developing environmentally friendly and energy-efficient processes to reduce environmental impact.
Companies are forming strategic partnerships and collaborations to enhance their capabilities and ensure a stable supply of rare earth elements.
How We Gather This Information
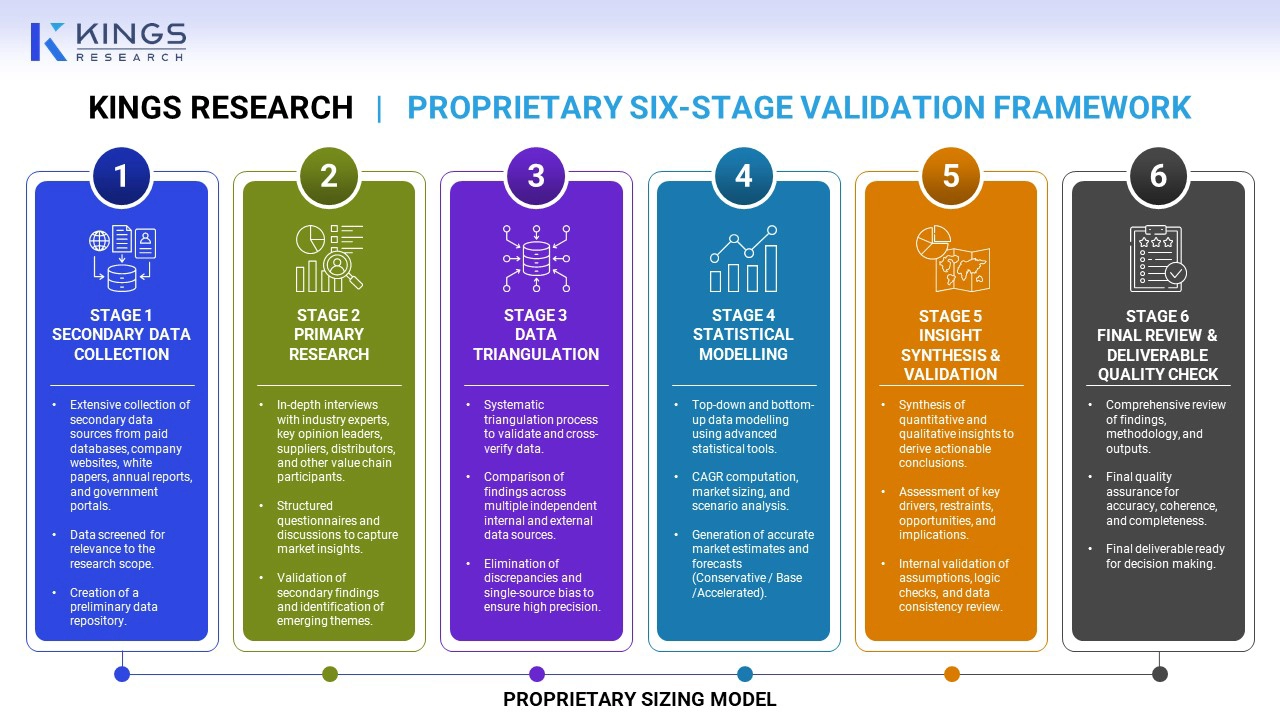
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Over the years, Versha brings over 15 years of experience managing consulting assignments across industries, including Food and Beverage, Consumer Goods, ICT, Aerospace, and more. Her work has spanned diverse sectors. Her cross-domain expertise and adaptability make her a versatile and dependable professional. She is known for her keen business insight and foresight. With sharp analytical skills and a curious mindset, Versha excels at transforming complex data into actionable insights. She has a proven track record of unraveling market dynamics, identifying trends, and delivering tailored solutions to meet client needs. As a skilled leader, Versha has successfully mentored research teams and directed projects with precision, ensuring high-quality outcomes. Her collaborative approach and strategic vision enable her to turn challenges into opportunities and consistently deliver impactful results. Whether analyzing markets, engaging stakeholders, or crafting strategies, Versha draws on her deep expertise and industry knowledge to drive innovation and deliver measurable value.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


