
Inquire Now
Key Strategic Points
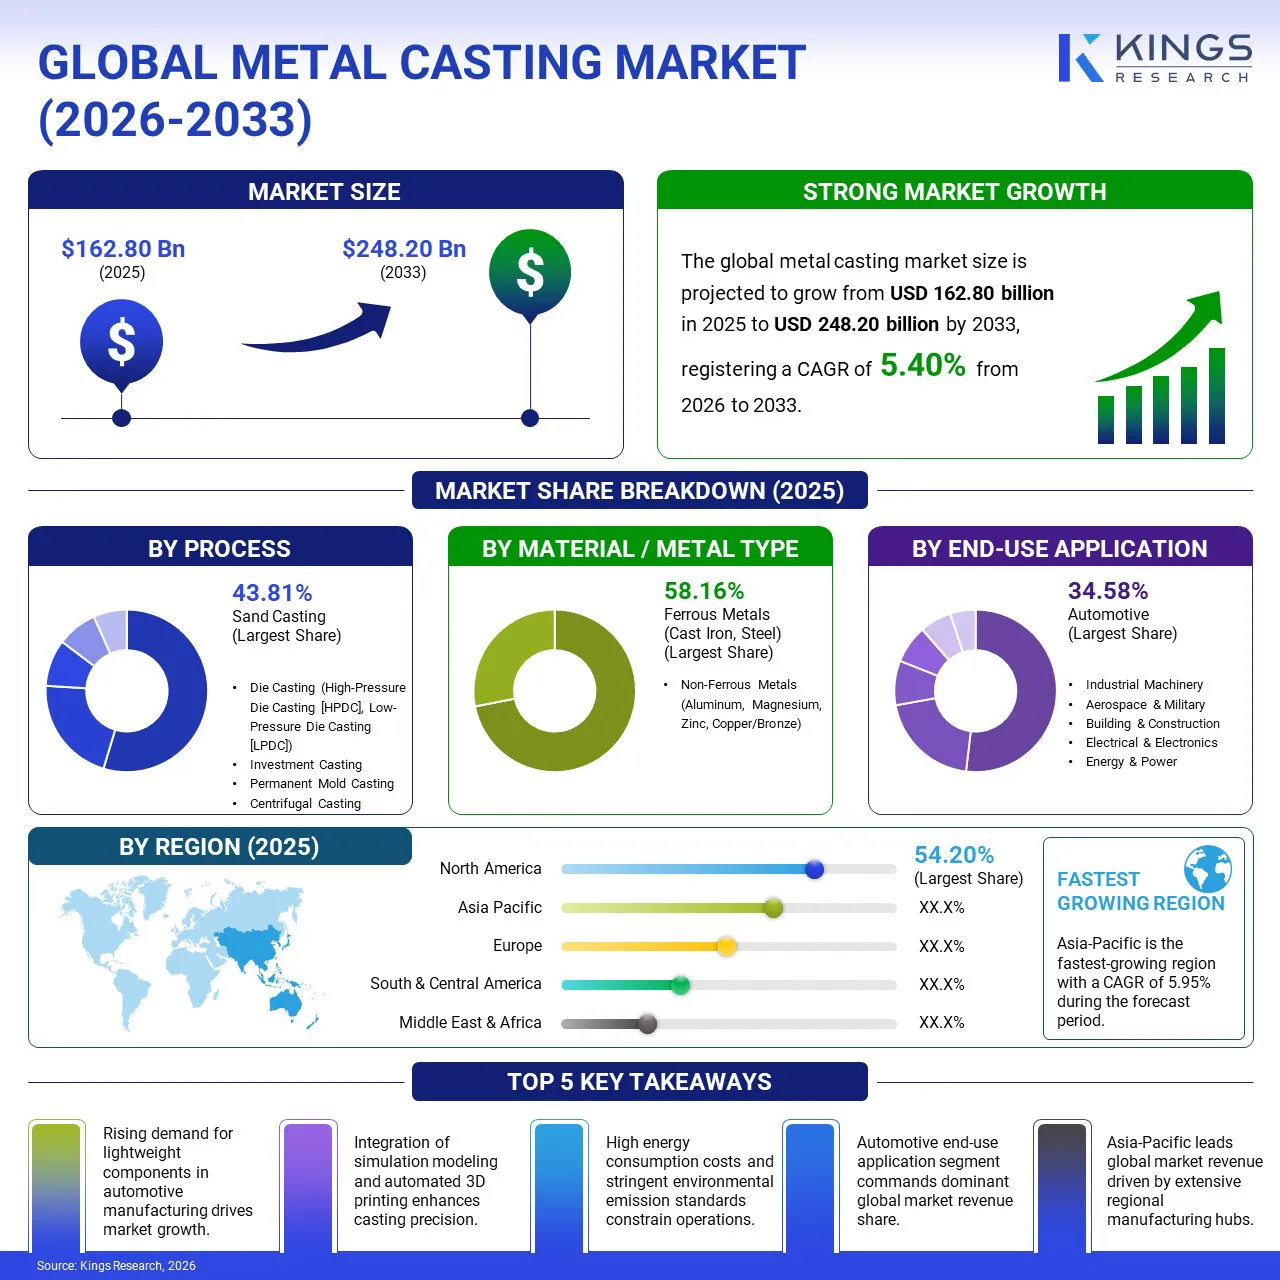
According to Kings Research, the global metal casting market size is projected to grow from USD 162.80 billion in 2025 to USD 248.20 billion by 2033, registering a CAGR of 5.40% from 2026 to 2033.
The growth of the market is primarily driven by the increasing demand for lightweight materials in automotive manufacturing, particularly for electric vehicles (EVs). The shift toward EVs requires advanced casting technologies for structural components, prompting investments in facilities and production capacity.
Additionally, the growing infrastructure development in emerging markets, particularly in Asia-Pacific, is fueling demand for high-quality cast products used in construction and industrial applications.
Major companies operating in the metal casting industry are Dynacast, Nemak, Aisin World Corp. of America, Omnidex, MINO Industry USA, Inc., Endurance Technologies Limited, Rheinmetall AG, Ryobi Die Casting (USA), Inc., Arconic, Alcast Technologies Ltd, UNI Abex, GF Casting Solutions, Gibbs, MES, Inc., POSCO, and others.
Rapid urbanization and ongoing infrastructure projects in emerging markets are fueling the demand for metal casting products. Cast metal components are essential in the construction of buildings, bridges, transportation systems, and other infrastructure projects that require durable and high-performance materials.
The ongoing expansion of infrastructure in developing economies, coupled with a growing emphasis on modernizing aging infrastructure in developed regions, is fueling market growth.
The automotive and aerospace industries are among the largest consumers of metal casting products. The need for lightweight and durable components in these sectors is significantly boosting the growth of the metal casting market.
Components such as engine blocks, transmission parts, and turbine blades require precise casting methods to meet strict performance standards. With the increasing focus on fuel efficiency, safety, and reduced emissions, the demand for high-performance cast parts in these industries continues to rise, boosting the growth of the market.
A significant challenge hindering the growth of the metal casting market is the rising cost of raw materials, particularly metals such as aluminum, steel, and cast iron. These costs are driven by global supply chain disruptions, fluctuating commodity prices, and trade policies.
Key players are adopting various strategies to address this challenge, including diversifying their supply sources, investing in advanced recycling technologies to reduce dependency on raw materials, and optimizing production processes to enhance efficiency.
Additionally, collaboration with suppliers and leveraging digital tools for inventory management helping stabalize cost and ensure a reliable material supply.
The global transition to renewable energy sources is contributing significantly to the growth of the metal casting market. Renewable energy technologies, such as wind turbines and solar energy systems, require high-quality, durable metal components for optimal performance.
For instance, turbine housings, wind tower components, and support structures are commonly produced through metal casting. As countries invest in renewable energy infrastructure to reduce carbon emissions and meet sustainability goals, the demand for cast components in the renewable energy sector is expected to expand.
|
Segmentation |
Details |
|
By Material |
Iron, Steel, Aluminum, Others |
|
By Process |
Sand Casting, Investment Casting, Die Casting, Gravity Casting, Others |
|
By Application |
Automotive & Transportation, Manufacturing, Others |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, U.K., Spain, Germany, Italy, Russia, Rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South America: Brazil, Argentina, Rest of South America |
Based on region, the global market has been classified into North America, Europe, Asia Pacific, Middle East & Africa, and Latin America.
The Asia Pacific metal casting market captured a substantial share of around 54.20% in 2025. The Asia-Pacific region is experiencing rapid industrialization and urbanization, particularly in countries such as China, India, and Southeast Asia.
This surge in infrastructure development, including the construction of roads, buildings, and transportation networks, significantly boosts the demand for metal casting products. These developments require durable, high-performance metal components, thereby contributing to the expansion of the regional market.
Additionally, Asia-Pacific is the largest producer and consumer of automobiles, with major automotive hubs in China, India, Japan, and South Korea.
The increasing demand for vehicles, particularly electric vehicles (EVs), is highlighting the need for high-quality cast components such as engine blocks, chassis, and transmission parts. As the automotive industry continues to grow in the region, it contributes significantly to market expansion.
The European metal casting industry is experiencing steady growth, driven by the region's strong focus on environmental sustainability. Europe is at the forefront of sustainability initiatives, with a robust regulatory framework designed to reduce carbon emissions and promote circular economy practices.
The European Green Deal and carbon neutrality goals have made sustainability a primary focus for the region’s manufacturing industries, including metal casting. The push for energy-efficient production, the adoption of recyclable metal materials, and the use of environmentally friendly casting technologies are becoming integral parts of the industry’s strategy.
As companies strive to meet stringent environmental standards, demand for metal casting solutions that reduce waste, improve energy consumption, and promote sustainable practices is surging.
The metal casting industry is characterized by a large number of participants, including both established corporations and emerging players. To accelerate growth and expand market share, leading companies are adopting strategies such as the expansion of operations and significant investments in their facilities.
These strategies enable companies to boost their production capacity, improve efficiency, and meet the increasing demand for high-quality metal cast products.
By expanding their manufacturing plants and upgrading technology, companies can optimize production processes, reduce costs, and enhance product offerings. These initiatives further enable players to cater to new market segments and geographical regions.
This investment in facilities and infrastructure is vital for companies aiming to strengthen their competitive edge and position themselves as industry leaders in a growing market.
Recent Developments
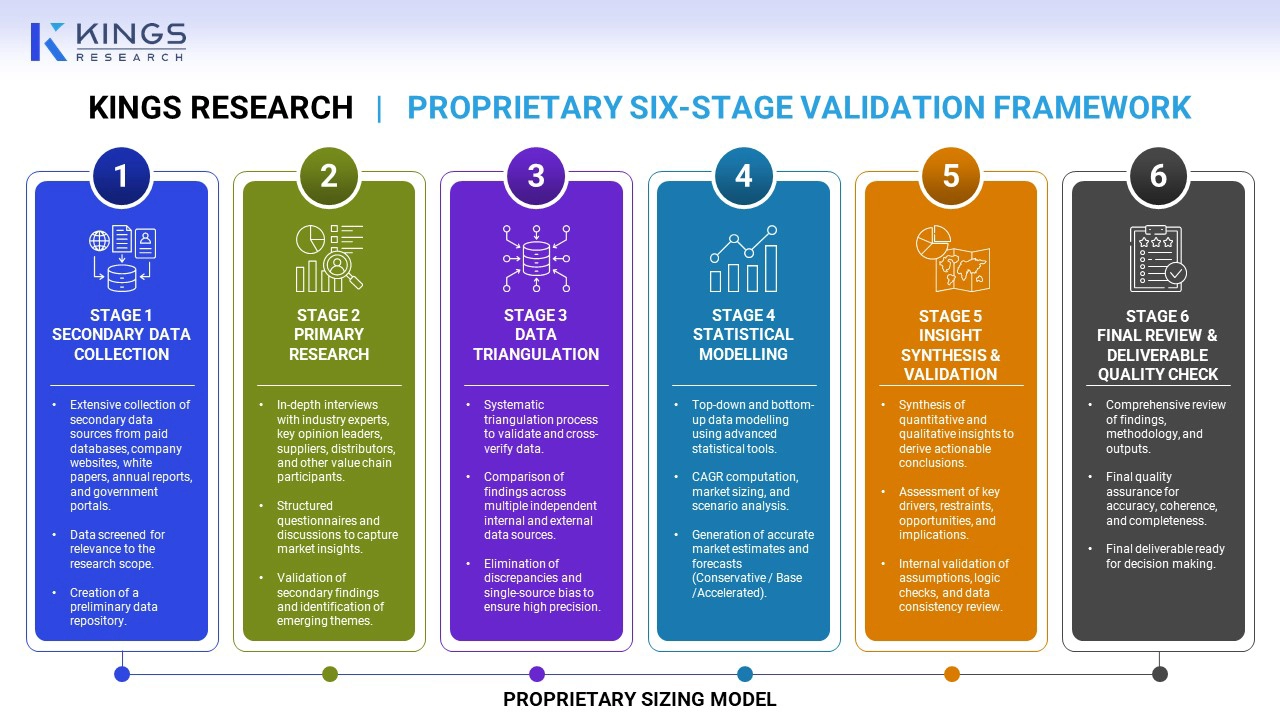
Our methodology triangulates insights from multiple independent and publicly available research databases, which are further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
 Custom Offerings
We deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Sunanda is a proficient research analyst with strong cross-domain expertise, excelling in identifying market trends and delivering insightful analyses across various industries, including consumer goods, food & beverages, healthcare, and more. Her ability to connect insights from diverse sectors enables her to offer actionable recommendations that support strategic decision-making in a range of business contexts. Sunanda's research is driven by thorough data analysis and her commitment to providing relevant, data-driven insights. Her keen eye for patterns allows her to spot emerging opportunities before they become mainstream. Sunanda's synthesis of cross-sector learnings often reveals unconventional solutions that clients find invaluable. She adapts her analytical frameworks to suit each industry's unique nuances, ensuring reports are both accurate and contextually relevant. Clients appreciate her ability to deliver crisp, actionable findings under tight deadlines, consistently exceeding expectations with her thoroughness and insight.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


