
Inquire Now
Key Strategic Points
The market encompasses the development, production, and distribution of devices that detect and measure moisture levels in the air. This market includes capacitive, resistive, and thermal conductivity sensors, integrated modules, and related calibration & maintenance services.
It serves sectors such as automotive, HVAC, healthcare, agriculture, and industrial automation. The market's scope covers both analog and digital sensors used in environmental monitoring, process control, and smart device applications. The report provides a comprehensive analysis of key drivers, emerging trends, and the competitive landscape expected to influence the market over the forecast period.
The global humidity sensor market size was valued at USD 3,326.2 million in 2024 and is projected to grow from USD 3,544.4 million in 2025 to USD 5,815.8 million by 2032, exhibiting a CAGR of 7.33% during the forecast period.
Rising HVAC adoption and industrial digital transformation drive the market by enabling precise climate control, energy efficiency, real-time monitoring, predictive maintenance, and smart IoT integration across diverse sectors.
Major companies operating in the humidity sensor industry are IST AG, dol-sensors A/S, OMEGA Engineering inc., Mifa Systems Pvt Ltd., Honeywell International Inc, amphenol, Texas Instruments Incorporated., Sensirion AG, TE Connectivity., Siemens, Teracom Ltd, Bosch Sensortec GmbH, Schneider Electric, Renesas Electronics Corporation., and Pyrotron (India) Inc.
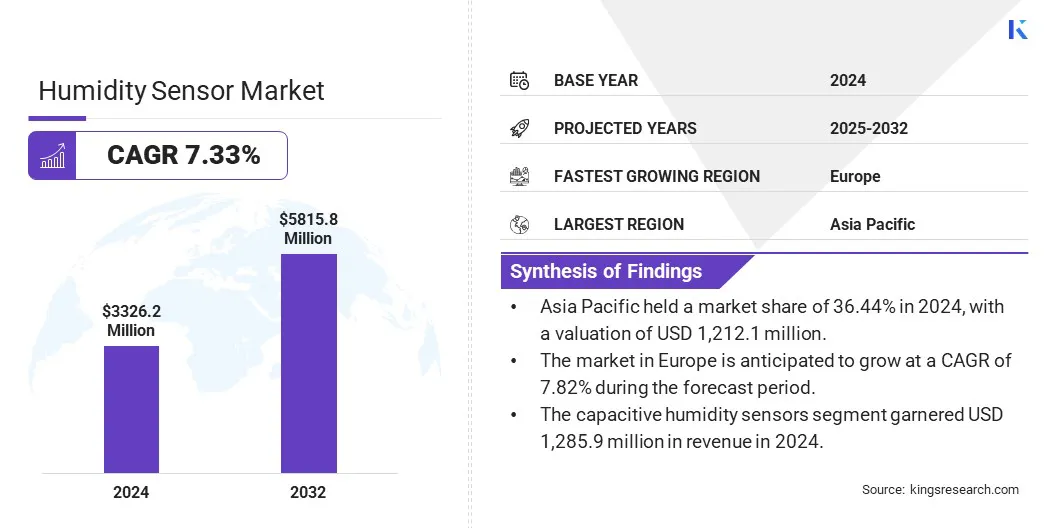
The rapid expansion of consumer electronics is significantly accelerating the demand for humidity sensors. Integration of smart sensors in smartphones, wearable devices, and home automation systems is driving their large-scale adoption.
Manufacturers prioritize compact, energy-efficient, and high-performance sensor solutions to enhance user experience. This surge in connected technologies is creating sustained opportunities for humidity sensor innovation and commercialization across global markets.
Rising adoption of HVAC systems across residential, commercial, and industrial sectors significantly propels the market. Enhanced climate control requirements, energy efficiency regulations, and increasing emphasis on indoor air quality drive the integration of advanced humidity sensing technologies.
These sensors enable precise monitoring and regulation, optimizing system performance while reducing operational costs, thereby fostering sustained market expansion.
The humidity sensor market is constrained by supply chain disruptions and raw material shortages, impacting production timelines and cost structures. Fluctuations in the availability of key components such as semiconductor materials and specialized polymers have led to increased lead times and pricing volatility.
Manufacturers are diversifying their supplier base, investing in local sourcing, and adopting agile manufacturing practices. Furthermore, strategic inventory management and advanced forecasting techniques are being implemented to enhance supply chain resilience, ensuring consistent product delivery and maintaining competitive positioning in a volatile global market.
Industrial digital transformation in this market demands advanced, real-time environmental monitoring for enhanced operational efficiency. Integration of smart sensors with IoT platforms enables predictive maintenance, process optimization, and regulatory compliance.
Growing adoption across manufacturing, automotive, and energy sectors further accelerates the market expansion, positioning humidity sensors as critical components in connected, data-driven industrial ecosystems.
|
Segmentation |
Details |
|
By Type |
Capacitive Humidity Sensors, Resistive Humidity Sensors, Thermal Conductivity Humidity Sensors |
|
By End Use |
Automotive, Pharmaceutical & Healthcare, Industrial, Building Automation & Domestic Appliances |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, Rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, U.A.E., Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South America: Brazil, Argentina, Rest of South America |
Based on region, the global market has been classified into North America, Europe, Asia Pacific, Middle East & Africa, and South America.
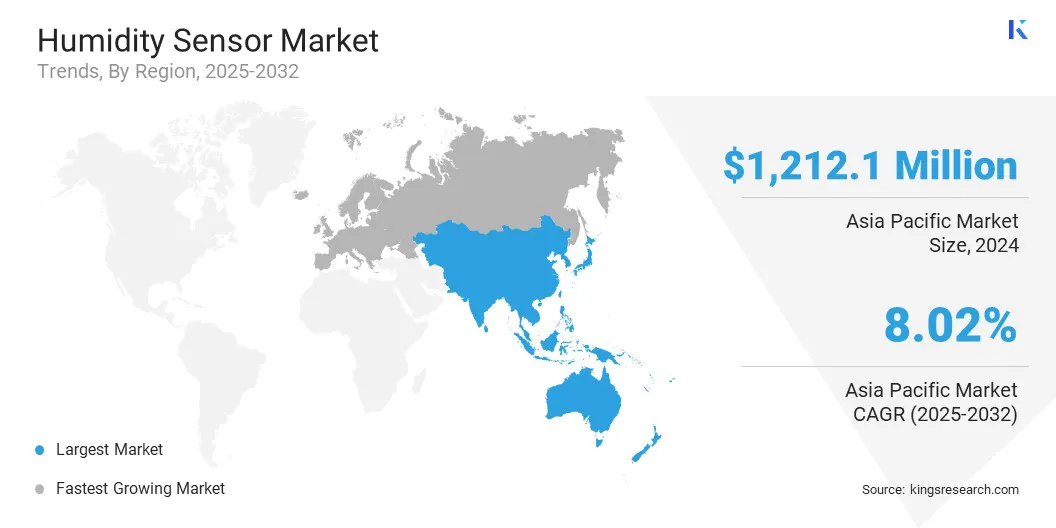
Asia Pacific accounted for 36.44% share of the humidity sensor market in 2024, with a valuation of USD 1,212.1 million. The dominance is attributed to rapid industrial growth, high production capacity in electronics, and increasing integration of sensor technologies in consumer devices & automotive systems.
Strong demand from end-user industries, coupled with government initiatives promoting smart infrastructure and environmental monitoring, accelerates adoption. Additionally, the presence of major OEMs and a robust supply chain enhances market competitiveness, reinforcing the region's leading position in the global landscape.
The humidity sensor industry in Europe is poised for significant growth at a robust CAGR of 7.82% over the forecast period. This growth is attributed to the rising demand for precision agriculture and climate-controlled farming. The increasing adoption of advanced agricultural technologies to enhance crop yield and optimize resource usage significantly contributes to sensor deployment.
Moreover, supportive government policies and funding for sustainable farming practices further accelerate market growth, positioning the region as a key contributor to the market.
The humidity sensor industry is characterized by frequent product launches and technological advancements from leading companies. These players focus on introducing high-precision, durable sensors tailored for applications in IoT and industrial automation.
The market also registers an expansion of product portfolios and strategic collaborations aimed at strengthening competitive positioning. This dynamic environment reflects efforts to address evolving demands across diverse end-use sectors.
Frequently Asked Questions

Over the years, Versha brings over 15 years of experience managing consulting assignments across industries, including Food and Beverage, Consumer Goods, ICT, Aerospace, and more. Her work has spanned diverse sectors. Her cross-domain expertise and adaptability make her a versatile and dependable professional. She is known for her keen business insight and foresight. With sharp analytical skills and a curious mindset, Versha excels at transforming complex data into actionable insights. She has a proven track record of unraveling market dynamics, identifying trends, and delivering tailored solutions to meet client needs. As a skilled leader, Versha has successfully mentored research teams and directed projects with precision, ensuring high-quality outcomes. Her collaborative approach and strategic vision enable her to turn challenges into opportunities and consistently deliver impactful results. Whether analyzing markets, engaging stakeholders, or crafting strategies, Versha draws on her deep expertise and industry knowledge to drive innovation and deliver measurable value.
With over a decade of research leadership across global markets, Ganapathy brings sharp judgment, strategic clarity, and deep industry expertise. Known for precision and an unwavering commitment to quality, he guides teams and clients with insights that consistently drive impactful business outcomes.


