
Inquire Now
Key Strategic Points
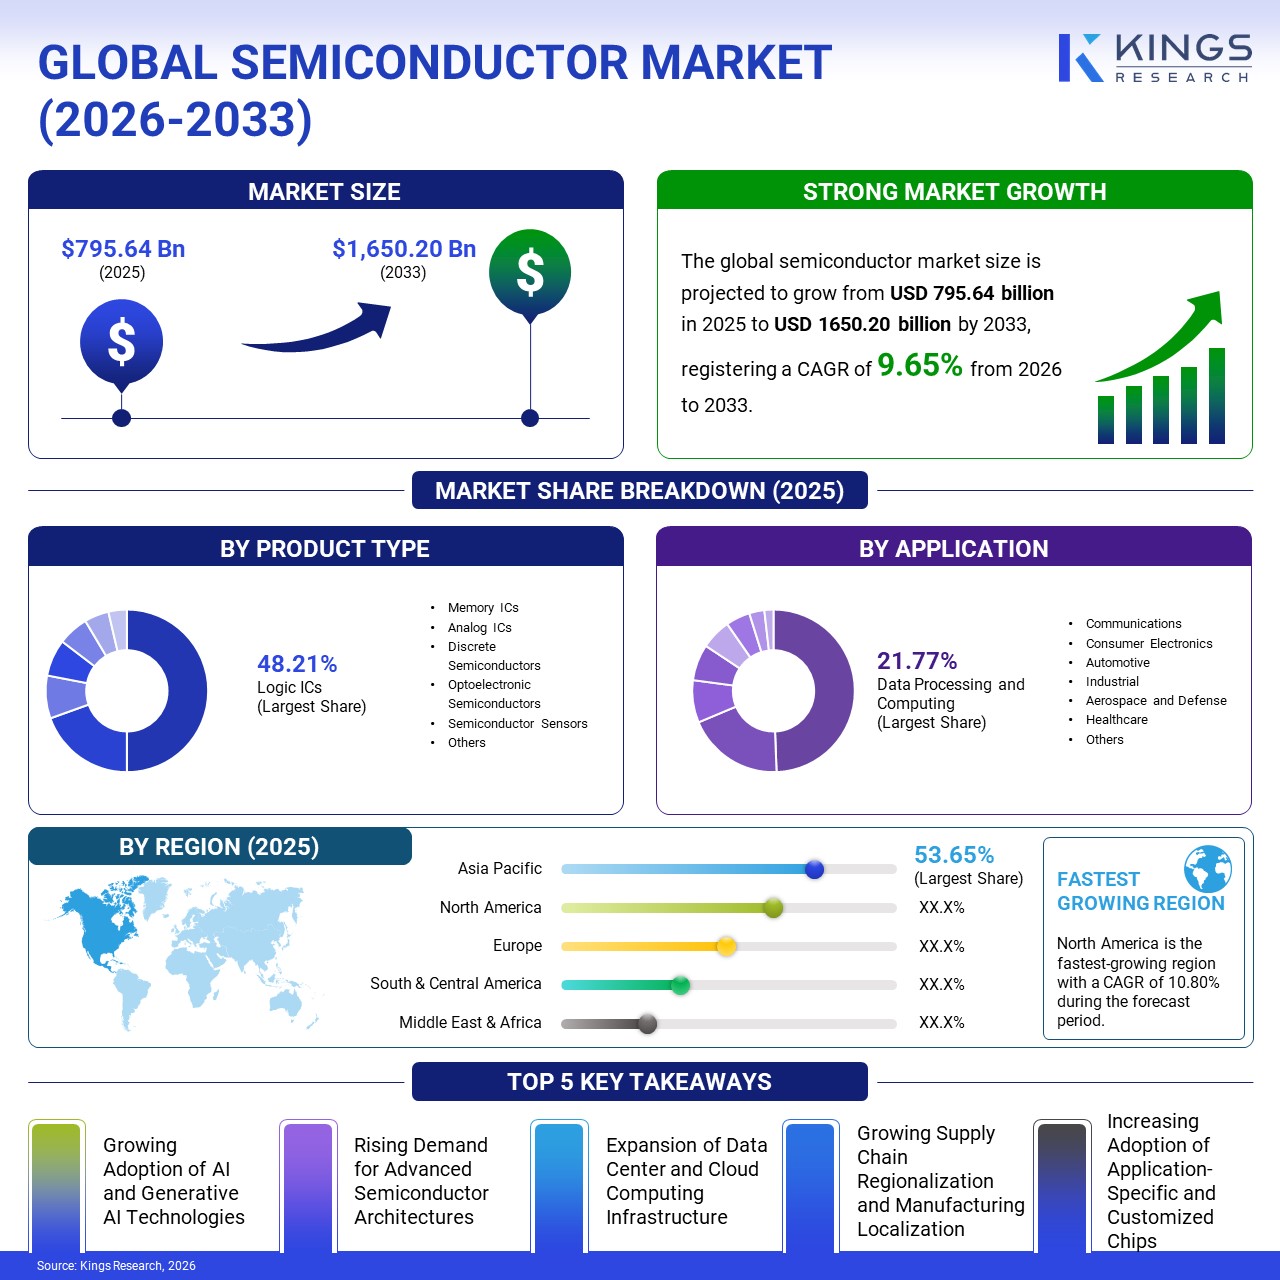
According to Kings Research analysis, the global semiconductor market was valued at USD 795.64 billion in 2025 and is estimated to grow from USD 866.15 billion to USD 1,650.20 billion in 2033, registering a CAGR of 9.65% over the forecast period (2026-2033).
The global semiconductor market is being reshaped by the rapid adoption of AI, driving demand for high-performance, customized, and application-specific chips across data centers, automotive, communications, industrial, and consumer electronics. Advanced architectures and packaging technologies are enabling greater computing performance, power efficiency, scalability, and integration.
At the same time, geopolitical tensions and supply-chain fragmentation are encouraging manufacturers to diversify production and strengthen regional semiconductor ecosystems. Competitive activity remains strong, with companies pursuing strategic partnerships, acquisitions, manufacturing expansion, and advanced packaging investments.
Asia Pacific continues to anchor global semiconductor production, while North America is emerging as a key growth region driven by AI, data centers, and domestic manufacturing initiatives.
The rapid adoption of artificial intelligence (AI) and generative AI (Gen AI) is emerging as a key growth driver for the global semiconductor industry. The increasing computational requirements of AI workloads are accelerating demand for specialized, high-performance semiconductor solutions, including neural processing units (NPUs), graphics processing units (GPUs), and high-bandwidth memory (HBM).
This trend is further strengthened by the expansion of data centers and cloud infrastructure, along with rising digital transformation across autonomous and electric vehicles, 5G and edge computing, industrial automation, and consumer electronics verticals.
Furthermore, the rising complexity of AI workloads is prompting semiconductor market players to optimize compute, memory, and networking architectures, targeted at achieving higher performance, power efficiency, and scalability across data center and edge environments.
This surge in demand from downstream industries for application-specific performance in semiconductors, through customized silicon and advanced architectures, acts as a major driver for the global semiconductor market.
Rising geopolitical tensions and technological competition are transforming global trade dynamics, thereby impacting supply chain resilience. Governments are emphasizing national security, strategic resilience, and technological competition through semiconductor restrictions and strategic tariff impositions. This is enabling semiconductor manufacturers to diversify their supply chains and shift manufacturing operations away from China toward emerging manufacturing hubs comprising India, Vietnam, Indonesia, and Mexico.
U.S. tariffs are anticipated to undermine economic growth and technological competitiveness by increasing semiconductor costs, which are crucial inputs for end-use domains comprising artificial intelligence, data centers, automobiles, telecommunications, and advanced manufacturing.
To address this challenge, governments are increasingly pursuing trade agreements and strategic partnerships to strengthen semiconductor supply chains, reduce trade uncertainties, and support domestic manufacturing capacity.
The shift towards centralized and zonal semiconductor architectures in next-generation software-defined applications is poised to create growth avenues for the semiconductor market. The limitations of traditional single-block (monolithic) chip designs to handle the extreme performance, efficiency, and data demands of modern workloads, including artificial intelligence, fuel the growth of advanced chip architectures.
Advanced packaging, including 3D stacking and system-in-package (SiP), multi-chip modules (MCM), and high-density interconnect (HDI) technologies, increases component density and integration within compact semiconductor devices.
These technologies expand the applicability of semiconductors across data centers, artificial intelligence, telecommunications, and other high-performance computing applications. This enables semiconductor players to boost growth through strategic investments in advanced packaging capabilities, enhancing chip integration and accelerating the commercialization of next-generation semiconductor architectures.
In September 2026, TSMC opened a new supplier campus in Kaohsiung’s Baipu Industrial Park to accelerate advanced semiconductor packaging development. The facility will co-locate TSMC engineers with materials and equipment suppliers, aiming to improve packaging validation efficiency by 25–50%. Rather than producing chips, the campus will focus on testing, R&D, and faster qualification of next-generation packaging materials and technologies.
The initiative is expected to strengthen Taiwan’s semiconductor supply chain and help future CoWoS capacity additions reach production more quickly. However, current AI chip supply constraints are expected to persist, with the campus’s impact becoming more significant during the 2027–2028 capacity expansion period.
AI demand is changing where value and supply constraints sit across the semiconductor value chain. Leading-edge wafer fabrication remains critical, but High-Bandwidth Memory (HBM) and advanced packaging have emerged as additional bottlenecks for AI accelerators. Chip designs are increasingly using multi-die and chiplet architectures; the ability to combine logic, memory, and other components into a single package is becoming as important as producing the individual dies.
Advanced packaging is therefore moving from a supporting manufacturing step to a strategic capacity constraint. Technologies such as TSMC’s CoWoS and SoIC are critical to integrating AI processors with HBM, while growing demand is also creating opportunities for OSAT providers to participate in higher-value packaging work. This is increasing the importance of packaging capacity alongside traditional wafer capacity when assessing semiconductor supply.
HBM is also changing the economics of the memory segment. Unlike conventional memory, which has historically been highly cyclical, HBM benefits from strong AI-driven demand and limited qualified supply. This has increased the strategic importance and pricing power of leading HBM suppliers, particularly SK hynix and Samsung in South Korea, alongside Micron in the US. As a result, South Korea has become an increasingly important center of value in the AI semiconductor supply chain, complementing the established roles of the US in design and semiconductor equipment and Taiwan in advanced fabrication.
The shift extends beyond chips themselves. Advanced packaging is creating new demand for hybrid bonding, precision assembly, substrates, and specialized materials, adding new potential constraints to the supply chain. For market participants, this means semiconductor capacity should no longer be assessed through wafer fabrication alone. HBM availability, advanced packaging capacity, and related equipment and materials are increasingly important indicators of supply, pricing power, and future value creation.
|
Segmentation |
Details |
|
|
By Product Type |
Logic ICs, Memory ICs, Analog ICs, Discrete Semiconductors, Optoelectronic Semiconductors, Semiconductor Sensors, Others |
|
|
By Application |
Data Processing and Computing, Communications, Consumer Electronics, Automotive, Industrial, Aerospace and Defense, Healthcare, Others |
|
|
By Region |
North America |
U.S., Canada, Mexico |
|
Europe |
France, the UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia-Pacific |
China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East and Africa |
Turkey, U.A.E., Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South and Central America |
Brazil, Argentina, and the rest of South and Central America |
|
Based on the product type, the global semiconductor market is segmented into logic ICs, memory ICs, analog ICs, discrete semiconductors, optoelectronic semiconductors, semiconductor sensors, and others. The logic ICs captured the largest market share of 48.21% in 2025. The high share is driven by the widespread applicability of ICs in consumer electronics, automotive systems, data centers, and AI applications. Additionally, rising demand for high-performance computing and advanced processing capabilities further fuels the demand for advanced logic ICS, thereby boosting dominance.
Based on the application, the market is segmented into data processing and computing, communications, consumer electronics, automotive, industrial, aerospace and defense, healthcare, and others. Data processing and computing is forecasted to register the fastest growth rate of 13.17% over the forecast period. This growth is primarily driven by the increasing adoption of AI workloads, cloud computing, and data center expansion, alongside rising demand for high-performance computing and advanced semiconductor solutions.
By region, the global semiconductor market has been segmented into North America, Europe, Asia Pacific, the Middle East and Africa, and South and Central America.
The Asia Pacific captures the largest share of 53.65% in 2025, registering a market valuation of USD 426.89 billion. The designation of Asia Pacific as a global hub of the semiconductor industry is supported by strong manufacturing capabilities and specialized semiconductor clusters. AI, data centers, and EV adoption act as major contributors to its high share.
The region accounts for around 75% of global semiconductor production capacity and key material supplies. Asia economies comprising Taiwan, South Korea, China, and Southeast Asia, with Hsinchu specializing in advanced chip manufacturing, South Korea in memory chips, and China in fabrication and semiconductor R&D, acting as major propellers of semiconductor production.
Emerging hubs such as Malaysia are further strengthening the regional ecosystem, with integrated circuit production and exports, which account for approximately 13% of global semiconductor testing and packaging output.
North America is projected to register the fastest semiconductor market growth, at a CAGR of 10.80%, driven largely by the United States’ position as a global hub for semiconductor innovation and technology. The rising demand from the rapidly expanding artificial intelligence, data center, consumer electronics, automotive, and telecommunications sectors is expected to significantly increase semiconductor consumption across the region.
Moreover, the presence of leading semiconductor companies, including Intel, AMD, Nvidia, Broadcom, Qualcomm, Micron Technology, and others, combined with a strong technical talent pool, further strengthens the U.S. position within the global semiconductor value chain. Government initiatives such as the CHIPS and Science Act and the Inflation Reduction Act are further poised to support and strengthen domestic semiconductor manufacturing and supply-chain resilience over the forecast interval.
Europe, the Middle East, and Africa are expected to see steady semiconductor growth, supported by increasing demand from automotive, industrial, telecommunications, and emerging applications, requiring artificial intelligence and machine learning as core technologies. Rising investments in local semiconductor manufacturing and booming consumer electronics and allied domains are anticipated to fuel market growth in the regions.
South and Central America are expected to experience comparatively moderate semiconductor market growth, driven by rising adoption of digital technologies across the industrial landscape of emerging economies, including Brazil, Chile, and Argentina. Increasing investments in electronics manufacturing and improving semiconductor supply-chain capabilities are poised to fuel semiconductor demand across the industrial ecosystem of the region.
The global semiconductor market is fragmented, with competition distributed across leading global players and regional players that maintain strong positions in their respective markets. Companies are strengthening strategic technical partnerships and mergers and acquisitions to expand reach across untapped markets.
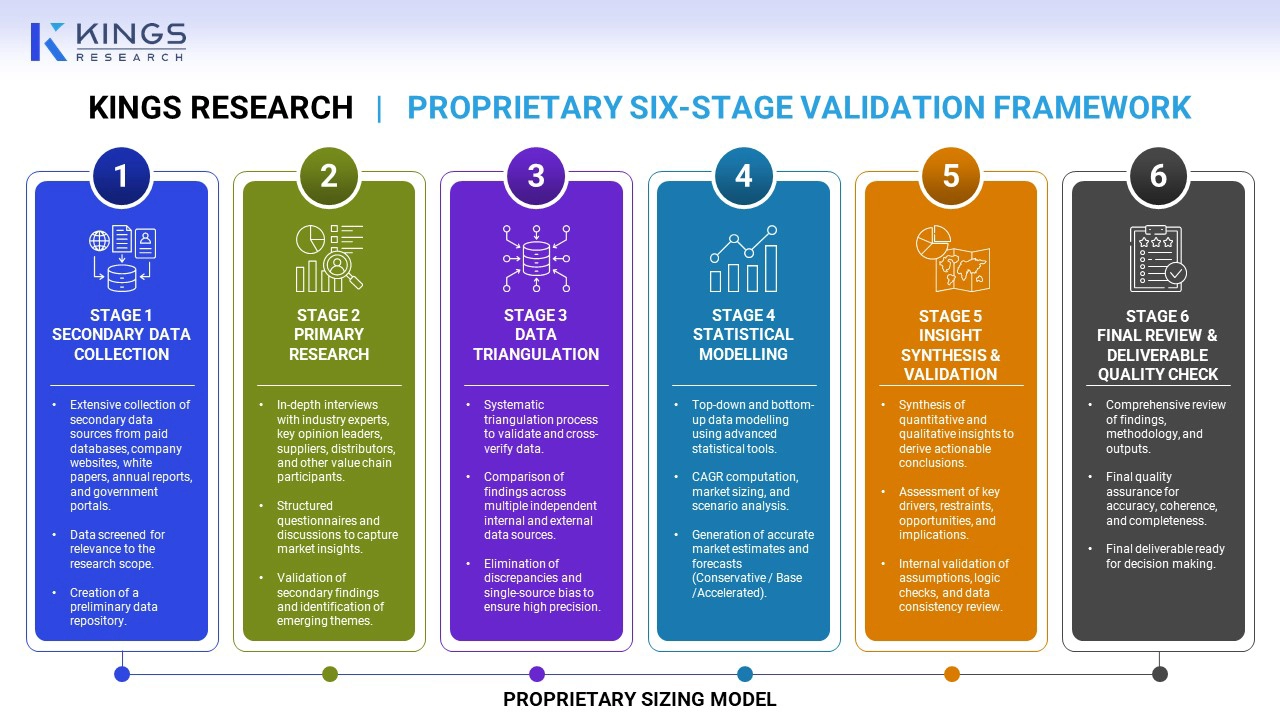
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Ashim Lakhera is a market intelligence professional specializing in the Agriculture and Food & Beverage industry. His work focuses on emerging markets, competitive dynamics, industry trends, and the factors driving market growth and transformation. He has experience in market sizing, forecasting, strategic analysis, and industry research across food, FMCG, and life sciences. His research interests span the broader food and agriculture value chain, with a particular focus on how innovation, changing consumer behavior, sustainability priorities, and evolving production systems are influencing markets. He examines these developments to understand their impact on demand, competition, business models, and growth opportunities across the agri-food ecosystem. His work combines quantitative market analysis with an understanding of the broader industry forces shaping food and agriculture markets. He is particularly interested in the structural changes taking place across global food systems and how businesses are adapting to evolving consumer expectations, technological developments, and sustainability requirements.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


