
Inquire Now
Key Strategic Points
According to Kings Research, the global digital diabetes management market size was valued at USD 24.80 billion in 2025 and is projected to reach USD 63.50 billion by 2033, growing at a CAGR of 12.47% from 2026 to 2033. Digital diabetes management refers to the use of technology, including mobile apps, wearable devices, telemedicine platforms, and data analytics, to monitor, track, and manage diabetes related parameters such as glucose levels, medication adherence, diet, and exercise.
The report covers products offered by companies such as MiniMed, Inc., Dexcom, Inc., Abbott Laboratories, Roche Diabetes Care, Inc., Insulet Corporation, Tandem Diabetes Care, Inc., Ascensia Diabetes Care Holdings AG, Teladoc Health, Inc., Senseonics Holdings, Inc., WellDoc, Inc., and others.
Wearable devices such as continuous glucose monitors (CGMs), connected insulin pumps, smart glucose meters, and digital diabetes applications are becoming increasingly sophisticated, enabling real-time monitoring and more automated disease management. The integration of these technologies with AI-powered analytics and machine learning is accelerating the transition toward predictive and personalized diabetes care. AI algorithms can analyze large volumes of glucose, behavioral, and physiological data to identify patterns, predict blood glucose fluctuations, and support treatment decisions, while connected insulin delivery systems can increasingly automate therapy based on individual patient needs. The convergence of wearables, AI, connected devices, and digital platforms is therefore expanding the capabilities of diabetes management beyond basic monitoring and tracking.
Digital diabetes management is increasingly evolving into an interconnected healthcare ecosystem that combines wearable devices, mobile applications, telemedicine platforms, remote patient monitoring, electronic health records, and clinical decision-support systems. Integration across these technologies enables healthcare providers to remotely access patient data, monitor changes in glucose levels, and intervene more proactively when risks are identified. However, broader adoption is also influenced by reimbursement frameworks, data privacy and cybersecurity requirements, regulatory approval processes, and interoperability with existing healthcare infrastructure. As healthcare systems increasingly emphasize value-based care and measurable patient outcomes, solutions that demonstrate clinical effectiveness, integrate seamlessly with provider workflows, and improve patient engagement are expected to achieve greater adoption.
In our study, we explore the key demand signals that impact the digital diabetes management market, including device adoption trends, patient engagement levels, changing reimbursement policies, and provider adoption rates. This offers companies a clear picture of the current market position and forecasts where the demand will be concentrated in the coming years. Our results ultimately underscore the importance of increased diabetes prevalence, ongoing surveillance needs, scaling of remote care models, and broader movement toward personalized, preventive health care in facilitating sustained long-term growth.
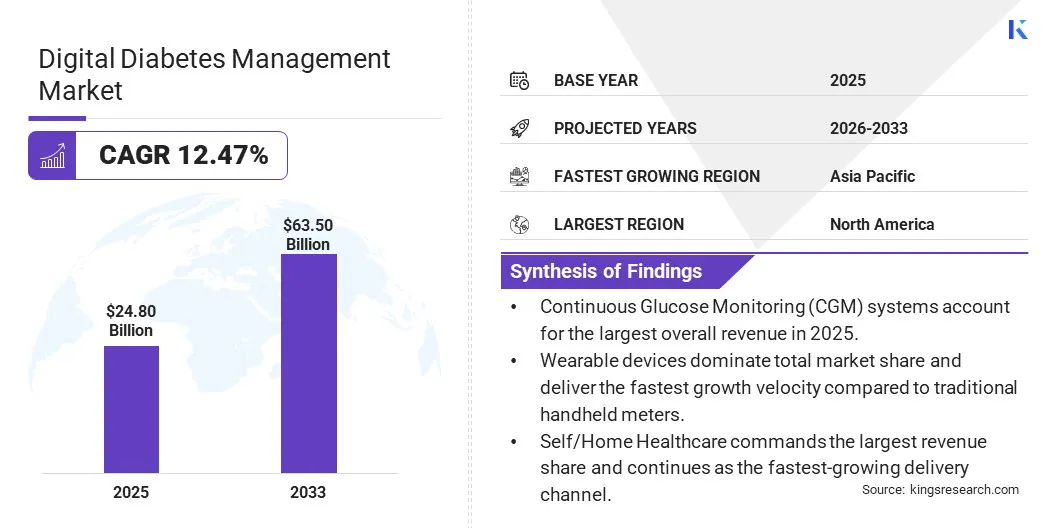
The rising prevalence of diabetes worldwide is a significant factor driving demand for digital diabetes management solutions. According to the World Health Organization, diabetes rates continue to climb due to sedentary lifestyles, unhealthy diets, obesity, and aging populations, placing a growing burden on healthcare systems and increasing the focus on preventive and proactive care. Digital solutions offer a scalable, cost-effective way to monitor and manage diabetes, giving patients self-care tools while enabling providers to deliver timely, personalized interventions.
The integration of AI-powered analytics with connected devices is expanding what digital diabetes management platforms can offer. Randomized studies have shown that smartphone-integrated glucose tools can improve HbA1c control by 0.5 to 0.8 percentage points compared with standard care alone, giving providers and payers measurable evidence of clinical benefit rather than a general efficiency claim.
These platforms are increasingly able to flag early warning signs of glycemic instability and recommend dosage adjustments, supporting more proactive, personalized treatment rather than the reactive, appointment-based model that has traditionally defined diabetes care.
Regulatory and reimbursement changes are accelerating adoption. New remote patient monitoring billing codes now allow physicians to be reimbursed for reviewing continuous glucose monitor data remotely, creating a predictable revenue stream that offsets device and platform costs for healthcare providers.
The U.S. Food and Drug Administration's streamlined pathway for over-the-counter continuous glucose monitor approvals has also removed a major access barrier, allowing consumers without a prescription to purchase and use these devices directly.
Sustained telehealth utilization, combined with rising smartphone penetration and digital literacy, continues to support demand for platforms that combine glucose monitoring with remote consultations and care coordination. Improved interoperability between digital diabetes platforms and electronic health records is making this integration more practical for healthcare systems to adopt at scale.
Data privacy and security concerns remain a meaningful restraint on market growth. The sensitive nature of health data, including glucose levels, medication history, and lifestyle habits, raises concerns about unauthorized access, data breaches, and misuse, requiring compliance with data protection regulations such as GDPR in the European Union and HIPAA in the United States.
To address these concerns, companies are implementing encryption protocols, secure data storage, and regular security audits, alongside transparent privacy policies that help build patient and provider trust in digital health technologies.
Many healthcare providers still lack the IT infrastructure needed to act on continuous, streaming glucose data even where data exchange standards exist. This gap between data availability and a provider's practical ability to use that data in clinical workflows limits how much value some healthcare systems can realistically extract from digital diabetes management platforms in the near term.
The rise of personalized and preventive care is reshaping this market. Personalized approaches use data analytics, AI algorithms, and in some cases genetic insight to tailor treatment plans to individual patients, improving treatment efficacy and patient engagement compared with a one-size-fits-all approach.
Kings Research's Technology Intelligence practice tracks emerging innovations before they reach mainstream adoption, including closed-loop insulin delivery systems and next-generation predictive glucose algorithms, giving clients early visibility into which technologies are likely to reshape competitive dynamics in coming product cycles.
|
Segmentation |
Details |
|
Segmentation By Product & Service |
Devices (CGM Systems, Smart Insulin Pumps & Patches, Smart Glucose Meters, and Smart Insulin Pens), Applications (Diabetes & Tracking Apps, Weight & Diet Apps), Software & Platforms and Services |
|
By Device Type |
Wearable, Handheld |
|
By End User |
Self and Home Healthcare, Hospitals and Clinics, Others |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, Rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South & Central America: Brazil, Argentina, Rest of South and Central America |
The global digital diabetes management market is segmented based on product & service, device type, end user, and geography.
How is continuous glucose monitoring driving its dominance in the market?
Based on product and service, the market is segmented into continuous glucose monitoring systems, smart glucometers, smart insulin patch pumps, smart insulin pens, and apps and services. Continuous glucose monitoring systems are the largest sub-segment, reflecting its essential role in real-time glucose tracking and treatment decision-making.
Smart insulin pumps and patches are the fastest-growing sub-segment, supported by continued advances in automated, closed loop insulin delivery that reduce the day-to-day burden of manual dosing on patients.
How is the self and home healthcare segment driving its dominance across end users?
Based on end user, the market is classified into self and home healthcare, hospitals and clinics, and others. Self and home healthcare is the largest end-user segment, reflecting the broader shift of diabetes management out of clinical settings and into patients' daily routines, supported by wearable devices that make continuous, at-home monitoring practical.
Hospitals and clinics remain a significant channel, particularly for initial diagnosis and complex case management, while established partnerships between hospitals and digital health solution providers continue to support institutional adoption of these tools alongside their growing use at home.
How is the wearable devices segment driving its dominance across device types?
Based on device type, the market is classified into wearable and handheld devices. Wearable devices are both the largest and fastest-growing device type, reflecting strong patient preference for continuous, unobtrusive monitoring over handheld devices that require active, periodic use.
This dual leadership position makes wearable form factors the clearest area of sustained investment for device manufacturers, as products in this category are winning on both current adoption and forward growth momentum at the same time.
By region, the global digital diabetes management market is categorized into North America, Europe, Asia-Pacific, MEA, and South & Central America.
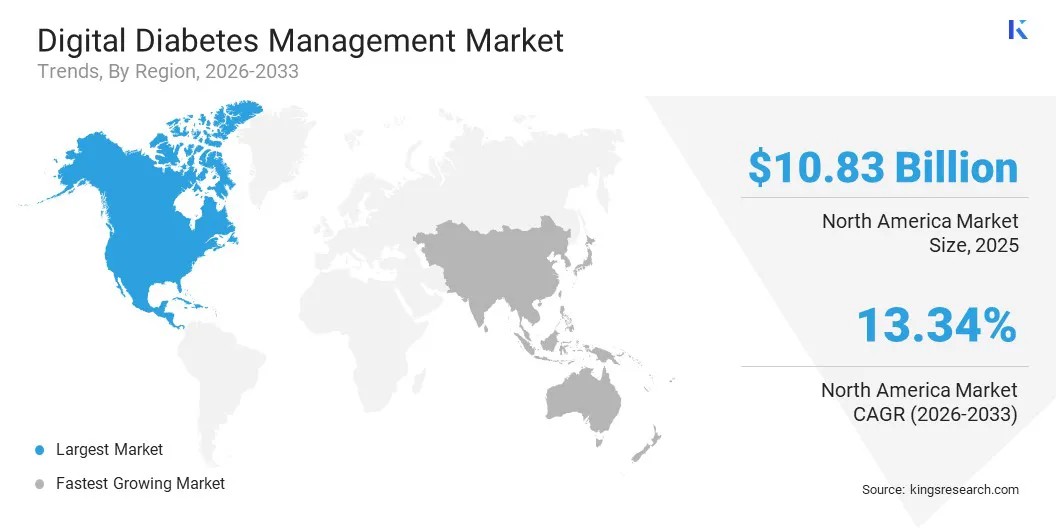
North America held the largest regional share in 2025. This leadership is supported by a high prevalence of diabetes and obesity, advanced healthcare infrastructure, and a favorable regulatory and reimbursement environment that continues to encourage investment in telemedicine, remote patient monitoring, and AI-driven healthcare solutions.
Europe remains a significant market, supported by well-established healthcare infrastructure and widespread adoption of advanced technologies, alongside supportive regulatory frameworks and reimbursement policies for digital health services.
Asia-Pacific is anticipated to register the fastest regional CAGR over the forecast period, supported by rising diabetes prevalence, expanding smartphone penetration, and government-led digital health initiatives across the region's major economies.
The global digital diabetes management market report will provide valuable insights with an emphasis on the fragmented nature of the industry. Prominent players are focusing on several key business strategies such as partnerships, mergers and acquisitions, product innovations, and joint ventures to expand their product portfolio and increase their market shares across different regions. Companies are undertaking effective strategic initiatives, including investments in R&D activities, the establishment of new manufacturing facilities, and supply chain optimization, to gain a competitive edge in the market.
How We Gather This Information
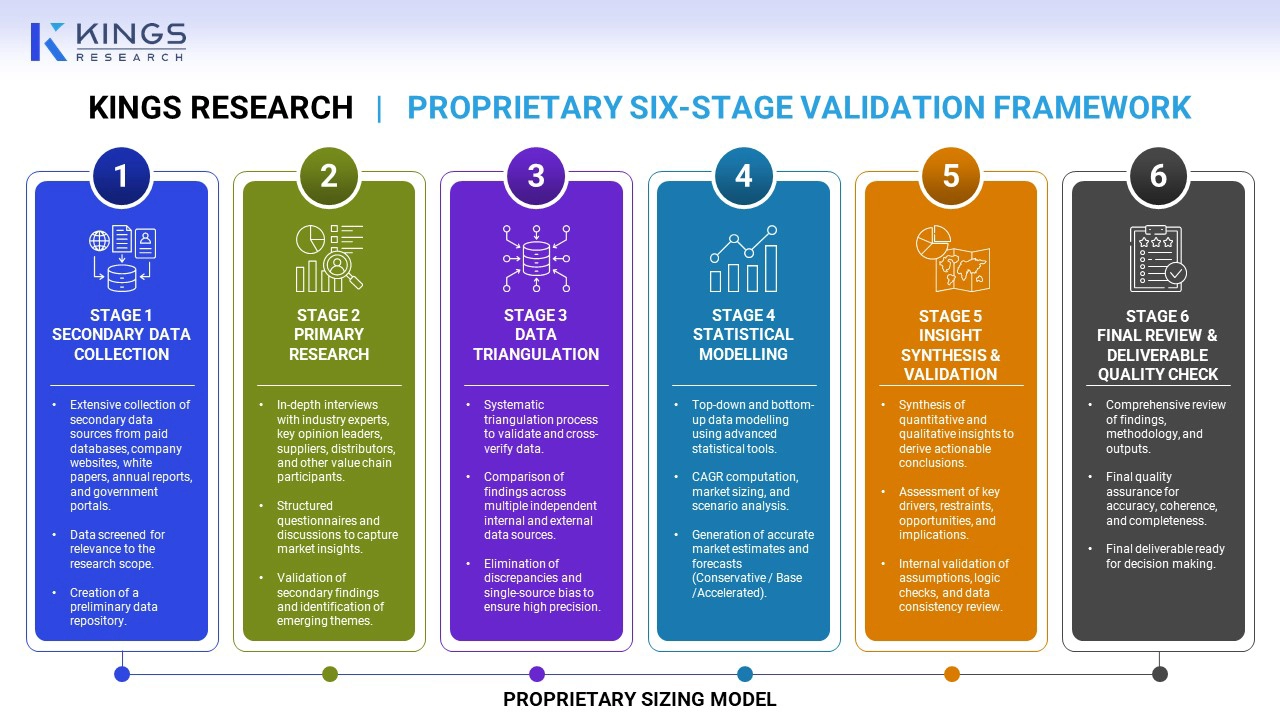
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Omkar is an accomplished research analyst with experience across a wide range of industries, including but not limited to pharmaceuticals, biotechnology, healthcare, chemicals & materials, energy, and consumer goods. His cross-domain expertise allows him to analyze complex market dynamics, uncover actionable insights, and provide high-value research that supports strategic decision-making. Skilled in both qualitative and quantitative analyses, Omkar synthesizes large datasets to create insightful, stakeholder-focused reports. His broad industry knowledge enables him to identify synergies across sectors, adding value to his research. Outside of work, Omkar is a passionate movie enthusiast. His love for cinema fuels his creativity and enhances his ability to think critically-skills that complement his research capabilities. Omkar’s data validation skills and cross-industry expertise make him a partner. He translates complex findings into strategic narratives. His commitment to continuous learning keeps him ahead of evolving markets, while his collaborative nature strengthens team synergy, driving stakeholder confidence and impactful outcomes.
With many years of consulting experience across global pharma, biotech, and MedTech markets, Minaz brings deep domain expertise, strategic clarity, and analytical rigor to every engagement. She has led 130+ consulting assignments spanning market entry, competitive landscaping, and portfolio prioritization, helping clients navigate complex, high-stakes decisions with confidence. Known for her ability to synthesize primary and secondary research into executive-ready recommendations, Minaz has built forecasting models and market sizing frameworks that have informed multi-million dollar investment decisions in oncology, diagnostics, and peptide therapeutics. Beyond her analytical strength, Minaz is a trusted client partner, translating complex datasets into clear, actionable insights for senior stakeholders. She currently leads a team of research analysts, driving business expansion, and shaping client engagement strategy.


