
Inquire Now
Key Strategic Points
Non-metal electrical conduits are tubular systems used to protect and route electrical wiring in buildings and infrastructure. They are typically made from materials such as polyvinyl chloride, polypropylene, and fiber-reinforced composites, offering corrosion resistance and ease of installation compared to traditional metal conduits.
These conduits find extensive use in residential, commercial, and industrial construction projects, ensuring safe and organized electrical distribution. They are applied in wiring protection, cable management, and structural installations where durability, flexibility, and long-term reliability are essential.
The global non-metal electrical conduit market size was valued at USD 3,952.6 million in 2024 and is projected to grow from USD 4,209.2 million in 2025 to USD 6,892.8 million by 2032, exhibiting a CAGR of 7.30% during the forecast period.
This growth is attributed to rising construction activities and increasing demand for safe and efficient electrical distribution systems. Widespread adoption across residential, commercial, and industrial sectors is further supported by advantages such as corrosion resistance, lightweight design, and ease of installation.
Major companies operating in the non-metal electrical conduit market are Atkore, IPEX Electrical Inc., CTUBE Inc., Robroy Industries, Champion Fiberglass, Inc., Anamet Electrical, Inc., National Pipe and Plastics, Inc, JM EAGLE, INC., Westlake Pipe & Fittings, Bahra Electric, Electri-Flex Company, ABB, PIPELIFE INTERNATIONAL GmbH, Schneider Electric, and Legrand.
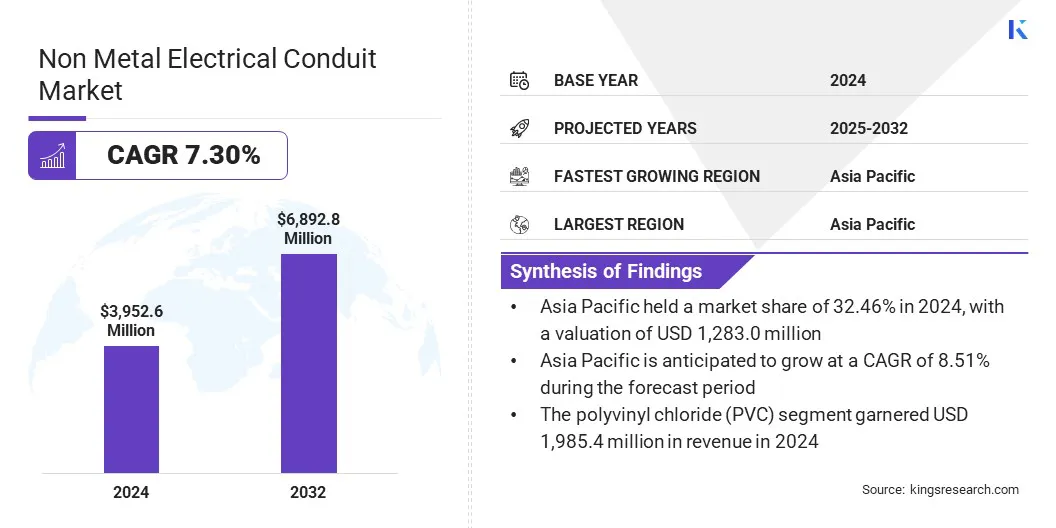
Increasing focus on regulatory compliance, standardized wiring safety, and large-scale infrastructure projects is promoting wider deployment of non-metal electrical conduits worldwide. Additionally, ongoing material innovations, enhanced manufacturing processes, and supportive government policies are boosting market expansion.
The growth of the non-metal electrical conduit market is primarily boosted by rising construction activities and expanding infrastructure projects across residential, commercial, and industrial sectors. Increasing investments in building developments, smart cities, and energy facilities are creating a strong demand for reliable and durable electrical distribution systems.
According to the Government of India’s Open Government Data Platform, the Annual Building Construction Cost Index from 1981 to 2022 shows a consistent increase in construction costs, reflecting steady growth in construction activities and demand for building materials.
In response, construction and industrial players are increasingly adopting non-metal conduits due to their corrosion resistance, lightweight design, and ease of installation. Ongoing urbanization, large-scale projects, and regulatory compliance requirements are further promoting wider deployment and technological improvements, supporting sustained market growth.
The limited load-bearing capacity poses a major challenge to the growth of the nonmetal electrical conduit market. Compared to traditional metal conduits, these products offer lower mechanical strength, restricting their use in heavy-duty, high-impact, or industrial applications and often necessitating additional protective or reinforcement. This limitation increases project complexity, installation time, and overall costs, particularly in large-scale infrastructure projects.
Furthermore, construction companies and facility managers face challenges in ensuring reliability and compliance with structural requirements, as the integration of non-metal conduits in demanding environments requires careful material selection, engineering expertise, and strict adherence to safety standards.
Ongoing research in advanced polymer composites, fiber reinforcements, and hybrid materials aims to enhance mechanical performance, supporting wider adoption and addressing load-bearing limitations.
The non-metal electrical conduit market is witnessing a notable trend toward advancements in material technology, supported by increasing demand for durable, lightweight, and corrosion-resistant solutions across residential, commercial, and industrial construction projects.
High-performance polymers, fiber-reinforced composites, and hybrid materials are being developed to enhance mechanical strength, load-bearing capacity, and resistance to environmental factors, while manufacturing processes are optimized for consistency and long-term reliability. Construction companies are adopting these innovations to achieve efficient, low-maintenance, and cost-effective alternatives to traditional metal conduits.
Leading manufacturers and research institutions are investing in advanced materials, improved extrusion techniques, and innovative composite designs to scale production and performance. Continuous improvements in conduit technology are expected to broaden applications, support safer electrical installations, and boost significant market growth over the forecast period.
|
Segmentation |
Details |
|
By Classification |
Polyvinyl Chloride (PVC), Reinforced Thermosetting Resin (RTRC/FRE), Rigid Non-Metallic (RNC), and Electrical Non-Metallic Tubing (ENT) |
|
By End Use |
Residential, Commercial, Industrial, and Utility |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, Rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, U.A.E., Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South America: Brazil, Argentina, Rest of South America |
Based on region, the global non-metal electrical conduit market has been classified into North America, Europe, Asia Pacific, Middle East & Africa, and South America.
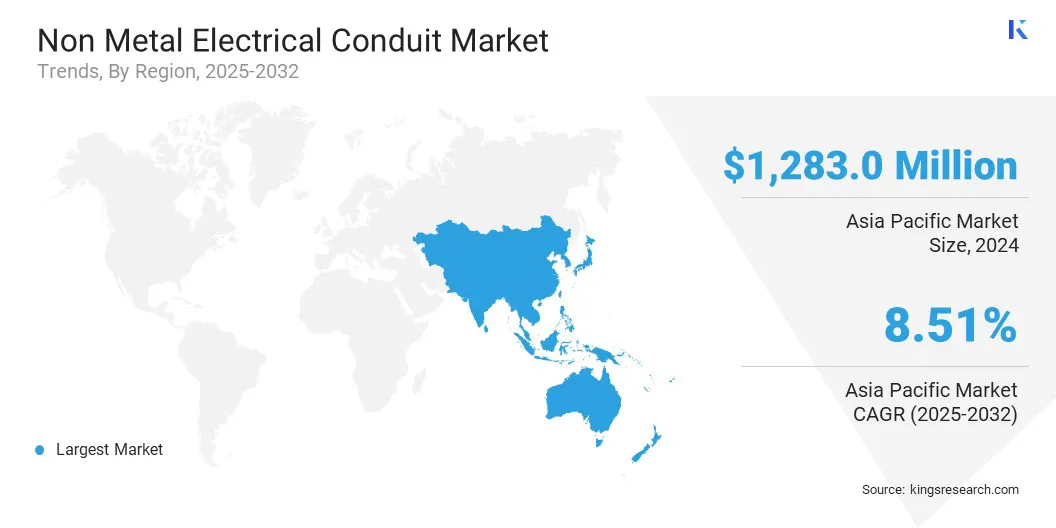
Asia Pacific non-metal electrical conduit market share stood at 32.46% in 2024, valued at USD 1,283.0 million. Rapid urbanization, expanding infrastructure projects, and increasing industrialization are reinforcing this dominance. Additionally, substantial investments in residential, commercial, and smart city developments are accelerating adoption across construction and industrial sectors.
Strategic initiatives by local and international manufacturers, along with supportive building regulations, present growth prospects. Continuous advancements in high-performance polymers, fiber-reinforced materials, and manufacturing technologies are further promoting the deployment of non-metal electrical conduits across the region.
The Europe non-metal electrical conduit industry is set to grow at a CAGR of 7.04% over the forecast period. This growth is fueled by increasing investments in modern infrastructure, smart buildings, and industrial upgrades across the region. Government regulations, building codes, and initiatives promoting electrical safety are boosting the adoption of non-metal conduit solutions in the region.
Increasing construction activities across residential, commercial, and industrial sectors are creating strong opportunities for wider deployment. Moreover, advancements in high-performance polymers, fiber-reinforced composites, and manufacturing technologies are fostering adoption, positioning Europe as a key market for non-metal electrical conduits.
Companies operating in the non-metal electrical conduit industry are maintaining competitiveness through investments in advanced polymer and composite materials, enhanced manufacturing processes, and innovative conduit designs. They are focusing on expanding product portfolios and improving operational efficiency to meet growing demand across residential, commercial, and industrial construction projects.
Leading players are offering solutions such as polyvinyl chloride (PVC), reinforced thermosetting resin (RTRC), and electrical non-metallic tubing (ENT), supported by strategic collaborations, joint ventures, and regional expansion efforts.
Rising focus on partnerships with contractors, regulators, and technology providers is further accelerating adoption and ensuring compliance with building codes. Additionally, companies are enhancing product performance, durability, and fire-retardant properties while leveraging automation, digital monitoring, and integrated service offerings to maintain a competitive edge.
Frequently Asked Questions

Over the years, Versha brings over 15 years of experience managing consulting assignments across industries, including Food and Beverage, Consumer Goods, ICT, Aerospace, and more. Her work has spanned diverse sectors. Her cross-domain expertise and adaptability make her a versatile and dependable professional. She is known for her keen business insight and foresight. With sharp analytical skills and a curious mindset, Versha excels at transforming complex data into actionable insights. She has a proven track record of unraveling market dynamics, identifying trends, and delivering tailored solutions to meet client needs. As a skilled leader, Versha has successfully mentored research teams and directed projects with precision, ensuring high-quality outcomes. Her collaborative approach and strategic vision enable her to turn challenges into opportunities and consistently deliver impactful results. Whether analyzing markets, engaging stakeholders, or crafting strategies, Versha draws on her deep expertise and industry knowledge to drive innovation and deliver measurable value.
With over a decade of research leadership across global markets, Ganapathy brings sharp judgment, strategic clarity, and deep industry expertise. Known for precision and an unwavering commitment to quality, he guides teams and clients with insights that consistently drive impactful business outcomes.


