
Inquire Now
Key Strategic Points
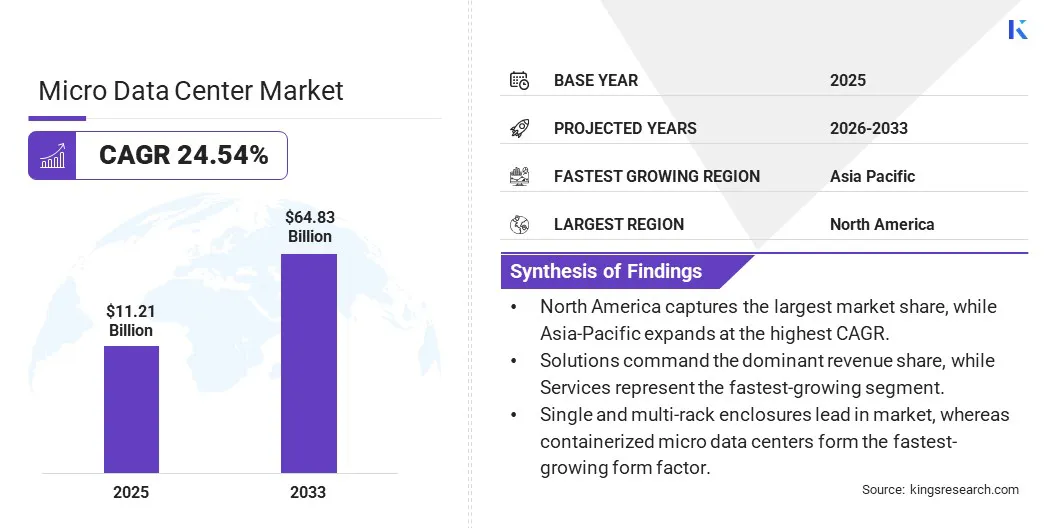
According to Kings Research, the global micro data center market size was valued at USD 11.21 billion in 2025 and is projected to reach USD 64.83 billion by 2033, growing at a CAGR of 24.54% during the forecast period 2026-2033. The market is experiencing robust growth, driven by several factors, including the increasing demand for edge computing solutions, the proliferation of IoT devices, and the need for scalable and flexible IT infrastructure.
In the scope of work, the report includes products offered by companies such as Rittal GmbH & Co. KG, Panduit Corp., Vertiv Group Corp., Schneider Electric, Eaton, American Portwell Technology, Inc., Hewlett Packard Enterprise Development LP, Hitachi Energy Ltd., Delta Power Solutions, ALTRON, and others.
The micro data center market is characterized by strong competition among established infrastructure providers offering integrated, modular, and scalable solutions. Vendors are increasingly enhancing their portfolios with advanced power management, cooling, security, monitoring, and remote management capabilities. Companies such as Vertiv and Schneider Electric are developing solutions for telecommunications, manufacturing, retail, healthcare, and industrial applications, supporting rapid deployment of localized computing infrastructure and addressing the growing requirements of distributed edge computing environments.
The continued deployment of 5G networks is increasing the need for distributed computing infrastructure that can process data closer to users and connected devices. 5G's higher bandwidth and lower latency support data-intensive applications such as autonomous systems, industrial automation, IoT, and smart infrastructure. Edge micro data centers address these requirements by bringing computing, storage, power, cooling, and management capabilities closer to the point of data generation, thereby reducing latency and improving real-time responsiveness.
The growing volume of data generated by IoT devices and distributed industrial systems is encouraging organizations to shift processing and storage closer to the network edge. Micro data centers provide compact, integrated infrastructure that combines power, cooling, security, and IT management, enabling reliable computing in factories, retail facilities, telecommunications sites, and other locations where conventional data centers are impractical. This is supporting the expansion of edge computing, Industry 4.0, and distributed IoT deployments.
Increasing adoption of AI and high-performance computing is raising requirements for high-density computing and advanced thermal management. In February 2025, Schneider Electric completed the acquisition of a controlling interest in Motivair, strengthening its liquid-cooling capabilities for AI and HPC workloads. Such investments reflect the industry's shift toward advanced cooling technologies capable of supporting increasingly power-dense computing environments.
Enterprises are increasingly deploying computing resources across remote offices, manufacturing facilities, retail locations, and other space-constrained environments, creating demand for compact and rapidly deployable infrastructure. Micro data centers integrate essential IT infrastructure within standardized enclosures, enabling faster installation, easier scalability, and simplified remote management compared with conventional data center construction. Their ability to bring computing capacity closer to distributed workloads is therefore supporting adoption across industrial, commercial, telecommunications, and other edge applications.
Integration with legacy IT environments can constrain the adoption of micro data centers, particularly when organizations need to connect new edge infrastructure with existing servers, networking equipment, applications, and IT/OT systems. Compatibility requirements, integration work, and the need for specialized expertise can increase deployment complexity and place additional demands on internal IT teams. Schneider Electric highlights IT/OT integration as an important consideration for industrial micro data center deployments, while its pre-integrated solutions are designed to simplify compatibility and deployment.
High upfront investment and ongoing operating expenses can also limit adoption, particularly among small and medium-sized enterprises. Although micro data centers can reduce construction and deployment costs under certain conditions, organizations still need to account for servers, UPS systems, cooling, power infrastructure, monitoring, maintenance, and energy consumption. Distributed deployments can further increase management and maintenance requirements because multiple sites may need to be monitored and serviced.
The increasing integration of AI and liquid-cooling technologies into micro data center designs is emerging as a prominent trend shaping the market. As AI inferencing and high-performance computing workloads increasingly move closer to the network edge, vendors are developing compact infrastructure capable of supporting higher computing densities and associated thermal loads. Advanced liquid-cooling solutions are being incorporated to improve heat dissipation and maintain system performance within space-constrained environments, while modular architectures enable flexible deployment across distributed locations. This trend is expected to continue influencing product development as AI workloads increasingly extend beyond centralized data centers into edge environments.
|
Segmentation |
Details |
|
By Component |
Solution (Hardware and DCIM Software) and Services (Integration & Installation, Consulting, Maintenance & Support) |
|
By Type |
Rack, Cabinet and Container |
|
By Vertical |
IT and Telecommunications, BFSI, Healthcare, Retail and Others |
|
By End Use |
BFSI, Retail & E-Commerce, Healthcare, IT & Telecommunications, Government and Others |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, Rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South & Central America: Brazil, Argentina, Rest of South & Central America |
The global market is segmented based on component, type, vertical, end use, and geography.
Why is the services segment growing faster than solution despite solution's larger base?
Based on component, the market is categorized into solution and services. According to Kings Research, the solution segment led the market in 2025, driven by the diverse range of hardware enclosures and DCIM software offered by key players. The services segment, comprising integration and installation, consulting, and maintenance and support, is expected to register the fastest growth over the forecast period. This divergence reflects a maturing buyer base: as more enterprises without in-house edge IT expertise deploy micro data centers into remote offices, retail locations, and industrial sites, demand for integration, consulting, and ongoing support is scaling faster than hardware and software sales alone.
Why does rack lead while container grows fastest?
Based on type, the market is classified into rack, cabinet, and container. The rack segment held the largest share in 2025, reflecting its established role as a compact, space-efficient way to deploy IT infrastructure in offices, retail stores, and edge locations. The container segment is expected to grow at the fastest pace through 2033, as organizations increasingly favor fully self-contained, weatherized units for large-scale edge and industrial deployments where rack or cabinet form factors cannot accommodate the required power and cooling capacity.
Why do IT and telecommunications lead both current share and forecast growth?
Based on vertical, the market is segmented into IT and telecommunications, BFSI, healthcare, retail, and others. IT and telecommunications led the market in 2025 and are also expected to remain the fastest-growing vertical through 2033, an unusually concentrated pattern that reflects the sector's dual role as both the earliest adopter of edge computing infrastructure and the primary beneficiary of 5G network rollout. IT companies, telecommunications providers, and service providers deploy micro data centers to support edge computing, IoT deployments, content delivery, and mobile edge computing, applications that demand high-performance, scalable, and reliable infrastructure positioned close to the point of use. BFSI, healthcare, and retail represent a more diversified but currently smaller opportunity set, with adoption driven by branch-level deployment, patient-data processing, and in-store analytics, respectively.
Based on region, the global market is classified into North America, Europe, Asia-Pacific, MEA, and South & Central America.
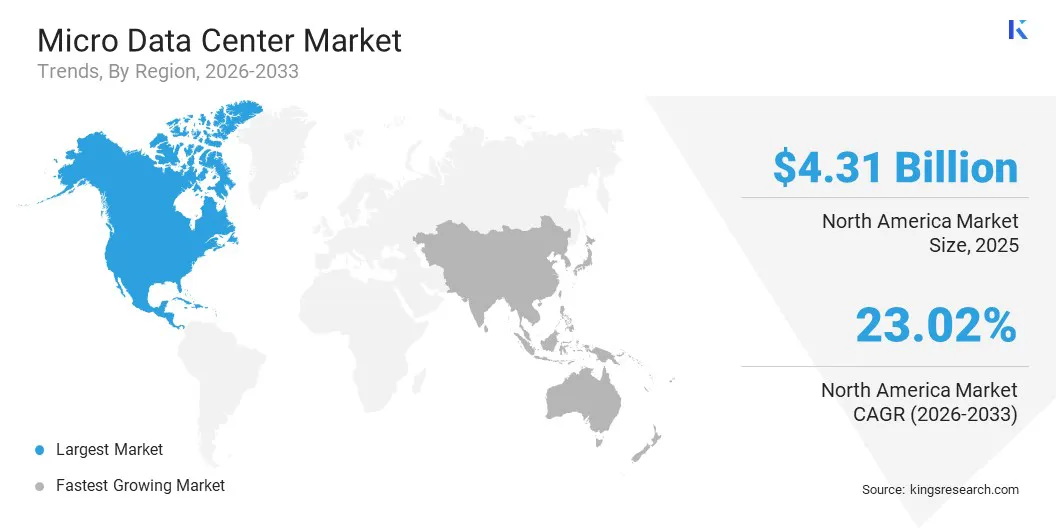
North America held the largest regional market size of USD 4.31 billion in 2025, representing a 38.46% share of the global market, and is projected to grow at a CAGR of 23.02% through 2033. The region's dominance reflects the significant adoption of micro data center solutions across telecommunications, healthcare, finance, and IT services, supported by a strong presence of key market players, advanced technological infrastructure, and continued investment in edge computing, IoT deployments, and mobile edge computing. The region is characterized by a highly competitive landscape, with key players focusing on research and development initiatives to stay ahead in this rapidly evolving market.
Asia-Pacific is projected to be the fastest-growing region over the forecast period, underpinned by the region's rapid 5G rollout pace, expanding hyperscale and edge infrastructure investment, and manufacturing-hub concentration across China, Japan, India, and South Korea. These markets are simultaneously major consumers and major producers of edge infrastructure components, a combination that is expected to accelerate regional adoption faster than in more mature markets.
The global micro data center market is characterized by a fragmented competitive landscape, with a mix of established infrastructure vendors and specialized cooling and power management providers. Key players are pursuing partnerships, mergers and acquisitions, product innovation, and joint ventures to expand their portfolios and strengthen their market presence across regions.
Rittal GmbH & Co. KG specializes in modular enclosure systems for industrial edge deployments, while Panduit Corp. focuses on structured cabling and physical infrastructure for micro data center integration.
How We Gather This Information
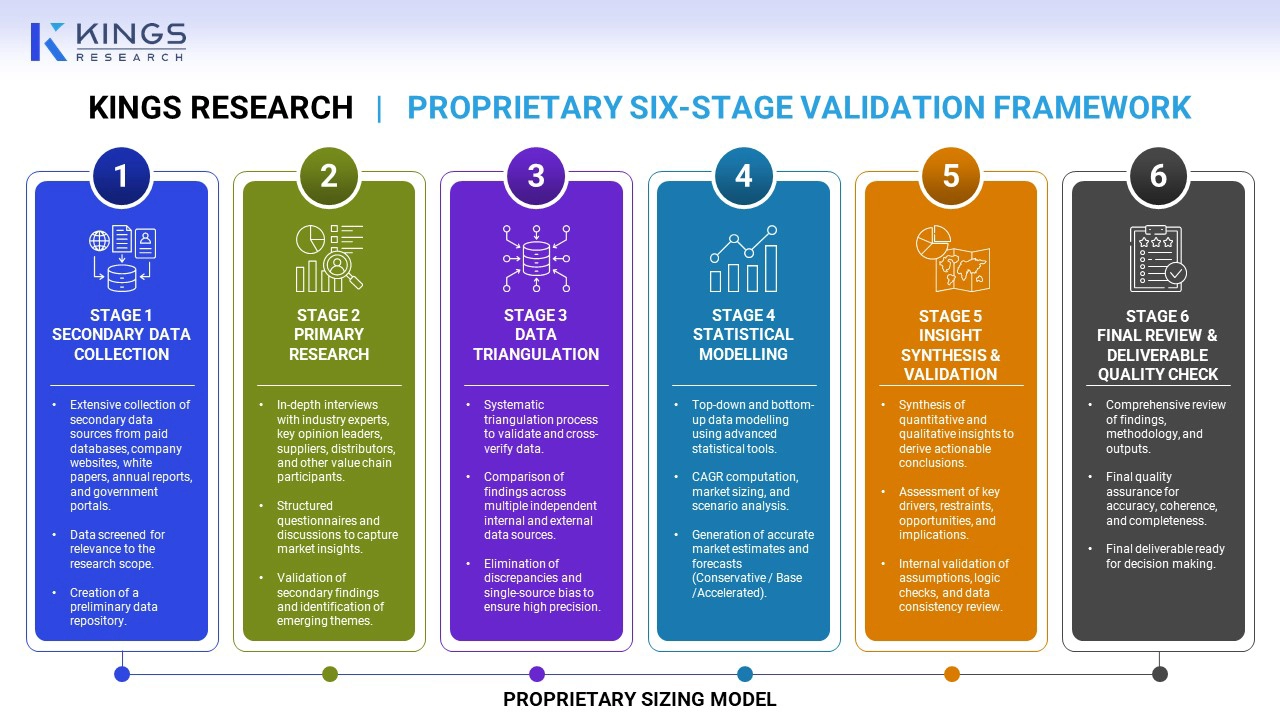
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Antriksh is an experienced analyst specializing in cross-domain research across diverse industries. With a strong foundation in data analysis and statistical interpretation, he delivers insightful market reports that guide strategic decision-making. Antriksh excels in conducting primary research, with a focus on identifying trends and understanding consumer behavior. Thriving in dynamic and high-pressure environments, he combines analytical expertise with a commitment to delivering impactful outcomes. Beyond his professional pursuits, Antriksh's passion for travel fuels his curiosity and broadens his perspectives, enriching his ability to uncover unique insights that enhance his research capabilities. He is equally adept at synthesizing quantitative findings with qualitative context, which allows him to present holistic viewpoints to clients. His disciplined work ethic and intellectual agility make him a trusted partner in navigating market uncertainties. He consistently seeks out new methodologies to refine his analytical toolkit, and his ability to communicate complex insights clearly ensures stakeholders act confidently on his recommendations.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


