
Inquire Now
Key strategic points
According to Kings Research, the global menswear market size was valued at USD 647.85 billion in 2025 and is projected to reach USD 886.74 billion by 2033, growing at a CAGR of 4.10% from 2026 to 2033.
The report covers products offered by companies such as Adidas AG, Nike, Inc., Ralph Lauren Corporation, Burberry Group plc, Hanesbrands Inc., Patagonia, Inc., Hugo Boss AG, Levi Strauss & Co., Fast Retailing Co., Ltd., PUMA SE, VF Corporation, Under Armour, Inc., Inditex, S.A., Ermenegildo Zegna N.V., Giorgio Armani S.p.A., Brooks Brothers, Lululemon Athletica Inc., PVH Corp., Gap Inc., and others.
This growth is largely driven by increasing fashion awareness among men and the growing impact of social media on style trends. Disposable income and apparel spending are rising in emerging markets. The increasing popularity of e-commerce platforms is also providing convenience and accessibility for consumers, expanding the reach of menswear styles and brands across different geographic locations.
The global menswear market is expected to grow during the forecast period, driven by increasing fashion awareness and rising digital penetration. The sector is diversifying by blending traditional and casual styles, reflecting the shift in workplace norms and culture toward more relaxed dress codes.
Manufacturers are prioritizing innovations in materials and sustainability practices to cater to environmentally conscious consumers, thereby significantly shaping market offerings and consumer preferences.
Apparel designed for men is sold through a variety of garments, footwear, and accessories. This market targets males across all age groups and spans both the mass market and luxury segments. It includes sales across various channels, such as physical stores and online platforms, to meet both seasonal and year-round apparel needs
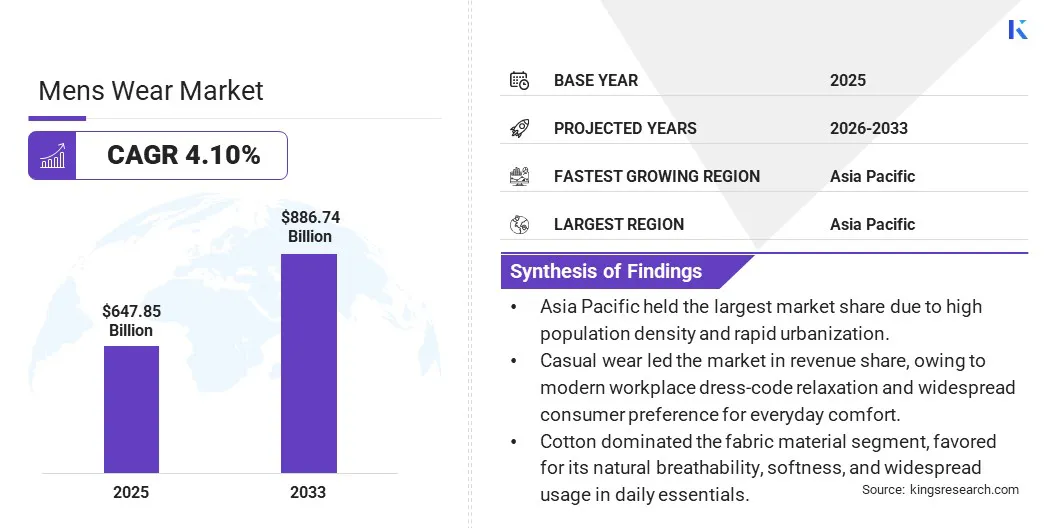
Fashion consciousness, digital innovation, and sustainability trends are driving rapid growth in the global menswear market. Increasing incomes and urbanization in emerging markets are also supporting market growth. However, these positive growth drivers are challenged by disruptions in the supply chain, inventory management issues, and rapidly changing fashion trends.
Even so, the overall trend of the market is positive, with brands that focus on innovation, sustainability, and evolving consumer preferences well positioned for growth.
The adoption of technology in the fashion industry is changing the landscape of the menswear market. Brands are using tools such as AR fitting rooms and AI-driven style assistants to enhance the shopping experience and personalize customer interactions. For example, Nike has rolled out AI-powered Smart Fitting Rooms across select physical retail locations, while industry-wide adoption of AI-driven virtual try-on technology has been shown to lift online conversion rates by as much as 25% through 3D body-scanning and sizing accuracy, reducing returns tied to poor fit.
This shift in technology is increasing the accuracy of size fittings, decreasing return rates, and enabling companies to collect detailed consumer data. This helps brands better coordinate product design and marketing strategies with consumer tastes, stimulating sales and building customer loyalty.
One of the biggest challenges the industry faces is consumer demand for new and trendy clothing options in a shorter period of time, which results in overproduction and more wasted inventory.
Brands are also adopting lean manufacturing approaches that emphasize just-in-time production and frequent, smaller product releases, enabling faster response to changing fashion trends. On-demand manufacturing reduces waste, resulting in a more sustainable and economical manufacturing process.
Increasing demand for sustainable fashion is influencing the dynamics of the menswear market. There is growing demand for sustainably and ethically produced clothing, as consumers, particularly younger generations, become more aware of their environmental and social footprint.
Brands are responding to this demand by embedding sustainability throughout their supply chains, from sourcing organic materials to reducing water and energy use and adopting green manufacturing processes. Companies are also addressing this in packaging and distribution, exploring biodegradable packaging and carbon-neutral shipping options.
Sustainability is becoming a key differentiator, and brands that demonstrate eco-conscious practices are resonating with discerning consumers. The blurring of traditional style boundaries is affecting the market, with consumers demanding greater casualization and versatility. This trend is also driven by lifestyle changes, such as the rise of remote employment and a growing focus on comfort.
This is reflected in the combination of formal and casual elements in menswear, with tailored pieces paired with athleisure or streetwear elements. The trend has also been supported by the growing popularity of gender-neutral and unisex fashion, with designs that are more inclusive of a wider range of individual looks and tastes. This trend is driving greater diversity and creativity in menswear design.
|
Segmentation |
Details |
|
By Product Type |
Formal Wear, Casual Wear, Sportswear / Activewear, Nightwear / Loungewear, Intimate Wear / Innerwear, Outerwear, Others |
|
By Fabric Material |
Cotton, Polyester, Wool, Silk, Nylon, Blended Fibers, Others |
|
By Price Category |
Mass, Mid-Range, Premium / Luxury |
|
By Distribution Channel |
Offline Stores, Online Stores |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, Rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South & Central America: Brazil, Argentina, Rest of South & Central America |
The global market is segmented by product type, fabric material, price category, and distribution channel.
Based on product type, the market is segmented into formal wear, casual wear, sportswear/activewear, nightwear/loungewear, intimate wear/innerwear, outerwear, and others.
Casual wear is the largest sub-segment, driven by the continued shift toward relaxed dress codes in both professional and social settings, as well as the growing popularity of versatile, everyday styles. Sportswear/activewear is the fastest-growing sub-segment, supported by rising health and fitness awareness and the ongoing athleisure trend, which continues to blur the line between performance wear and everyday clothing.
Advances in textile technology and manufacturing processes are enabling brands to offer a wider variety of high-quality, innovative clothing across all product categories. Consumer interest and engagement continue to grow as key players strengthen their marketing strategies and brand positioning across each segment.
Based on fabric material, the market is classified into cotton, polyester, wool, silk, nylon, blended fibers, and others.
Cotton is the largest sub-segment, owing to its comfort, breathability, and versatility across product types. Blended fibers are the fastest-growing sub-segment, as brands increasingly combine the performance benefits of synthetic materials, such as durability and moisture management, with the comfort of natural fibers, particularly within the sportswear/activewear and outerwear segments.
Based on price category, the market is classified into mass, mid-range, and premium/luxury.
The mass segment is the largest, supported by high-volume demand and broad accessibility across price-sensitive consumer groups. The premium/luxury segment is the fastest-growing, driven by rising disposable incomes, increasing brand consciousness, and growing demand for differentiated, high-quality products among aspirational consumers.
Based on distribution channel, the market is classified into offline stores and online stores.
Offline stores account for the largest share, supported by the ability of consumers to see, touch, and try on products before purchase, along with the in-store experience offered by flagship and multi-brand retail formats. This is driven by the diverse product offerings available in offline stores, along with strategic alliances and collaborations that make these stores more attractive to a broad customer base.
Online stores are the fastest-growing channel, driven by the increasing tendency toward experiential and personalized shopping, where customers seek curated recommendations and a seamless digital experience. Investments in omni-channel retailing and digitalization are enhancing the reach and accessibility of online stores, contributing to segment growth.
Based on region, the global market is classified into North America, Europe, Asia-Pacific, Middle East & Africa, and South and Central America.
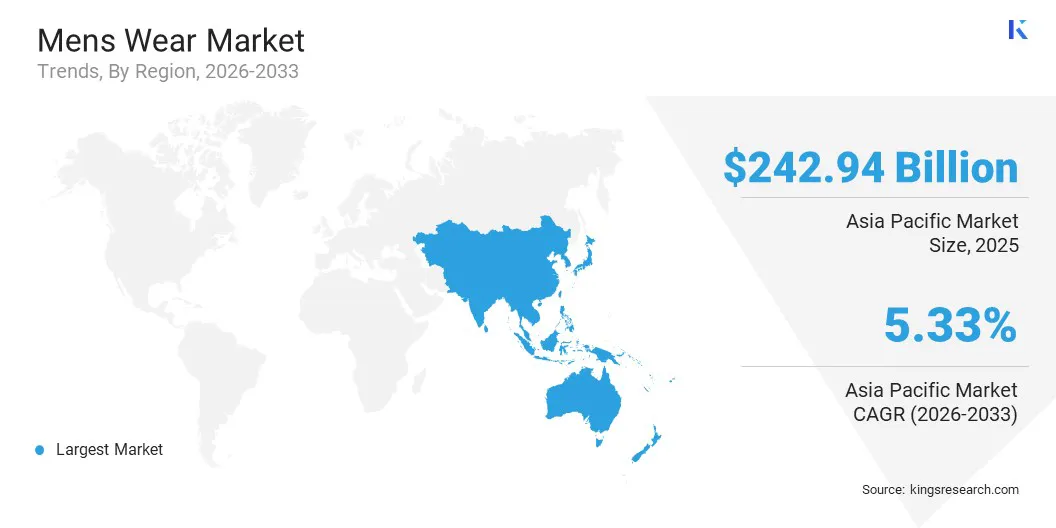
According to Kings Research, the Asia-Pacific menswear market held the largest regional share in 2025, accounting for 37.50% of the global market and valued at USD 242.94 billion. The region is projected to grow at a CAGR of 5.33% from 2026 to 2033, faster than the 4.10% global average. This regional dominance is fueled by the large populations of China and India, increasing disposable incomes, and rapid urbanization, with growing middle-class populations and rising purchasing power. This is driving increased demand for fashion and lifestyle products, including menswear.
Rapid urbanization and digitization in the region are also driving e-commerce adoption, offering consumers a convenient platform to access a wide range of menswear offerings. In addition, the region's rich textile manufacturing heritage and competitive production costs are enabling global brands to establish efficient supply chains, making Asia-Pacific a major hub for growth in the menswear industry.
The market is moderately fragmented, with global sportswear, luxury fashion, and fast-fashion companies competing on product innovation, digital retail expansion, sustainability efforts, and strategic collaborations. Key players are pursuing business strategies such as product innovation, joint ventures, mergers and acquisitions, and partnerships to expand their product portfolios and strengthen their market positions across regions.
Strategic initiatives such as investments in R&D, the establishment of new manufacturing facilities, and supply chain optimization continue to offer new avenues for market growth. For example, in January 2026, Ralph Lauren returned to the men's runway for the first time since 2002, presenting its Fall 2026 Purple Label and Polo Ralph Lauren collections at Milan Men's Fashion Week, including a new Polo Ralph Lauren x TÓPA collaboration with Oceti Sakowin designers, underscoring how established players are investing in brand storytelling and design collaborations to reinforce market position.
How We Gather This Information
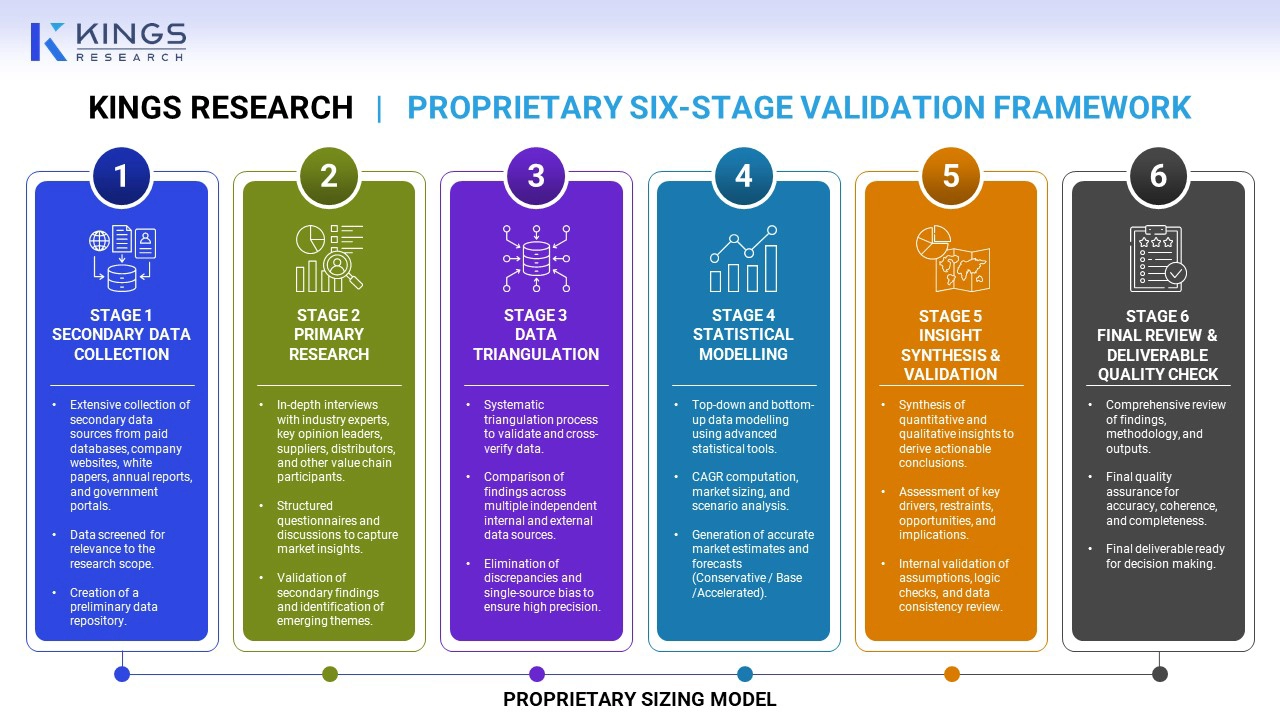
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Frequently Asked Questions

Ashim Lakhera is a market intelligence professional specializing in the Agriculture and Food & Beverage industry. His work focuses on emerging markets, competitive dynamics, industry trends, and the factors driving market growth and transformation. He has experience in market sizing, forecasting, strategic analysis, and industry research across food, FMCG, and life sciences. His research interests span the broader food and agriculture value chain, with a particular focus on how innovation, changing consumer behavior, sustainability priorities, and evolving production systems are influencing markets. He examines these developments to understand their impact on demand, competition, business models, and growth opportunities across the agri-food ecosystem. His work combines quantitative market analysis with an understanding of the broader industry forces shaping food and agriculture markets. He is particularly interested in the structural changes taking place across global food systems and how businesses are adapting to evolving consumer expectations, technological developments, and sustainability requirements.
Smriti Vinodia is a market research and consumer insights professional with expertise in qualitative research, consumer behavior, and strategic market intelligence across the FMCG and FMCD industries. She has experience supporting leading brands by transforming complex consumer and market insights into actionable strategies that inform product development, innovation, positioning, and business growth. Her expertise spans qualitative consumer research, market and competitive intelligence, consumer trend analysis, and AI-enabled insight generation. She has worked across diverse research engagements, helping organizations understand evolving consumer needs, identify emerging market opportunities, and strengthen customer-centric decision-making. Combining analytical rigor with a strong understanding of consumer psychology and market dynamics, Smriti brings a strategic perspective to research and insights. She focuses on connecting consumer behavior with commercial priorities, enabling organizations to make informed decisions, develop relevant products and experiences, and build sustainable growth strategies in rapidly evolving and competitive markets.


