Inquire Now
Key Strategic Points
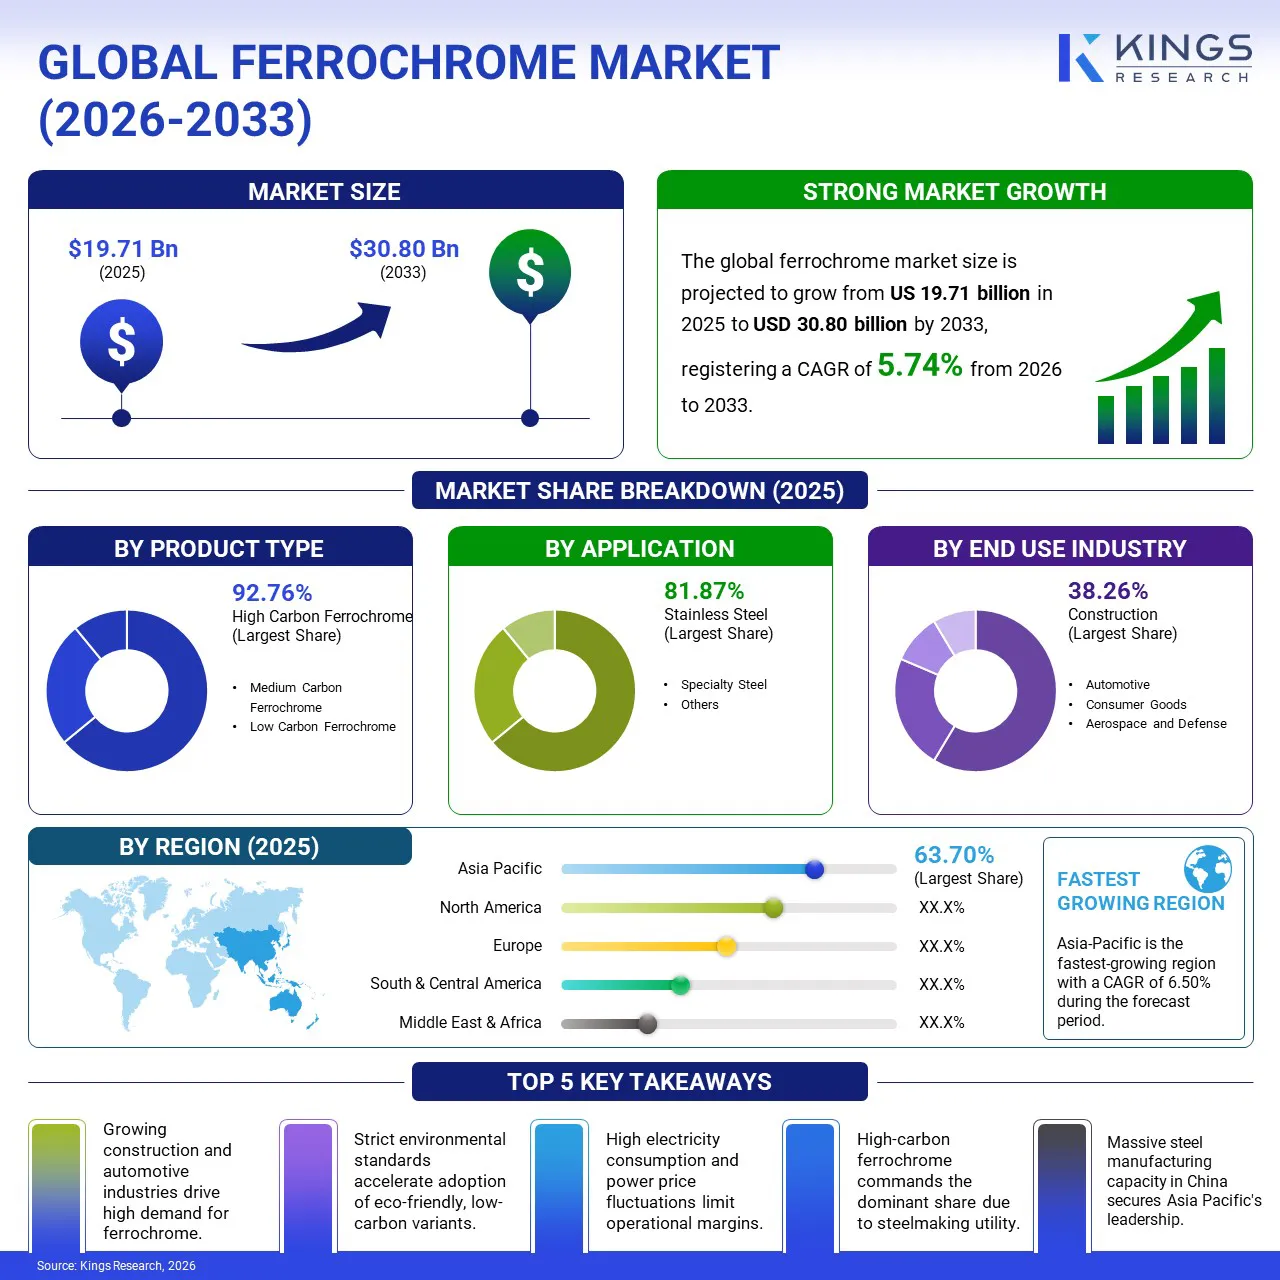
According to Kings Research, the global ferrochrome market size was valued at USD 19.71 billion in 2025 and is projected to reach USD 30.80 billion by 2033, exhibiting a CAGR of 5.74% during the forecast period (2026–2033).
The market involves mining companies, alloy smelters, and global steel manufacturers focused on producing high-grade chromium-iron alloys for stainless steel and specialty alloy production. The report explores key drivers of market development, offering detailed regional analysis and a comprehensive overview of the competitive landscape shaping future opportunities.
The market is expanding steadily, driven by rising global demand for stainless steel across construction, automotive, and industrial machinery sectors. Ferrochrome is essential in imparting corrosion resistance, tensile strength, and durability to stainless steel products. According to data from the Indian Ferro Alloy Producers' Association, stainless steel manufacturing consumes over 80% of global ferrochrome production.
Major companies operating in the ferrochrome market include Glencore, Samancor Chrome, Eurasian Resources Group (ERG), Tata Steel Mining Limited, Outokumpu, Jindal Steel & Power Ltd., Balasore Alloys Limited, Ferro Alloys Corporation Ltd. (FACOR), Fondelco Metal & Alloys Pvt. Ltd. (Fondelco Group), and IMFA (Indian Metals & Ferro Alloys Ltd.).
In August 2026, Outokumpu inaugurated a new biocoke agglomeration plant in Tornio, Finland, enabling the replacement of fossil coke with biomass-based biocoke in ferrochrome production. The approximately USD 35 million investment is expected to reduce CO₂ emissions by up to 82,000 tonnes annually at full production capacity, supporting the company's strategy to develop lower-carbon ferrochrome and strengthen sustainable production.
The global ferrochrome market is experiencing steady growth, driven primarily by expanding stainless steel manufacturing across emerging and developed economies. Stainless steel remains the largest end-use sector for ferrochrome, where chromium provides indispensable anti-corrosive and oxidation-resistant properties essential for architectural structures, chemical processing plants, and consumer appliances.
Additionally, ferrochrome is increasingly used in automotive manufacturing. The automotive industry utilizes high-strength stainless steel alloys for exhaust systems, structural chassis components, and trim parts. Rising vehicle production volumes, alongside strict emission standards requiring heat-resistant exhaust materials, drive continuous demand for high-quality ferrochrome alloys.
A primary restraint facing the ferrochrome market involves the extremely energy-intensive nature of submerged arc furnace (SAF) smelting operations. Electricity costs account for a significant portion of total production expenses. Consequently, fluctuations in regional energy tariffs, power load shedding, and carbon taxation policies directly impact smelter profitability and production continuity.
Furthermore, supply chain vulnerabilities associated with chromite ore mining, concentrated primarily in South Africa, Kazakhstan, and India, expose manufacturers to raw material price volatility, export duties, and logistical bottlenecks, constraining operational scaling.
The ferrochrome industry is witnessing a significant shift toward decarbonization, closed-furnace technology, and low-carbon product variants. Steelmakers are increasingly prioritizing supply chain sustainability, prompting ferrochrome producers to implement closed submerged arc furnaces that capture off-gases for energy recovery and reduce carbon emissions.
| Segmentation | Details |
| By Application | Stainless Steel, Specialty Steel, Others |
| By Product Type | High Carbon Ferrochrome, Medium Carbon Ferrochrome, Low Carbon Ferrochrome |
| By End Use Industry | Automotive, Construction, Consumer Goods, Aerospace, and Defense |
| By Region | North America: U.S., Canada, Mexico |
| Europe: France, UK, Spain, Germany, Italy, Russia, and the rest of Europe | |
| Asia Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia Pacific | |
| Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa | |
| South and Central America: Brazil, Argentina, and the rest of South and Central America |
Based on application, the market is segmented into stainless steel, specialty steel, and others. Stainless steel holds the largest market share of 81.87% in 2025, supported by ferrochrome's essential role in improving corrosion resistance, strength, and durability. Specialty Steel is witnessing steady demand, driven by the increasing use of high-performance steels in automotive, aerospace, industrial machinery, and other demanding applications.
Based on product type, the market is segmented into high carbon ferrochrome, medium carbon ferrochrome, and low carbon ferrochrome. High carbon ferrochrome holds the largest market share of 92.76% in 2025, owing to its cost efficiency, high chromium content, and extensive use in stainless steel production. Low carbon ferrochrome is witnessing strong growth, driven by increasing demand for controlled-carbon alloy and specialty steels where precise carbon levels are required.
Based on end-use industry, the market is segmented into automotive, construction, consumer goods, and aerospace and defense. Construction holds a significant market share of 38.26%, supported by the extensive use of chromium-containing stainless steel in buildings and infrastructure, where corrosion resistance, strength, durability, and low maintenance are critical. Ferrochrome is the essential raw material for stainless steel.
Asia Pacific held the largest market share of 63.70% in 2025, with an anticipated CAGR of 6.50% during the forecast period. According to Kings Research, regional dominance is driven by massive stainless steel production capacity in China and India, rapid urban infrastructure development, and growing automotive manufacturing. Regional industrial growth and strong domestic chromite processing infrastructure reinforce Asia Pacific's leading position.
According to Kings Research, Europe represents a major revenue hub in the global ferrochrome market, driven by advanced engineering industries, high-value stainless steel manufacturing, and a strong focus on decarbonization. Regional Regulatory Frameworks Play a Significant Role in Shaping the Market, where strict carbon footprint tracking and energy efficiency standards encourage adoption of low-carbon ferrochrome.
North America accounts for a significant share of global demand, supported by robust aerospace manufacturing, industrial equipment production, and automotive sector consumption across the United States and Canada. Rising demand for high-strength corrosion-resistant alloys in energy infrastructure further drives regional imports.
The Middle East & Africa region holds a crucial role in the market as a primary production and chromite ore mining hub, particularly in South Africa. Domestic consumption is expanding due to mega-construction projects and industrial diversification initiatives across GCC economies.
South and Central America is experiencing steady market growth, led by Brazil and Mexico, propelled by expanding automotive assembly operations, mining machinery fabrication, and regional infrastructure investments.
The global market is characterized by a large number of participants, including both established corporations and rising organizations. Companies in the ferrochrome market are expanding through strategic mergers, acquisitions, and investments in production capacity.
They are also exploring new markets, enhancing technological advancements, and focusing on sustainable practices to meet the growing global demand for stainless steel.
How We Gather This Information
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Siddhi is an accomplished professional with deep expertise in research and analysis, excelling in delivering customized reports across a wide range of industries. With a focus on extracting actionable insights, Siddhi's ability to navigate through various sectors demonstrates her cross-domain expertise. She approaches each assignment with a meticulous and data-driven mindset, translating complex market trends into clear recommendations that guide decision-making. Beyond her professional work, Siddhi is passionate about tracking B2B growth opportunities, staying ahead of industry trends, and continually expanding her knowledge through reading and research. Her dedication to precision ensures every report is comprehensive and actionable. Siddhi's ability to synthesize disparate data into cohesive narratives makes her a valuable asset in strategic planning. She tailors her analyses to client-specific contexts, enhancing relevance. Her proactive monitoring of emerging shifts keeps recommendations timely, while her intellectual curiosity drives her to explore adjacent sectors, further broadening her analytical scope and strengthening the insights she delivers.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.