Inquire Now
Key Strategic Points
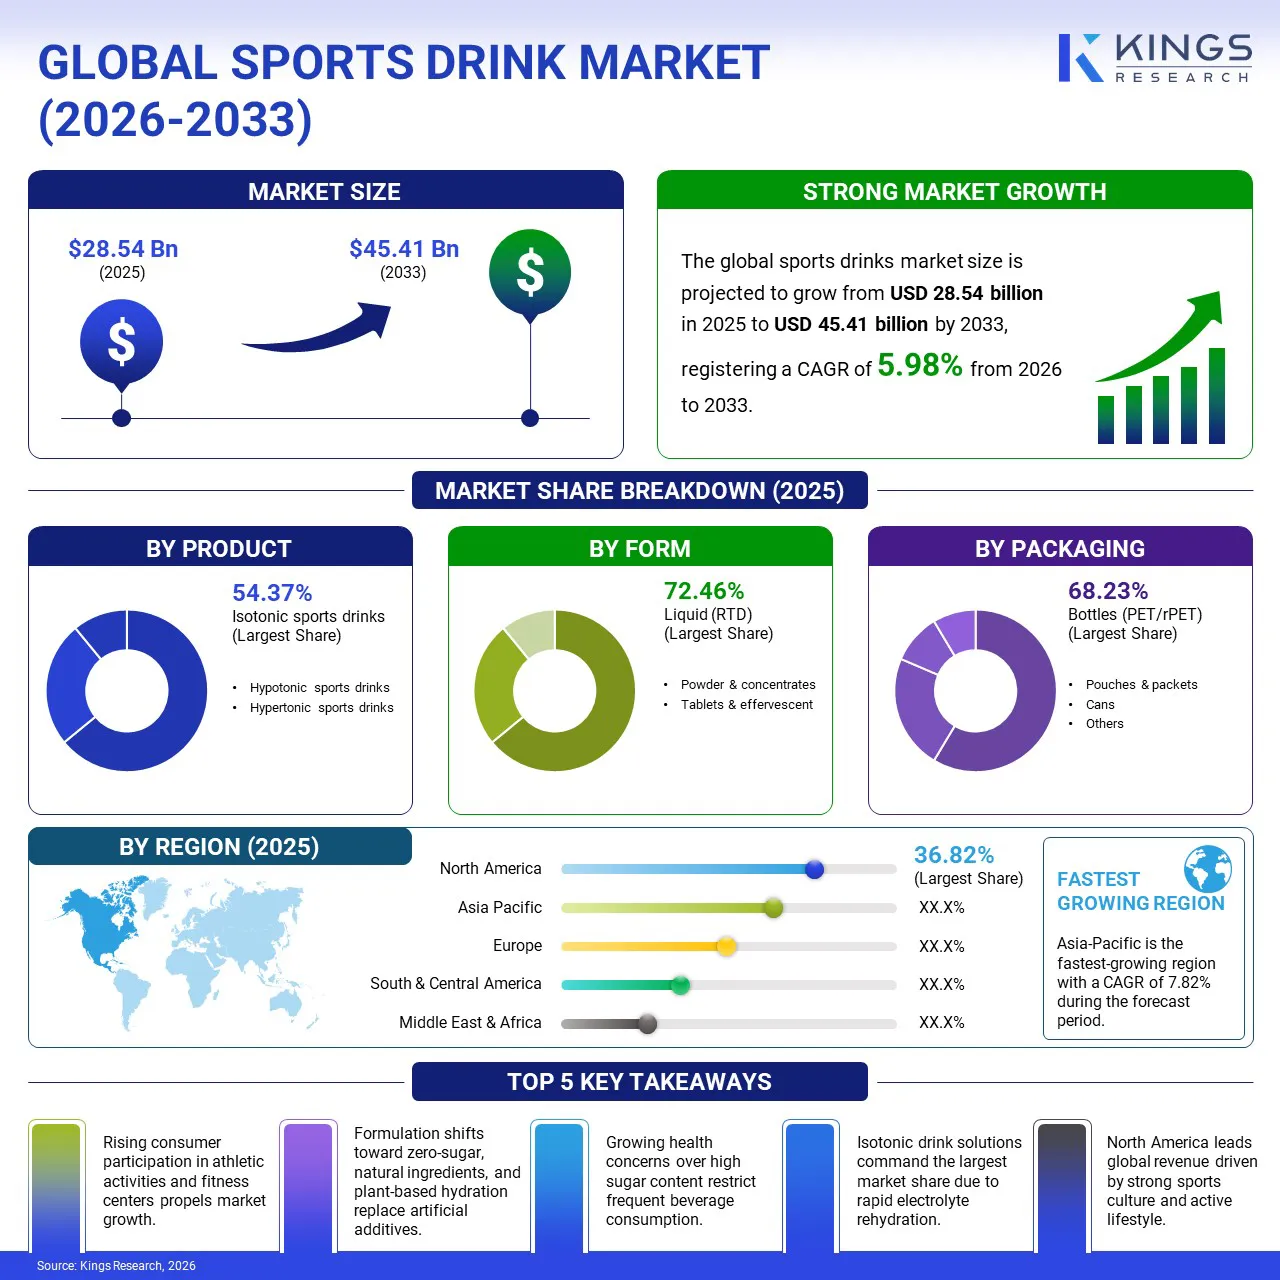
According to Kings Research, the global sports drink market size was valued at USD 28.54 billion in 2025 and is projected to reach USD 45.41 billion by 2033, exhibiting a CAGR of 5.98% during the forecast period (2026-2033).
The market encompasses isotonic, hypotonic, and hypertonic beverage formulations distributed in ready-to-drink (RTD) bottles, cans, and powder concentrates across residential, athletic, and commercial consumer segments. The report explores key drivers of market development, offering detailed regional analysis and a comprehensive overview of the competitive landscape shaping future opportunities.
The market is expanding steadily, driven by increasing consumer awareness of physical fitness, expanding athletic participation, and rising demand for functional hydration products containing essential electrolytes. Product innovations in clean-label, natural, and low-sugar formulations, along with expanding retail and e-commerce distribution channels, further propel growth.
Major companies operating in the sports drink market include PepsiCo, Inc., The Coca-Cola Company, Monster Energy Company, Red Bull GmbH, Otsuka Pharmaceutical Co., Ltd., Suntory Holdings Limited, Arizona Beverages USA, Abbott Laboratories, Nestlé S.A., and BA Sports Nutrition, LLC (BODYARMOR).
The global sports drink market is experiencing steady growth, driven by growing consumer participation in athletics, gym workouts, and recreational sports. Rising awareness regarding the importance of electrolyte replenishment and fluid balance during intense physical exertion accelerates functional beverage consumption.
Co-branding deals between mainstream beverage giants and sports nutrition firms are expanding retail shelf space for functional hydration drinks. Furthermore, active lifestyle adoption among non-professional fitness enthusiasts widens the overall consumer base beyond traditional professional athletes.
A primary restraint facing the sports drink market involves growing health scrutiny regarding high added sugar content, artificial colorants, and synthetic flavorings in traditional sports drinks. Increasing consumer awareness of metabolic health conditions, obesity, and dental erosion leads health-conscious consumers to seek natural water or low-calorie alternatives.
Additionally, fluctuations in packaging raw material prices (such as PET resin and aluminum) and rising freight transport costs impact manufacturing margins. Regulatory mandates restricting high-sugar beverage sales near educational institutions and sugar taxation in select international markets also impose compliance and operational hurdles on manufacturers.
The market is undergoing a significant transformation driven by clean-label natural ingredients, zero-sugar formulations, and functional additive enhancements (such as BCAAs, vitamins, and adaptogens). Consumers are increasingly seeking sports beverages formulated with natural coconut water, stevia sweeteners, real fruit juices, and organic electrolyte salts without artificial dyes.
This shift toward transparency and ingredient simplicity enhances brand trust and spurs innovation, driving demand for clean-label products. Simultaneously, manufacturers are leveraging eco-friendly bio-based PET packaging and expanding direct-to-consumer (DTC) subscription models for hydration powders and effervescent tablets.
|
Segmentation |
Details |
|
By Product |
Isotonic sports drinks, hypotonic sports drinks, and hypertonic sports drinks |
|
By Form |
Liquid (RTD), powder & concentrates, and tablets & effervescent |
|
By Packaging |
Bottles (PET/rPET), Pouches & Packets, Cans, and Others |
|
By Distribution Channel |
Hypermarkets & supermarkets, online retailers, convenience stores, and specialty & sports nutrition stores |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, U.A.E., Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South and Central America: Brazil, Argentina, and the rest of South and Central America |
The market is categorized into isotonic sports drinks, hypotonic sports drinks, and hypertonic sports drinks. According to Kings Research, the isotonic sports drinks segment held the largest market share of 54.37% in 2025, supported by their ability to provide rapid hydration while replenishing carbohydrates and electrolytes lost through sweating, making them suitable for prolonged and high-intensity physical activity.
The market is categorized into liquid (RTD), powder & concentrates, and tablets & effervescent. According to Kings Research, the liquid (RTD) segment held the largest share of 72.46% in 2025, fuelled by its convenience for immediate consumption and widespread availability across retail outlets.
The market is categorized into bottles (PET/rPET), pouches & packets, cans, and others. According to Kings Research, the Bottles (PET/rPET) segment has the highest share of 68.23% in 2025, owing to its portability, reusability, and rising consumer preference for convenient on-the-go hydration.
The market is categorized into hypermarkets/supermarkets, specialty stores, online retailers, convenience stores, and others. According to Kings Research, the hypermarkets/supermarkets segment has the highest revenue share, propelled by high product visibility, wide selection, and the convenience of one-stop shopping.
Based on region, the market has been classified into North America, Europe, Asia Pacific, the Middle East & Africa, and South and Central America.
The North American sports drink market accounted for a substantial share of 36.82% in 2025. This dominance is reinforced by the region's well-established distribution network, including extensive shelf space in convenience stores at gas stations.
The regional market benefits from a strong sports nutrition industry linked to collegiate and high school athletics, where sports drinks are widely adopted as part of training and recovery routines.
Additionally, the U.S. has seen a rise in consumer interest in functional beverages as alternatives to carbonated soft drinks, accelerating volume sales among health-conscious adults beyond the athletic segment.
The Asia-Pacific sports drink industry is expected to register the fastest CAGR of 7.82% over the forecast period, driven by increasing health awareness and a rising fitness culture among young consumers. Additionally, increased participation in sports and outdoor activities, coupled with expanding e-sports and gym memberships, fuels regional market expansion.
Moreover, strong investments by multinational brands in regional manufacturing and tailored marketing, such as cricket promotions in South Asia and badminton in Southeast Asia, are enhancing brand visibility and consumer adoption in this diverse market.
According to Kings Research, Europe accounts for a significant market share, driven by high participation in endurance sports, strict EU food safety regulations regarding artificial additives, and strong consumer preference for natural, low-sugar functional beverages across Germany, the UK, and France.
The Middle East & Africa region is witnessing steady growth in sports drink consumption, supported by high warm-climate hydration needs, expanding athletic facility infrastructure, and rising disposable incomes across GCC economies. South & Central America is experiencing gradual market growth, led by Brazil and Mexico, propelled by strong sports culture, expanding urban retail networks, and increasing availability of localized RTD sports beverages.
The sports drink industry is characterized by key players continuously refining their strategies to grow their market share. Companies prioritize product launches, line extensions, and partnerships with major sports teams and events to enhance brand presence.
Expansion into emerging markets through localized production and tailored marketing is a common strategy. Firms also focus on strengthening distribution by integrating traditional retail with online platforms. Furthermore, strategic mergers and acquisitions are leveraged to consolidate resources and access new consumer segments.
How We Gather This Information
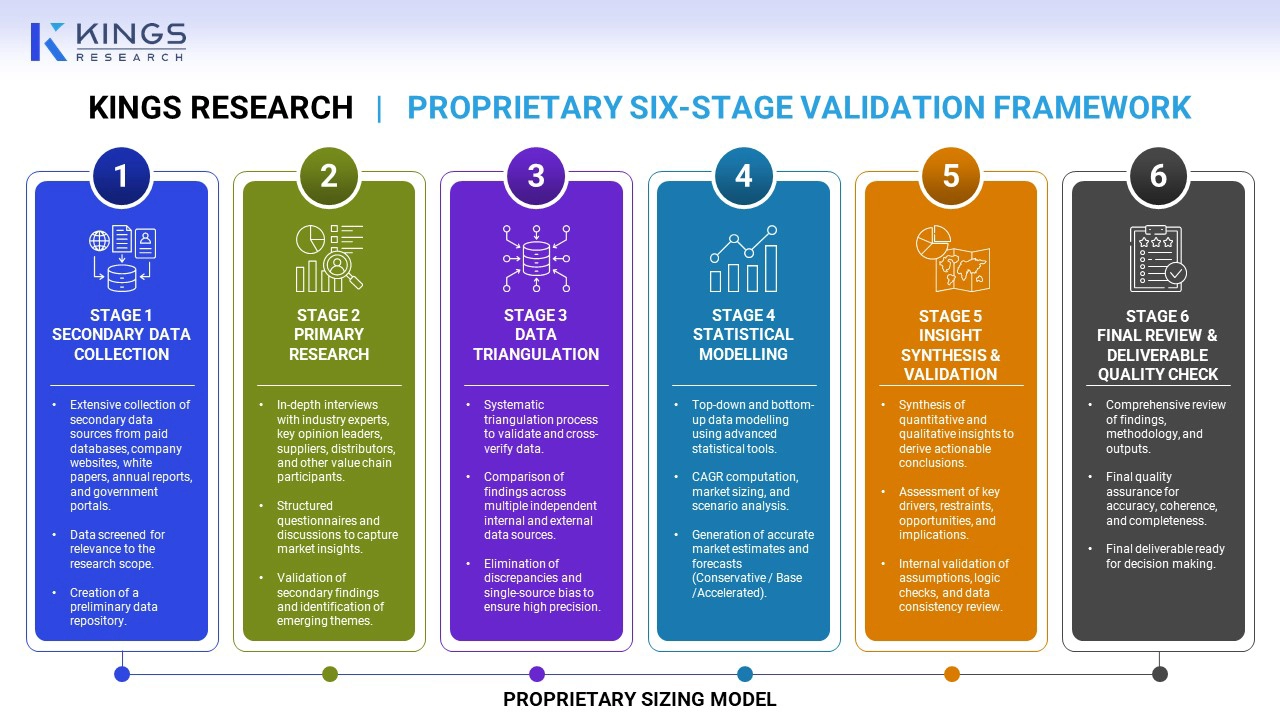
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Siddhi is an accomplished professional with deep expertise in research and analysis, excelling in delivering customized reports across a wide range of industries. With a focus on extracting actionable insights, Siddhi's ability to navigate through various sectors demonstrates her cross-domain expertise. She approaches each assignment with a meticulous and data-driven mindset, translating complex market trends into clear recommendations that guide decision-making. Beyond her professional work, Siddhi is passionate about tracking B2B growth opportunities, staying ahead of industry trends, and continually expanding her knowledge through reading and research. Her dedication to precision ensures every report is comprehensive and actionable. Siddhi's ability to synthesize disparate data into cohesive narratives makes her a valuable asset in strategic planning. She tailors her analyses to client-specific contexts, enhancing relevance. Her proactive monitoring of emerging shifts keeps recommendations timely, while her intellectual curiosity drives her to explore adjacent sectors, further broadening her analytical scope and strengthening the insights she delivers.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.