
Inquire Now
Key Strategic Points
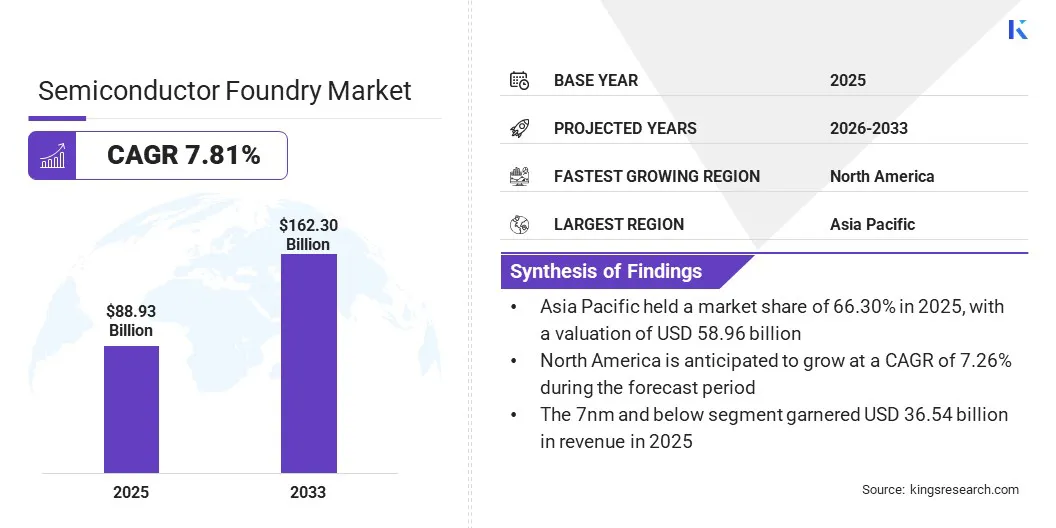
According to Kings Research, the global semiconductor foundry market size was valued at USD 88.93 billion in 2025 and is projected to grow from USD 95.88 billion in 2026 to USD 162.30 billion by 2033, exhibiting a CAGR of 7.8% during the forecast period. The rising proliferation of consumer electronics, particularly smartphones, laptops, and tablets, is driving the growth of advanced semiconductor chips, which in turn fuels the market growth.
A semiconductor foundry, also known as a chip foundry, is a specialized manufacturing facility dedicated to producing integrated circuits (ICs) and semiconductor devices based on designs provided by external clients. Foundries handle the fabrication of silicon wafers and the intricate processes required to create transistors and other components.
They cater to fabless semiconductor companies, which design chips and outsource production, as well as integrated device manufacturers (IDMs) that both design and manufacture their own chips. Foundries play a crucial role in the global electronics industry, fostering innovation and meeting the growing demand for advanced semiconductor technology.
In the scope of work, the report includes services offered by companies including Taiwan Semiconductor Manufacturing Company (TSMC), Samsung Electronics Co., Ltd., GlobalFoundries, United Microelectronics Corporation, Semiconductor Manufacturing International Corporation (SMIC), Hua Hong Grace Semiconductor Limited, Tower Semiconductor Ltd., Powerchip Semiconductor Manufacturing Corporation (PSMC), Nexchip Semiconductor Corp., and Vanguard International Semiconductor Corporation (VIS).
Moreover, the global rollout of 5G technology is bolstering the expansion of the semiconductor foundry market. The demand for faster data transfer and low-latency communication requires advanced semiconductor solutions. Foundries are tasked with developing chips that support high-speed 5G networks and infrastructure.
Additionally, the integration of 5G into various applications, such as IoT, autonomous vehicles, and smart cities, highlights the pressing need for sophisticated semiconductor components.
According to 5G Americas, global 5G connections reached 2.8 billion in Q3 2025, which are rapidly expanding. In November 2025, reportedly 379 commercial 5G networks were deployed globally, alongside 707 LTE networks. This in turn drives the demand for advanced semiconductor chips, thereby increasing the need for semiconductor foundry manufacturing capacity to support 5G infrastructure and devices.
Semiconductor foundries are increasingly integrating cutting-edge technologies such as extreme ultraviolet (EUV) lithography into their production processes, which is essential for manufacturing advanced semiconductor devices.
EUV lithography enables the creation of smaller, more intricate chip features, a critical requirement for achieving higher performance and lower power consumption in modern electronics. By adopting EUV, foundries enhance their ability to produce next-generation chips with superior precision and efficiency.
Moreover, the development of emerging technologies, including quantum computing and edge computing, is significantly contributing to the expansion of the semiconductor foundry market. Quantum computing necessitates specialized chips to handle complex computations, while edge computing requires high-performance processors for real-time data processing. Semiconductor foundries are essential for manufacturing the advanced chips needed for these innovative technologies, thereby supporting market growth.
Government initiatives and investments in semiconductor manufacturing are crucial factors fueling market growth. Countries are increasingly recognizing the strategic importance of domestic semiconductor production and are providing financial incentives and support.
Initiatives such as the CHIPS Act in the U.S. and similar programs in Europe (European Chips Act) and Asia are aimed at boosting local manufacturing capabilities. The investments help reduce reliance on foreign suppliers and promote the development of new foundry facilities.
Moreover, the growth of data centers and cloud computing services is supporting the development of the semiconductor foundry market. Data centers require high-performance chips to manage large volumes of data and support cloud-based applications. The rise in digital services and cloud infrastructure increases the demand for semiconductors, thereby boosting market growth.
However, geopolitical tensions and trade restrictions pose a significant challenge to the development of the market. Trade disputes, export controls, and tariffs disrupt global supply chains, limit access to essential technologies, and create market uncertainties. These issues impede the smooth flow of materials and technology required for semiconductor manufacturing.
To address these challenges and sustain market growth, companies are diversifying their supply chains to reduce dependency on any single region or supplier, thereby mitigating the impact of trade disruptions. They are further investing in local production capabilities and establishing regional manufacturing hubs to enhance supply chain resilience.
The automotive sector's shift toward electric vehicles (EVs) and autonomous driving systems significantly impacts the semiconductor foundry market. Modern vehicles require an array of semiconductor components, including sensors, processors, and power management ICs.
The development of EVs and advanced driver-assistance systems (ADAS) creates demand for chips that ensure energy efficiency, safety, and performance. The growing emphasis on smart and connected vehicles further highlights the need for specialized semiconductor solutions.
According to the International Energy Agency's Global EV Outlook 2026, global electric car sales grew by 20%, increasing the share of total car sales to 25%. This indicates a rise in demand for semiconductors to address the growing demand from the EV sector.
Additionally, the semiconductor industry’s transition to miniaturization and advanced process technology is generating a substantial demand for foundries. As semiconductor devices become smaller and grow more complex, the need for cutting-edge manufacturing processes increases.
Advancements in process nodes, such as 7nm, 5nm, and 3nm technologies, enable the production of chips with higher performance and lower power consumption. Semiconductor foundries invest in developing and implementing these advanced technologies to meet the evolving demands of various applications.
The global market has been segmented by technology node, foundry, application, and geography.
Based on technology node, the market has been segmented into 7nm and below, 10nm–20nm, 20nm–45nm, and 45nm and above. The 7nm and below segment led the semiconductor foundry market in 2025, reaching a valuation of USD 31.88 billion. With the growing demand for high-performance computing, artificial intelligence, and advanced mobile devices, semiconductor manufacturers are increasingly focusing on these smaller nodes.
Chips produced at 7nm and below offer higher transistor density, which leads to faster processing speeds and reduced power consumption. This development is crucial for meeting the performance requirements of modern applications such as AI accelerators and 5G infrastructure, thereby boosting segmental growth.
Based on foundry, the semiconductor foundry industry is segmented into pure-play foundries and IDMs. The pure play foundry segment secured the largest revenue share of 73.89% in 2025. Pure-play foundries specialize exclusively in semiconductor manufacturing, without engaging in design.
This business model enables them to focus solely on optimizing their manufacturing processes, achieving high levels of efficiency, and investing in cutting-edge technologies. By concentrating on fabrication, pure-play foundries can scale production rapidly and cater to a broad range of clients, including fabless semiconductor companies that design chips without manufacturing them.
Based on application, the market is bifurcated into telecommunication, automotive, consumer electronics, industrial, healthcare, and others. The automotive segment is set to witness significant growth at a robust CAGR of 10.46% through the forecast period.
The high share of automotive applications is attributed to the high reliance of modern vehicles on advanced semiconductor components for various applications, including electric powertrains, autonomous driving systems, and in-car entertainment. The shift toward electric vehicles (EVs) and advanced driver-assistance systems (ADAS) requires sophisticated chips for battery management, sensor fusion, and real-time processing. Additionally, the transition to connected vehicles and smart automotive technologies increases the demand for high-performance semiconductors.
Based on region, the global market has been classified into North America, Europe, Asia-Pacific, Middle East and Africa, and South and Central America.
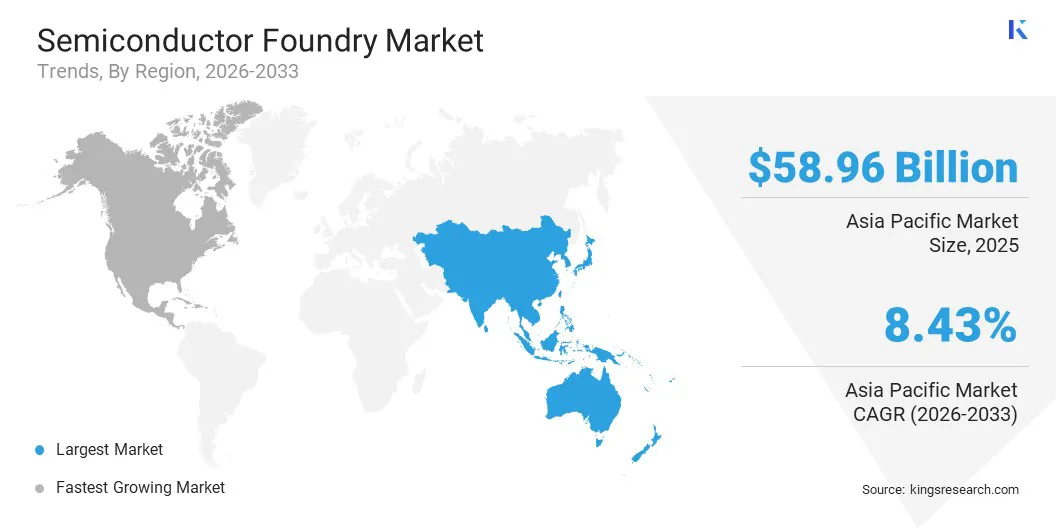
Asia Pacific semiconductor foundry market accounted for a share of around 66.30% in 2025, with a valuation of USD 58.96 billion. The Asia-Pacific region, particularly Taiwan, South Korea, and China, houses the world's largest and most advanced semiconductor manufacturers, including industry leaders such as TSMC, Samsung, and SMIC. Their dominance in semiconductor manufacturing positions the Asia-Pacific region as a leading hub for semiconductor foundries.
According to the Asian Development Bank, East Asia and Southeast Asia account for over 80% of global semiconductor manufacturing, with a major portion concentrated in Taiwan and South Korea. Japan is home to several of the largest companies that provide critical equipment and materials for the semiconductor industry, while China is designated as the global leader in photovoltaic cell production, which is a key segment within the broader semiconductor sector.
Additionally, the dominant position of the Asia-Pacific as a global hub for consumer electronics production, with countries such as China, South Korea, and Japan leading the manufacturing of smartphones, laptops, and other devices, further drives the demand for semiconductors. This dominance generates substantial demand, supporting the growth of the Asia-Pacific semiconductor foundry market.
North America is set to experience notable growth at a robust CAGR of 7.26% over the forecast period. The region hosts several leading fabless semiconductor companies, including Qualcomm, NVIDIA, AMD, and Broadcom, specializing in chip design and innovation.
These companies rely on external foundries for manufacturing, creating a strong demand for advanced semiconductor fabrication. The dominance of the region in chip design, coupled with partnerships with global foundries, contributes to the expansion of the semiconductor industry in North America.
Furthermore, the U.S. government’s commitment to strengthening domestic semiconductor manufacturing through initiatives such as the CHIPS and Science Act is contributing significantly to regional market growth. The act allocates significant funding to boost semiconductor research, development, and production. This government-backed support creates favorable conditions for investment and expansion in the North American market.
The global semiconductor foundry market is moderately concentrated owing to the presence of notable companies comprising Samsung Foundry, SMIC, and UMC accounting for much of the remaining share with TSMC capturing a dominant portion of the market. Industry players are focusing on strategic partnerships to drive product innovations, expand their product portfolio, and increase their market share. Strategic initiatives, including investments in R&D activities, establishment of new manufacturing facilities, and supply chain optimization, are creating new opportunities for market players.
In July 2026, UMC commenced foundry capacity expansion in Singapore and Taiwan to address rising demand from AI and edge-computing applications. The phased expansion strengthens supply-chain resilience and supports the growing need for high-performance semiconductor technologies.
In February 2026, SMIC introduced plans to add approximately 40,000 12-inch equivalent wafers of monthly capacity by the end of 2026. The expansion highlights sustained foundry demand, while rising depreciation and capital expenditure are expected to pressure margins.
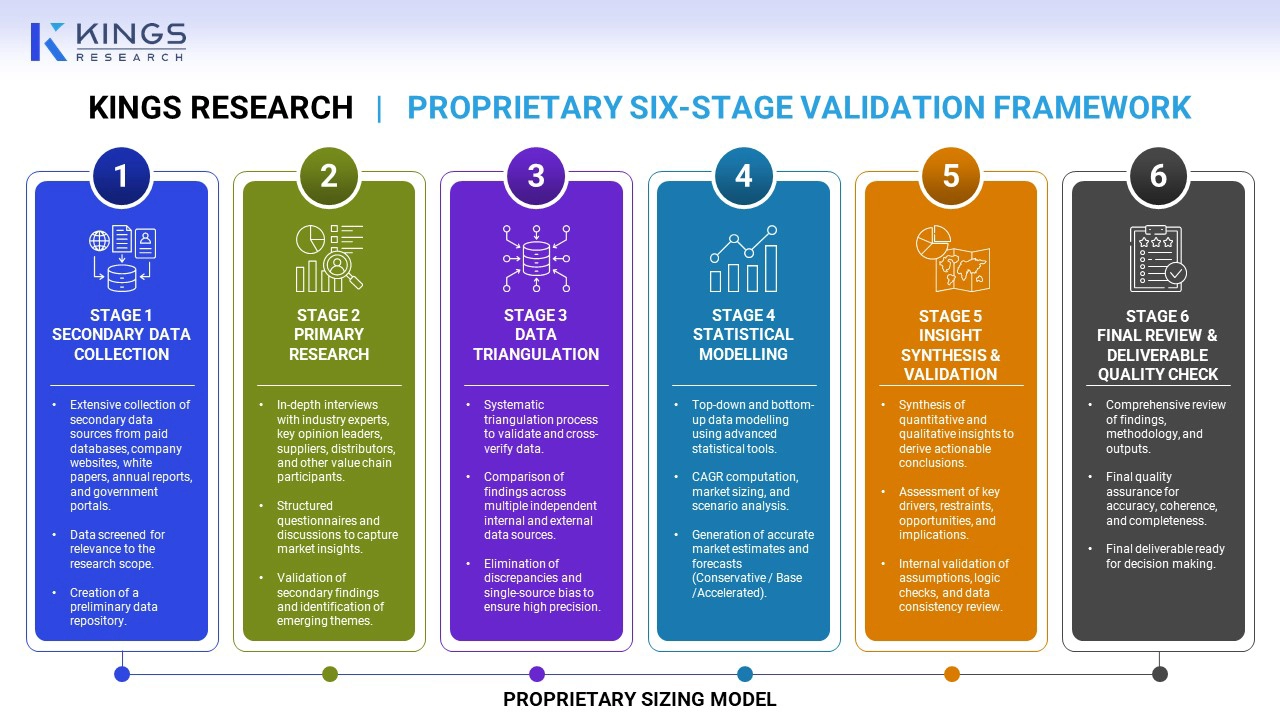
How We Gather This Information
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified, no single-source data is presented without validation.
Frequently Asked Questions

Sunanda is a proficient research analyst with strong cross-domain expertise, excelling in identifying market trends and delivering insightful analyses across various industries, including consumer goods, food & beverages, healthcare, and more. Her ability to connect insights from diverse sectors enables her to offer actionable recommendations that support strategic decision-making in a range of business contexts. Sunanda's research is driven by thorough data analysis and her commitment to providing relevant, data-driven insights. Her keen eye for patterns allows her to spot emerging opportunities before they become mainstream. Sunanda's synthesis of cross-sector learnings often reveals unconventional solutions that clients find invaluable. She adapts her analytical frameworks to suit each industry's unique nuances, ensuring reports are both accurate and contextually relevant. Clients appreciate her ability to deliver crisp, actionable findings under tight deadlines, consistently exceeding expectations with her thoroughness and insight.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


