
Inquire Now
Key Strategic Points
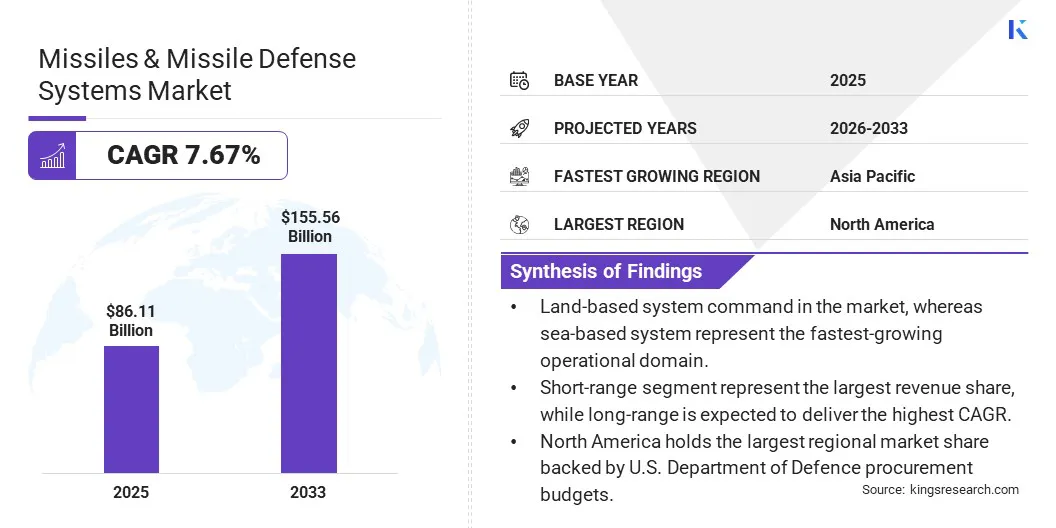
According to Kings Research, the global missiles and missile defense systems market size was valued at USD 86.11 billion in 2025 and is projected to reach USD 155.56 billion by 2033, exhibiting a CAGR of 7.67% during the forecast period.
The growth of the market is propelled by increasing geopolitical tensions, advancements in missile technology, and rising defense budgets globally. Governments and defense organizations are prioritizing military modernization to enhance national security and counter emerging threats.
This growth is further fueled by the development of hypersonic missiles, integration of artificial intelligence (AI) in missile defense, and growing investments in space-based defense systems.
Major companies operating in the missiles and missile defense systems industry are Lockheed Martin Corporation, RTX, Boeing, Northrop Grumman, BAE Systems, Thales, IAI, Kongsberg Defense & Aerospace, Bharat Dynamics Limited, MBDA Inc., Rheinmetall AG, Leonardo S.p.A., Saab AB, Denel Dynamics, and others.
Kings Research finds that geopolitical conflicts and regional security threats are prompting nations to strengthen their missile defense capabilities, supporting market growth. Countries in North America, Europe, and Asia-Pacific are investing in next-generation missile technologies to deter potential adversaries.
Military modernization programs in nations such as the U.S., China, India, and Russia are fueling demand for advanced missile systems, hypersonic weapons, and sophisticated interceptor technologies. For instance, the U.S. Department of Defense (DoD) continues to invest in missile defense programs such as the Terminal High Altitude Area Defense (THAAD) and the Aegis Ballistic Missile Defense (BMD) system, while European countries are enhancing their missile defense infrastructure under NATO's collective security framework.
Rapid development of hypersonic missiles is significantly driving market growth. Hypersonic missiles, including Hypersonic Glide Vehicles (HGVs) and Hypersonic Cruise Missiles (HCMs), travel at speeds exceeding Mach 5, making them difficult to detect and intercept with conventional defense systems.
Leading defense contractors, such as Lockheed Martin, Northrop Grumman, and RTX, are investing heavily in hypersonic missile research and development. The operational deployment of hypersonic missiles by Russia and China is prompting the U.S. and NATO allies to accelerate their hypersonic missile defense programs, propelling market expansion.
A significant challenge impeding market growth is the high cost of developing and producing advanced missile systems. The research, testing, and manufacturing of cutting-edge technologies such as hypersonic missiles, space-based defense systems, and interceptors require substantial investment, making these projects financially demanding.
To address this, companies are adopting cost-effective manufacturing, modular designs, and public-private partnerships to reduce financial burden. Advancements in automation and AI-driven technologies are also streamlining production and reducing costs while maintaining performance.
The rising focus on space-based missile defense is fueling substantial investment in satellite-enabled early warning systems, directed energy weapons (DEWs), and space-based interceptors. The U.S. Space Force is leading the development of space-based missile tracking and interception systems to counter hypersonic and ballistic missile threats.
Advanced programs such as the Hypersonic and Ballistic Tracking Space Sensor (HBTSS) aim to provide real-time threat tracking from space, enhancing global missile defense capabilities. The deployment of laser-based and kinetic-energy space weapons is also being explored, further supporting market expansion.
Based on region, the global market is classified into North America, Europe, Asia-Pacific, Middle East & Africa, and South and Central America.
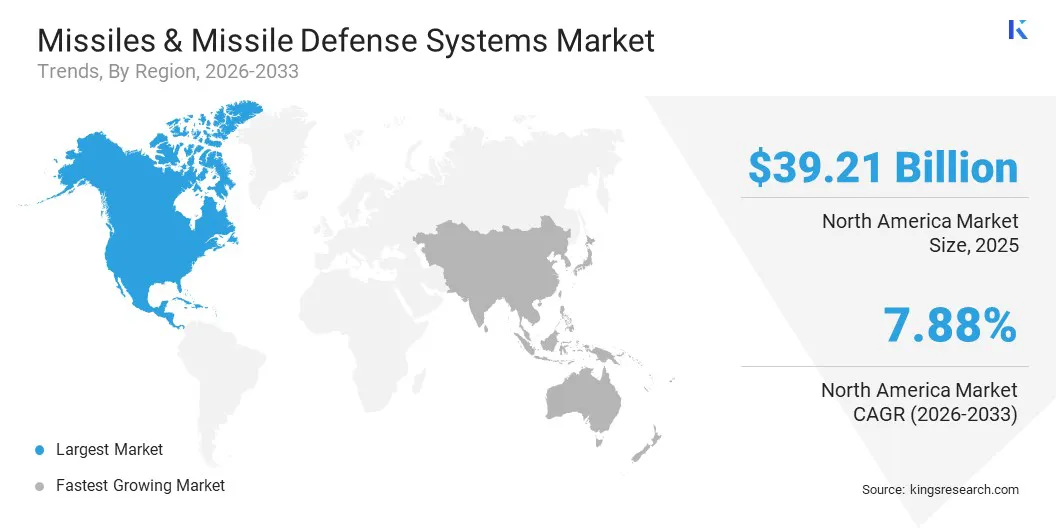
The North America missiles and missile defense systems market captured a share of around 45.54% in 2025, valued at USD 39.21 billion, and is projected to grow at a CAGR of 7.88% through 2033. North America faces increasing threats from intercontinental ballistic missiles (ICBMs) and unmanned aerial vehicles (UAVs), prompting investment in advanced missile interception systems.
The U.S. military is enhancing its Ballistic Missile Defense System (BMDS) with technologies such as THAAD and the Aegis BMD system. To counter UAV threats, the region is developing directed energy weapons (DEWs) and AI-powered counter-drone missile systems. North America is also home to some of the world's largest defense contractors, including Lockheed Martin, Boeing, RTX, and Northrop Grumman, which continue to invest heavily in next-generation missile technologies.
The Asia-Pacific missiles and missile defense systems industry is poised to register the fastest CAGR over the forecast period. The security landscape of the region is shaped by key countries, including China, India, South Korea, Japan, and others.
The increasing missile capabilities of China, including its hypersonic missile program, and North Korea's nuclear missile tests are prompting neighboring countries to strengthen their missile defense capabilities.
Countries in Asia-Pacific are also strengthening defense collaborations to enhance missile defense capabilities. The U.S.-Japan and U.S.-South Korea defense partnerships are facilitating joint development projects, including Aegis BMD systems and SM-6 missiles, while the Quadrilateral Security Dialogue (Quad) involving the U.S., Japan, Australia, and India is promoting the sharing of missile defense technologies and capabilities.
Key regulations, including the Missile Technology Control Regime (MTCR), which acts as a voluntary political framework involving 35 countries, are aimed at limiting the proliferation of missiles and technologies capable of delivering weapons of mass destruction. The framework relies on common export-control guidelines and a controlled list covering sensitive missile systems, components, software, and technologies. Several other country-level regulations in the missile and missile defense market include the following:
The global missiles and missile defense systems market comprises both established corporations and emerging players. Leading market participants are increasingly investing in research and development (R&D) to advance air and missile defense capabilities, driven by significant defense and army investments and contracts from various countries focused on enhancing national security.
By advancing missile defense technologies, these players are securing contracts from government defense agencies, supporting market expansion. Partnerships with governments and defense organizations further ensure continuous innovation in missile technologies, positioning these companies at the forefront of the industry.
How We Gather This Information
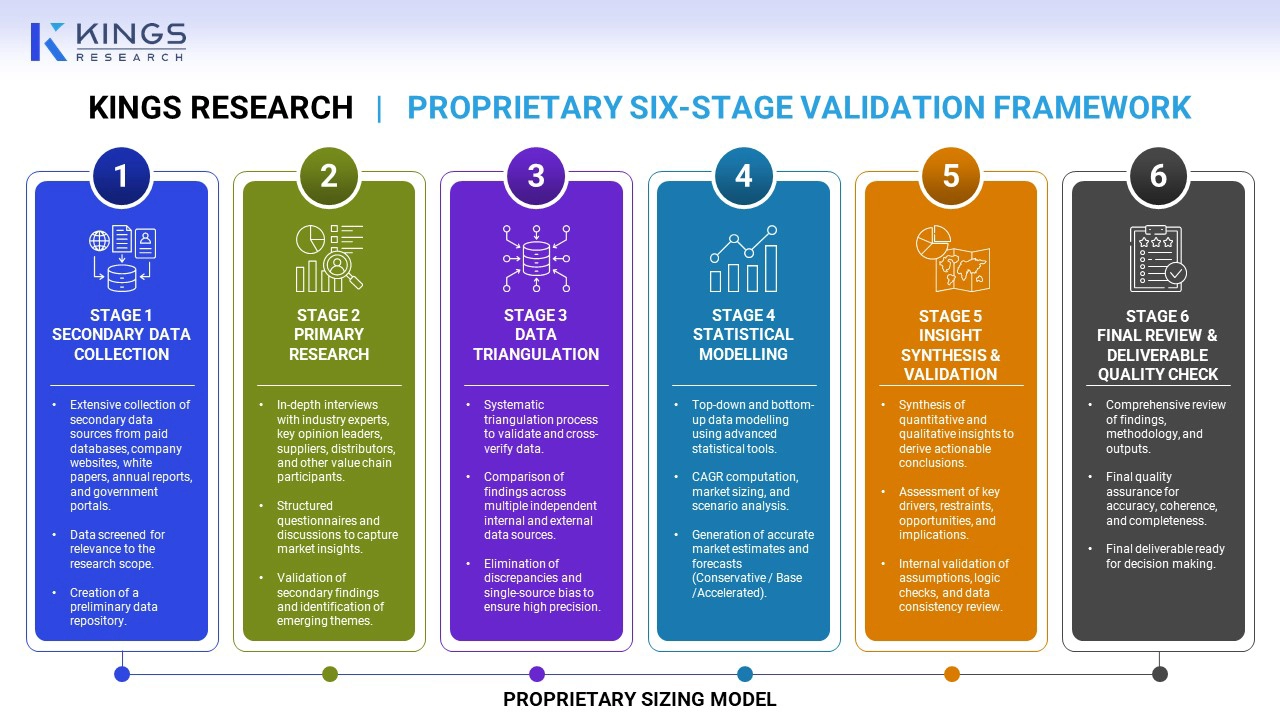
Our methodology triangulates insights from multiple independent and publicly available research databases, which is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Anurag Singh specializes in delivering actionable market intelligence across various domains such as ICT, IoT, Automotive & Transportation, Semiconductor & Electronics, Energy & Power, and Aerospace & Defence. With a background in Computer Science Engineering and extensive experience in market research, he brings a strong understanding of industry dynamics, emerging technologies, competitive landscapes, and evolving market opportunities. His expertise includes market sizing, forecasting, trend analysis, competitive benchmarking, and data-driven strategic insights. Anurag closely monitors technological advancements and shifting industry ecosystems to identify growth opportunities and emerging business trends. His research supports organizations in making informed strategic decisions, assessing market potential, understanding technology adoption, and navigating complex, rapidly evolving industries. Passionate about innovation and technology, he combines analytical expertise with a practical understanding of market developments to deliver meaningful insights that help businesses strengthen their strategies, identify new opportunities, and maintain a competitive edge in dynamic global markets.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


