
Inquire Now
Key Strategic Points
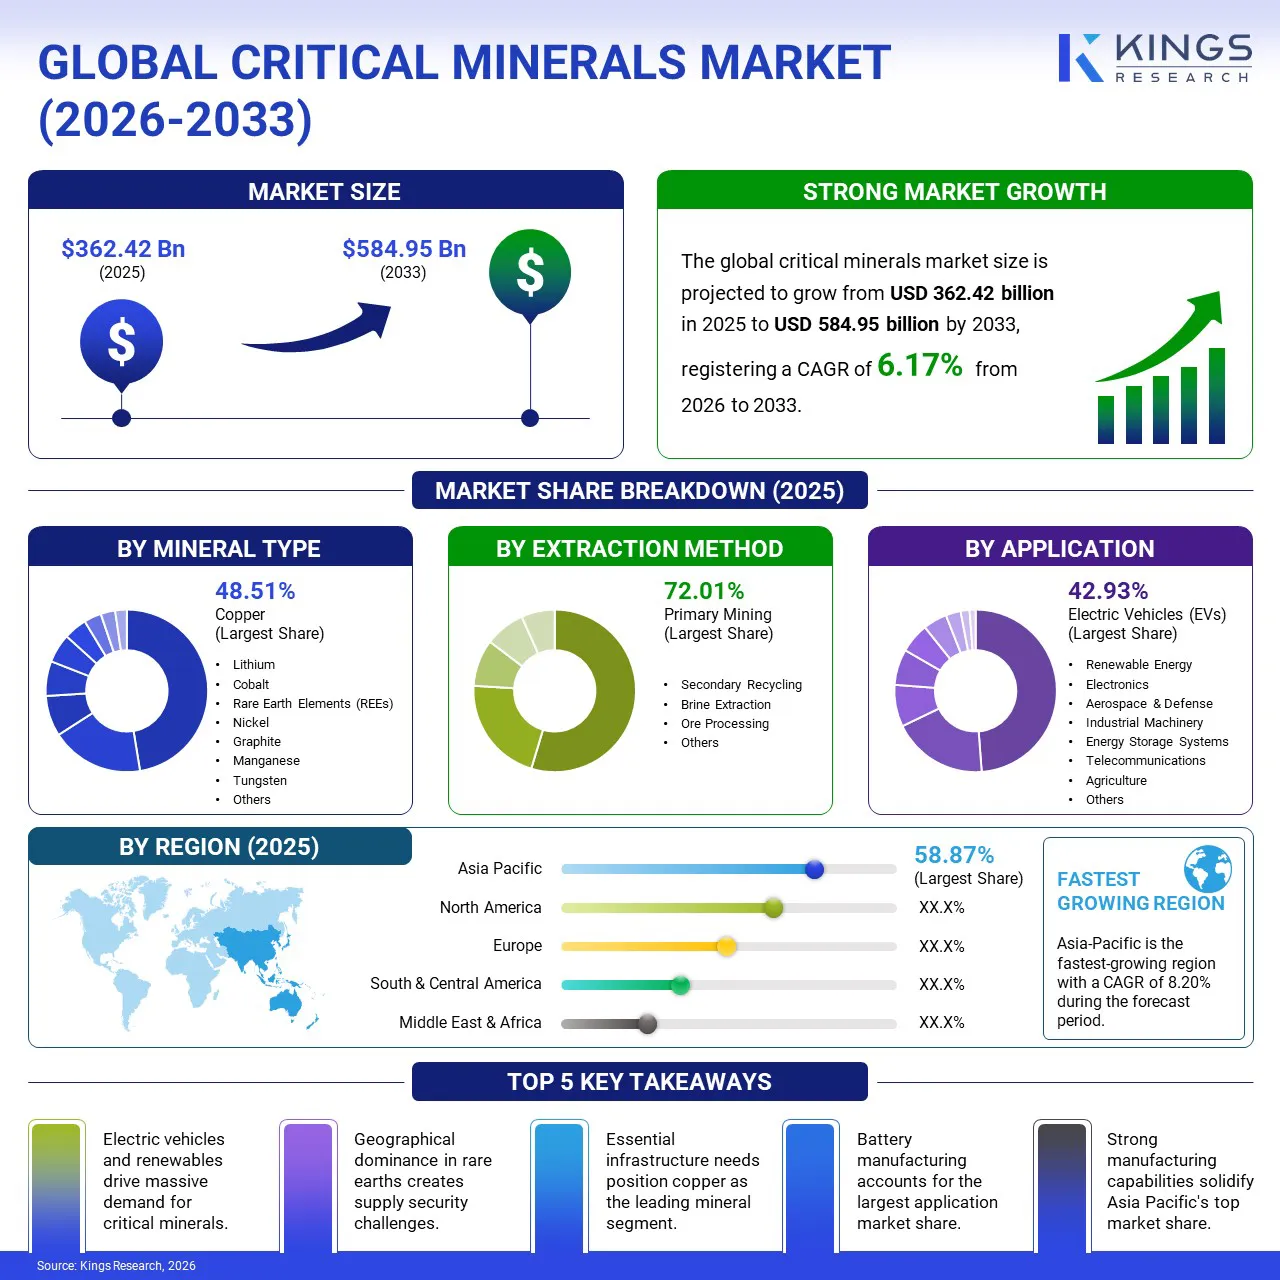
According to Kings Research, the global critical minerals market size was valued at USD 362.42 billion in 2025 and is projected to reach USD 584.95 billion by 2033, growing at a CAGR of 6.17% from 2026 to 2033. This represents a 61.4% increase over the forecast period, with Asia Pacific, which held a 58.87% revenue share in 2025, accounting for the largest share of this incremental growth.
The accelerating transition toward clean energy, electric mobility, advanced electronics, energy storage, and digital infrastructure is fueling growth for the global critical minerals market. Rising demand for lithium, copper, nickel, cobalt, graphite, and rare earth elements is encouraging investments across mining, processing, recycling, and supply-chain development, with Asia Pacific remaining a major market due to its established mining, refining, manufacturing, and technology capabilities.
The rapid adoption of clean energy technologies such as solar PV and batteries further creates market growth avenues, with leading producers increasingly aligning extraction and processing operations to frameworks such as ISO 14001 environmental management standards and the Responsible Minerals Initiative (RMI) to satisfy buyer due diligence and traceability requirements.
The surge in adoption of electric vehicles (EVs) is significantly driving the demand for critical minerals, including lithium, nickel, cobalt, copper, manganese, neodymium, dysprosium, aluminum, and others. According to the International Energy Agency (IEA), a standard EV requires about six times the mineral inputs of a conventional automobile.
Lithium is one of the critical minerals experiencing particularly strong demand from the EV sector, as lithium-ion batteries are widely used in EVs due to their high energy density and long lifespan. The rapid growth in EV sales is thus translating into a considerable increase in lithium demand, thereby making it a key component of the automotive sector.
This rising demand is further pressurizing global lithium supplies, raising concerns over potential shortages and highlighting the need to diversify sources of supply. According to the International Energy Agency, the global EV battery demand is projected to exceed 3 TWh by 2030 under the IEA STEPS scenario, with 85% of battery production concentrated in China. This is enabling EV battery manufacturers and automakers to secure upstream supplies through investments in mining, processing, and long-term sourcing agreements.
In April 2026, Contemporary Amperex Technology Ltd. (CATL) laid plans to invest USD 4.4 billion to establish a new critical minerals mining arm. The subsidiary focuses on mineral exploration, processing, sales, and securing raw-material supplies for CATL’s battery business.
Factors including demand-supply imbalances, geopolitical tensions, trade restrictions, and changing economic conditions restrain the global critical minerals market. High price volatility creates uncertainty for market players and governments, making it more difficult to plan investments, secure long-term supplies, and develop new mining and processing capacity.
Export controls and supply-chain concentration further hamper market growth avenues for critical minerals. China is positioned as the dominant refiner for 19 of the 20 strategic minerals analyzed by the IEA, with an average market share of around 70%. The concentration of refining capacity positions China to limit supply and control critical minerals trade, creating supply imbalances and thus hampering widespread market growth avenues for the critical minerals market. As per UN Trade and Development (UNCTAD), the lithium demand is projected to rise by 353% and graphite demand by 131% during 2024-2040. The high concentration of critical mineral supplies in the Democratic Republic of the Congo, producing 74% of global cobalt, and Indonesia holding 43% of global nickel refining capacity further acts as a major restraint.
To address the challenges, market participants and governments are pursuing supply-chain diversification, recycling, technological innovation, responsible sourcing, and international cooperation. These measures can reduce dependence on concentrated suppliers, improve supply flexibility, and strengthen resilience against price and supply shocks.
In July 2025, Australia, India, Japan, and the United States launched the Quad Critical Minerals Initiative to strengthen and diversify critical mineral supply chains. In May 2026, the Quad adopted a framework to operationalize the initiative through cooperation on investment, project development, regulatory alignment, standards, technology, and private-sector engagement. The framework envisages mobilizing up to USD 20 billion in public and private-sector support for mining, processing, and recycling projects.
Additionally, in September 2025, India introduced the National Critical Minerals Mission, which sets a target of completing 1,200 domestic exploration projects by 2030-2031 to ensure domestic production of at least 15 critical minerals, including graphite, lithium, potash, and rare earth elements. The NCMM further targets acquisition of 50 mining assets across the globe, thus creating secure, diversified supplies of critical minerals for processing and building secure mineral supply chains.
The rapid expansion of artificial intelligence is significantly creating growth opportunities for critical minerals, including gallium, germanium, copper, rare earth elements, silicon, indium, and tantalum, utilized across semiconductors, data centers, and digital infrastructure.
AI data centers drive up demand for critical minerals crucial for energy generation, transmission, and storage. The centers rely on uninterruptible power supplies, which incorporate lithium-ion batteries, contributing to mineral dependency. Additionally, energy storage systems that require critical minerals are increasingly used for backup power, stabilizing electricity supply, and smoothing out fluctuations in high-frequency switching environments typical of AI infrastructure, and translating data-center capacity expansion directly into incremental demand for copper, lithium, and rare earth elements used in power and battery-backup systems. Countries are formulating policies aimed at securing mineral supply chains to address rising demand from technological advancements and infrastructure development.
For instance, in August 2025, the U.S. Department of Energy’s Office of Critical Minerals and Energy Innovation (CMEI) introduced competitive funding, partnerships, and technical assistance to strengthen energy security, reduce costs, and support domestic manufacturing. It currently lists 12 funding opportunities across areas such as critical minerals, industrial technologies, chemical technologies, electricity systems, and transportation.
|
Segmentation |
Details |
|
|
By Mineral Type |
Lithium, Cobalt, Rare Earth Elements (REEs), Nickel, Graphite, Manganese, Tungsten, Copper, and Others |
|
|
By Extraction Method |
Primary Mining, Secondary Recycling, Brine Extraction, Ore Processing, and Others |
|
|
By Application |
Electric Vehicles (EVs), Renewable Energy, Electronics, Aerospace & Defense, Industrial Machinery, Energy Storage Systems, Telecommunications, Agriculture, and Others |
|
|
By Region |
North America |
U.S., Canada, Mexico |
|
Europe |
France, the UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia Pacific |
China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East and Africa |
Turkey, U.A.E., Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South and Central America |
Brazil, Argentina, and the rest of South and Central America |
|
According to Kings Research, the copper segment held the largest market share of 51.06% in 2025 owing to the increasing usage of copper-based applications across diverse end-use verticals comprising clean energy technologies, electrical systems, and infrastructure development. The clean energy transitions and global renewable electrification targets act as significant drivers for copper demand.
The electric vehicles segment accumulated the largest market share of 30.50% in 2022. The growing adoption of electric mobility and rising demand for advanced battery technologies drive the demand for critical minerals, including lithium, nickel, cobalt, graphite, copper, and rare earth elements. These materials find diverse applications across EV batteries, motors, and related components, thereby boosting EV segment growth.
The global critical minerals industry is consolidated, with operations confined to major critical mineral extraction companies, including BHP Group, Glencore, Rio Tinto, and others. Additionally, the confinement of operations to select countries, including the Democratic Republic of the Congo (DRC), controlling nearly 70%+ of global raw production; Indonesia, accounting for over 50% of the global mined nickel supply; and Australia (lithium) and Chile (lithium brine), collectively capturing over 75% of global extraction, further intensifies the competitive landscape of the global market.
Additionally, China's domination of upstream production, accounting for over 70% of global rare earth element (REE) output, concentrates pricing power and creates strategic dependency risk for downstream manufacturers of magnets, electronics, and wind turbine components that rely on REE inputs. Market players are pursuing strategic mergers, acquisitions, and partnerships to strengthen their competitive positioning, secure access to strategic mineral resources, diversify supply chains, expand geographic access, and enhance their capabilities across mining, processing, refining, and downstream value chains in the critical minerals market.
Based on region, the global market is classified into North America, Europe, Asia Pacific, the Middle East and Africa, and South and Central America.
Kings Research estimates that the Asia-Pacific critical minerals market share stood at 58.87% in 2025 in the global market, with a valuation of USD 213.36 billion. The high share is attributable to the presence of dominant processing, refining, and manufacturing capacity, particularly across China, Australia, Indonesia, Vietnam, and India, which control a large share of global rare-earth and other critical-mineral deposits.
The presence of major semiconductor, battery, electronics, and clean-energy industries across the region acts as a major catalyzing factor, boosting the demand for essential critical minerals, thereby creating market growth avenues. Additionally, the presence of strategic maritime routes and concentrated processing infrastructure reinforces the position of Asia Pacific in global critical-mineral supply chains. Recent developments, including key exploration projects and strategic investment opportunities, highlight the growing focus on securing domestic resources and strengthening critical mineral supply chains across the Asia Pacific.
In September 2026, China discovered a major copper and gold deposit in Anhui province, highlighting significant domestic mineral potential. The Chating deposit is estimated to contain more than 1 million tons of copper and over 200 tons of gold, making the discovery strategically crucial for China as the country seeks to reduce its reliance on external supplies of critical minerals.
Additionally, in September 2026, India revived preliminary talks with Zambia to explore investments in copper and other critical minerals owing to the rise in demand for critical materials. India’s state-owned Khanij Bidesh India Ltd. is also assessing mineral opportunities in Australia, Brazil, Canada, Russia, Indonesia, and Malawi, reflecting India’s efforts to secure overseas supplies of copper and cobalt and reduce its growing dependence on imports.
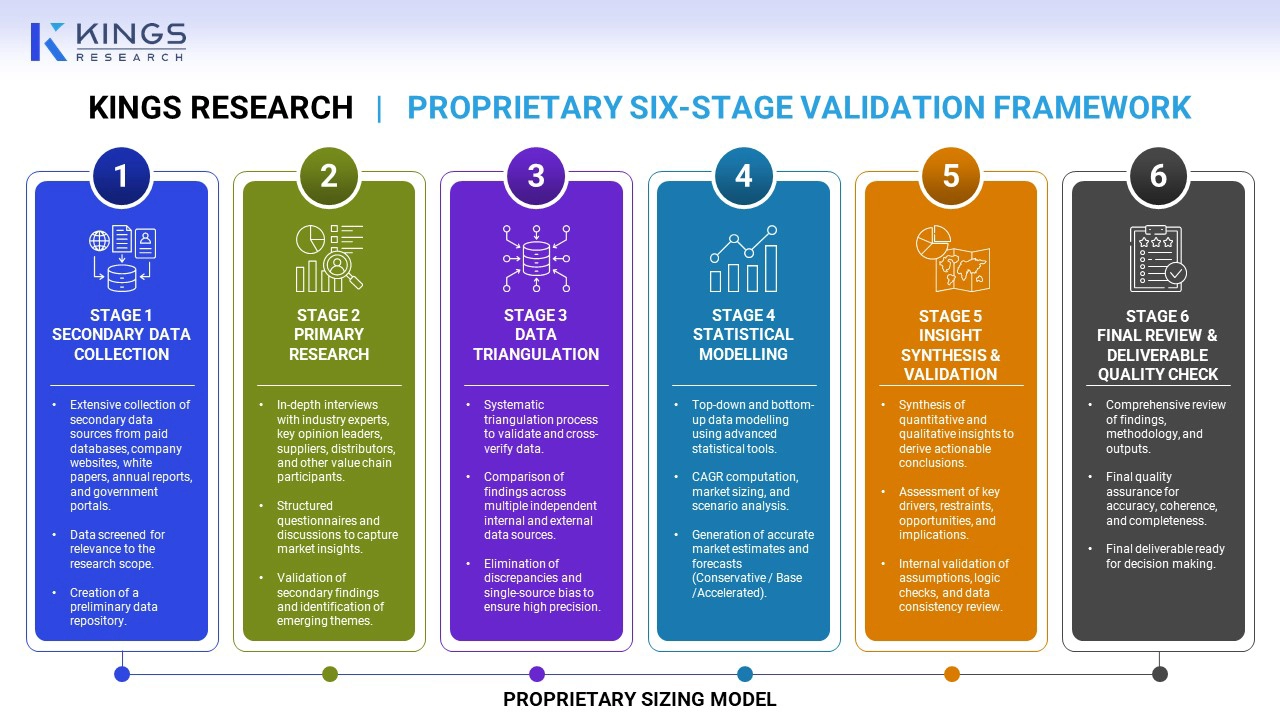
Our methodology combines bottom-up and top-down triangulation, supported by primary interviews with mining operators, mineral processors, and downstream manufacturers across key regions, and cross-referenced against regulatory filings, customs and trade data, and public company disclosures. Our analysts' ongoing engagement with industry executives and trend tracking across the mineral supply chain inform the demand and pricing assumptions used throughout this report. All estimates undergo multi-stage validation; no single-source data is presented without corroboration from at least two independent sources.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Antriksh is an experienced analyst specializing in cross-domain research across diverse industries. With a strong foundation in data analysis and statistical interpretation, he delivers insightful market reports that guide strategic decision-making. Antriksh excels in conducting primary research, with a focus on identifying trends and understanding consumer behavior. Thriving in dynamic and high-pressure environments, he combines analytical expertise with a commitment to delivering impactful outcomes. Beyond his professional pursuits, Antriksh's passion for travel fuels his curiosity and broadens his perspectives, enriching his ability to uncover unique insights that enhance his research capabilities. He is equally adept at synthesizing quantitative findings with qualitative context, which allows him to present holistic viewpoints to clients. His disciplined work ethic and intellectual agility make him a trusted partner in navigating market uncertainties. He consistently seeks out new methodologies to refine his analytical toolkit, and his ability to communicate complex insights clearly ensures stakeholders act confidently on his recommendations.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


