
Inquire Now
Key Strategic Points
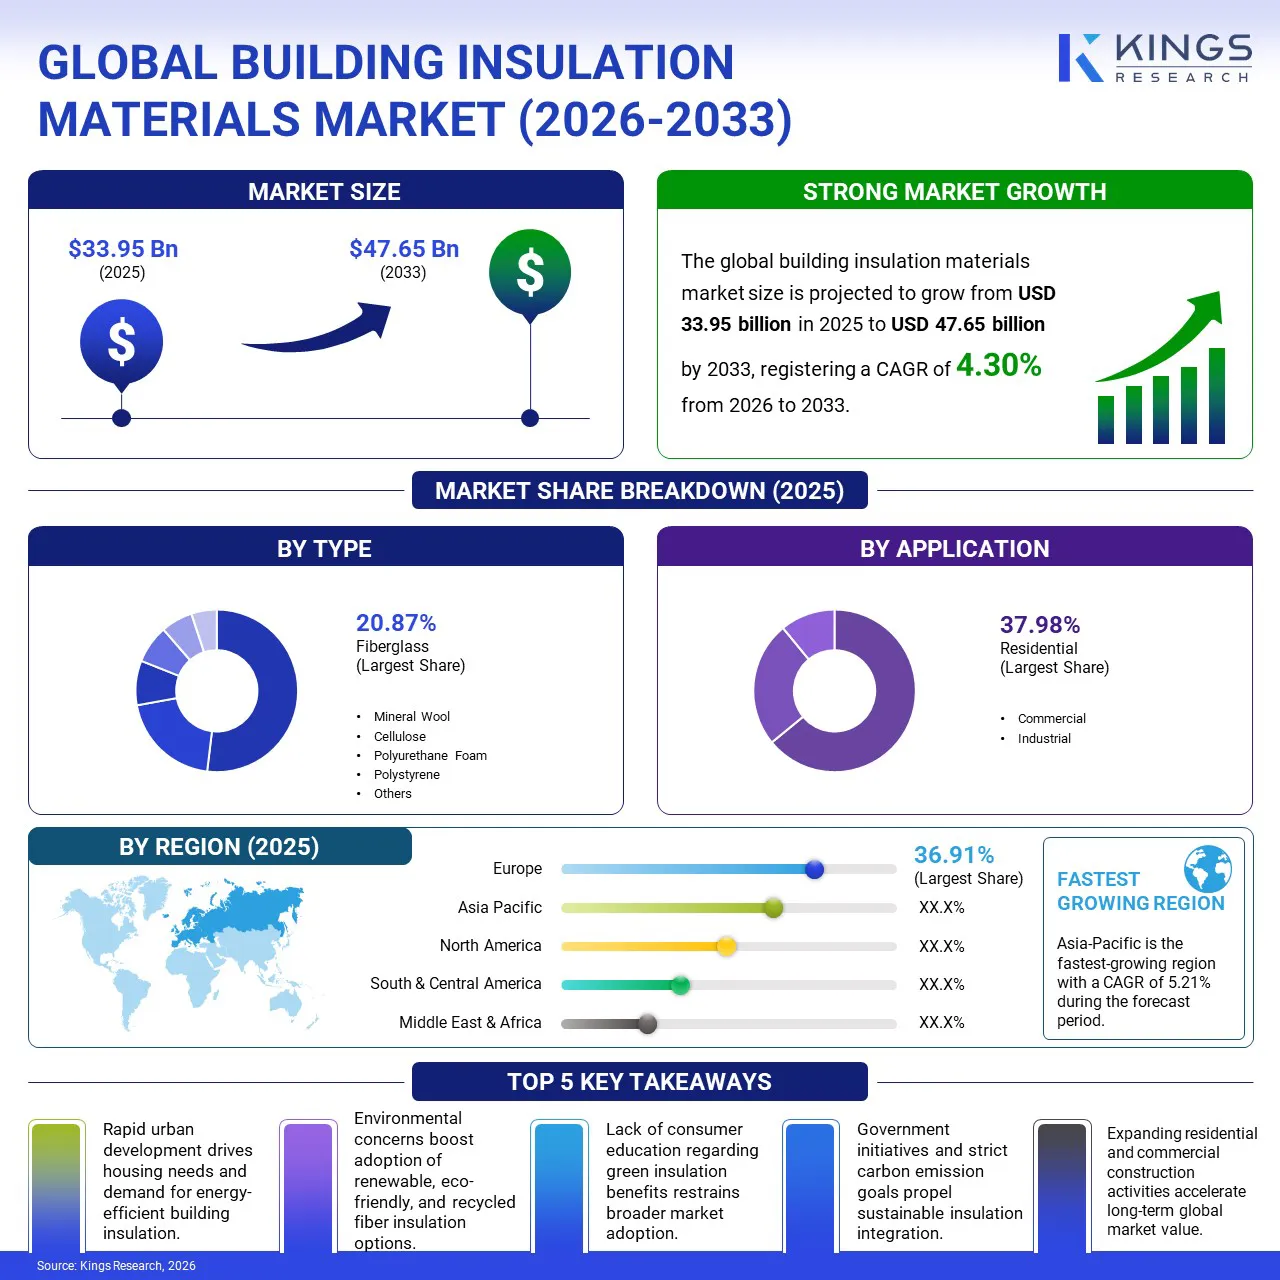
According to Kings Research, the global building insulation materials market size was valued at USD 33.95 billion in 2025 and is estimated to reach USD 47.65 billion by 2033, growing at a CAGR of 4.30% from 2026 to 2033. The market includes materials used to control temperature, reduce energy consumption, enhance thermal performance, provide soundproofing, and manage moisture within residential, commercial, and industrial buildings.
The market is expanding as governments, building owners, and construction companies place greater emphasis on energy efficiency, decarbonization, and sustainable construction. Stricter building energy codes, rising heating and cooling costs, increasing renovation activity, and growing demand for high-performance insulation are encouraging the adoption of fiberglass, mineral wool, polystyrene, polyurethane-based materials, cellulose, and other advanced insulation products.
Building insulation materials are increasingly being evaluated not only on thermal resistance but also on installation efficiency, fire performance, moisture resistance, embodied carbon, recyclability, and life-cycle performance. This shift is encouraging manufacturers to develop low-carbon, recycled, bio-based, and high-performance insulation solutions for both new construction and building retrofit applications.
Major companies operating in the building insulation materials market include Owens Corning; Saint-Gobain; Kingspan Group; Knauf Insulation; BASF SE; ROCKWOOL A/S; Johns Manville; Covestro AG; Huntsman International LLC; and Atlas Roofing Corporation, among others.
Rapid urbanization and population growth are increasing demand for residential buildings, commercial facilities, and infrastructure, thereby expanding the addressable market for insulation products. According to the World Bank, approximately 56% of the world's population resides in urban areas, and the global urban population is expected to continue increasing through 2050. As urban areas expand, building owners and developers are placing greater emphasis on controlling heating and cooling requirements. Insulation improves the thermal envelope of buildings, helping reduce heat transfer and energy consumption while improving indoor comfort.
The growing focus on energy-efficient construction is particularly important in regions experiencing rapid infrastructure development. China, India, and other Asia-Pacific economies are witnessing significant construction and urban development, creating opportunities for manufacturers of fiberglass, mineral wool, rigid boards, spray foam, and other insulation systems.
Governments are also strengthening building energy-efficiency standards to reduce energy consumption and greenhouse gas emissions. In Europe, the revised Energy Performance of Buildings Directive (EU/2024/1275) and the Energy Efficiency Directive (EU/2023/1791) support higher building efficiency and decarbonization objectives. In the U.S., building efficiency requirements and green-building initiatives are supporting demand for energy-efficient construction materials.
India uses the National Building Code and related energy-efficiency frameworks to promote safer, more sustainable, and energy-efficient construction. These regulatory developments are increasing the importance of insulation thickness, thermal resistance, fire performance, and material efficiency in construction specifications.
Increasing energy costs are further encouraging homeowners, commercial building operators, and industrial facilities to reduce energy consumption through improvements to building envelopes. Insulation can reduce heat transfer through roofs, walls, floors, and other building components, thereby lowering heating and cooling requirements. As building owners increasingly evaluate projects based on lifetime operating costs rather than initial construction expenses alone, insulation products with stronger thermal performance can provide an attractive long-term return on investment.
The renovation of existing buildings also represents a significant opportunity for insulation manufacturers. Older buildings often have inadequate insulation, resulting in higher heating and cooling requirements and lower occupant comfort. Government energy-efficiency initiatives, rising energy costs, and growing awareness of building performance are encouraging property owners to retrofit roofs, walls, floors, and other building components. Retrofit activity is supporting demand for flexible insulation materials, rigid boards, spray foam, and loose-fill products that can be installed within existing structures.
High installation costs can limit the adoption of advanced insulation materials, particularly in price-sensitive construction markets. Products such as high-performance rigid boards, aerogels, and specialty insulation systems can require higher upfront investment compared with conventional materials. Fluctuations in petrochemical feedstock prices can also affect the cost of polyurethane, polyisocyanurate, EPS, and other polymer-based insulation products. Installation requirements, skilled labor availability, and project-specific building configurations can further increase overall insulation costs, making advanced insulation solutions less attractive for cost-sensitive construction projects.
Some insulation materials also face challenges related to installation, handling, moisture exposure, fire performance, and worker safety. Mineral fiber products can generate dust during installation, while certain advanced materials require specialized installation procedures. Concerns around material performance, installation quality, and long-term durability can influence purchasing decisions and limit adoption in certain applications.
Growing emphasis on sustainable construction is increasing demand for insulation products with lower embodied carbon, recycled content, renewable feedstocks, and improved end-of-life characteristics. Construction material manufacturers are upgrading thermal performance properties and developing low-carbon, bio-based insulation boards to meet strict net-zero building efficiency standards. Materials such as cellulose, hemp, recycled fibers, and other bio-based products are gaining attention as building owners increasingly evaluate both operational and embodied carbon. Manufacturers are also focusing on improved product design, easier installation, higher fire resistance, and lower environmental impact to address concerns related to insulation performance, installation quality, durability, and sustainability.
|
Segmentation |
Details |
|
By Type |
Fiberglass, Mineral Wool, Cellulose, Polyurethane Foam, Polystyrene, Others |
|
By Application |
Residential, Commercial, Industrial |
|
By Region |
North America: U.S., Canada, Mexico |
|
Europe: France, UK, Spain, Germany, Italy, Russia, and the rest of Europe |
|
|
Asia-Pacific: China, Japan, India, Australia, ASEAN, South Korea, Rest of Asia-Pacific |
|
|
Middle East & Africa: Turkey, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa |
|
|
South and Central America: Brazil, Argentina, and the rest of South and Central America |
The global building insulation materials market is segmented based on type, application, and geography.
Based on type, the market is segmented into fiberglass, mineral wool, cellulose, polyurethane foam, polystyrene, and others. Fiberglass held the largest share of 20.87% in the building insulation materials market in 2025, supported by its widespread application in residential and commercial construction, thermal insulation properties, fire resistance, and established installation practices. Its extensive use across walls, ceilings, attics, and floors continues to support its leading position.
Based on application, the market is segmented into residential, commercial, and industrial. Residential accounted for the largest share of 37.98% in the building insulation materials market in 2025, supported by the large global housing stock, substantial residential energy consumption, new housing construction, and increasing renovation and energy-efficiency activity. According to the IEA, residential buildings account for approximately 70% of total energy demand in buildings, highlighting the substantial energy-saving potential associated with improving insulation and building-envelope performance.
Based on region, the global market has been classified into North America, Europe, Asia Pacific, the Middle East & Africa, and South & Central America.
According to Kings Research, Europe accounted for the leading share in the global building insulation materials market in 2025. The region's leading position is supported by stringent building energy-efficiency regulations, decarbonization targets, renovation initiatives, and growing demand for sustainable construction materials. Germany, France, and the UK are among the important markets for high-performance insulation products. The European Union's focus on reducing building energy consumption and carbon emissions is expected to continue supporting market demand.
According to Kings Research, Asia-Pacific is projected to have significant growth during the forecast period, making it the fastest-growing regional market. Increasing construction activities in China, India, and Japan are generating strong demand for energy-efficient building solutions. Rapid urbanization, industrialization, infrastructure development, and rising middle-class populations are supporting construction activity across the region.
Government incentives for green buildings and growing awareness of energy efficiency are encouraging the adoption of advanced insulation materials.
North America benefits from established construction markets, energy-efficiency standards, renovation activity, and demand for high-performance insulation, with the U.S. representing a major market due to its large building stock. The Middle East & Africa market is supported by infrastructure development, commercial construction, extreme climatic conditions, and increasing attention to building energy consumption. Demand for insulation in the region is particularly relevant as cooling requirements account for a significant share of building energy use. South and Central America is supported by residential construction, commercial infrastructure development, and growing awareness of energy-efficient building systems. Brazil represents an important regional market due to its large construction sector and increasing focus on sustainable building practices.
In the building insulation materials industry, acquisitions are increasingly common as companies seek to expand their market presence, diversify product offerings, and strengthen operational efficiency.
These strategic moves allow businesses to tap into new geographic regions, enhance technological capabilities, and meet the growing demand for sustainable and energy-efficient insulation solutions, ensuring competitiveness in a rapidly evolving industry.
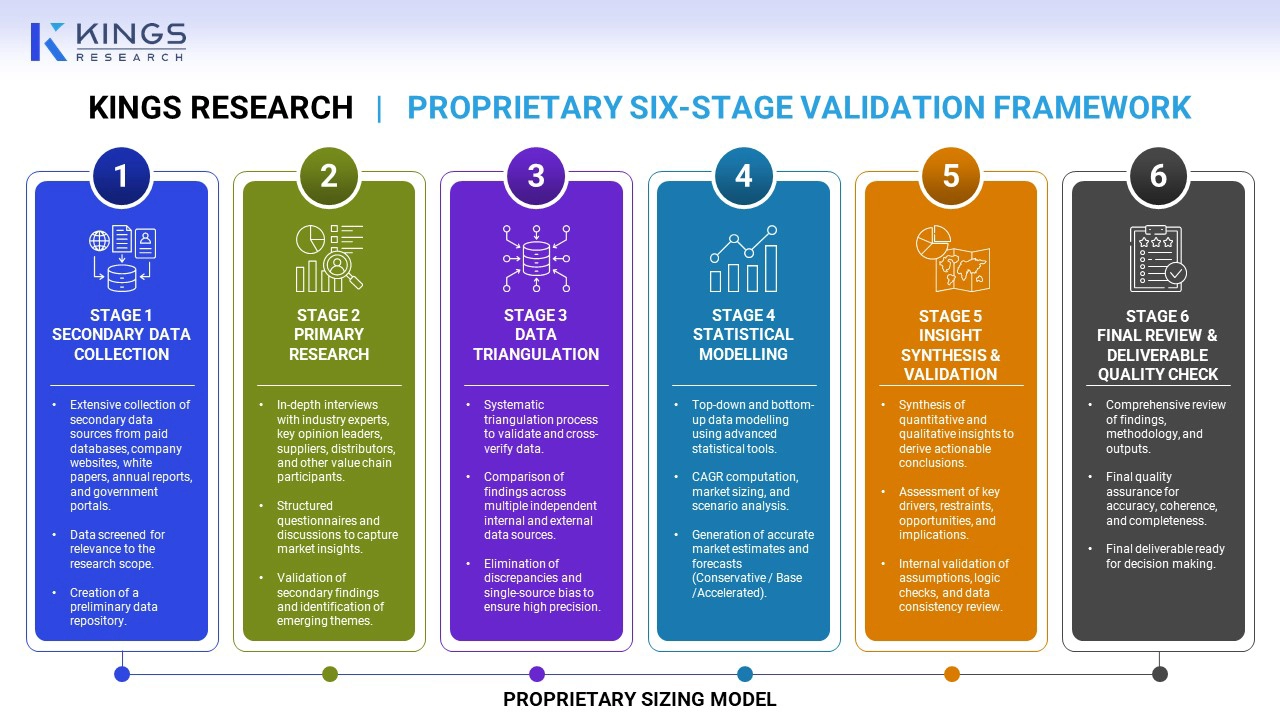
Our methodology triangulates insights from multiple independent and publicly available research databases and is further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
Our custom offerings deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Sharmishtha is a budding research analyst with a strong commitment to achieving excellence in her field. She brings a meticulous approach to every project, delving deep into details to ensure comprehensive and insightful outcomes. Passionate about continuous learning, she strives to enhance her expertise and stay ahead in the dynamic world of market research. Beyond work, Sharmishtha enjoys reading books, spending quality time with friends and family, and engaging in activities that foster personal growth. Her dedication to precision ensures that no critical detail is overlooked, and her analytical rigor consistently produces reliable, evidence-based conclusions. Sharmishtha's proactive curiosity drives her to explore emerging research methodologies, which she readily applies to deliver fresh perspectives on complex market questions. Her collaborative nature and openness to constructive feedback make her a dependable team player. She balances technical accuracy with clear communication, ensuring her insights are actionable for clients and stakeholders alike.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


