
Inquire Now
Key Strategic Points
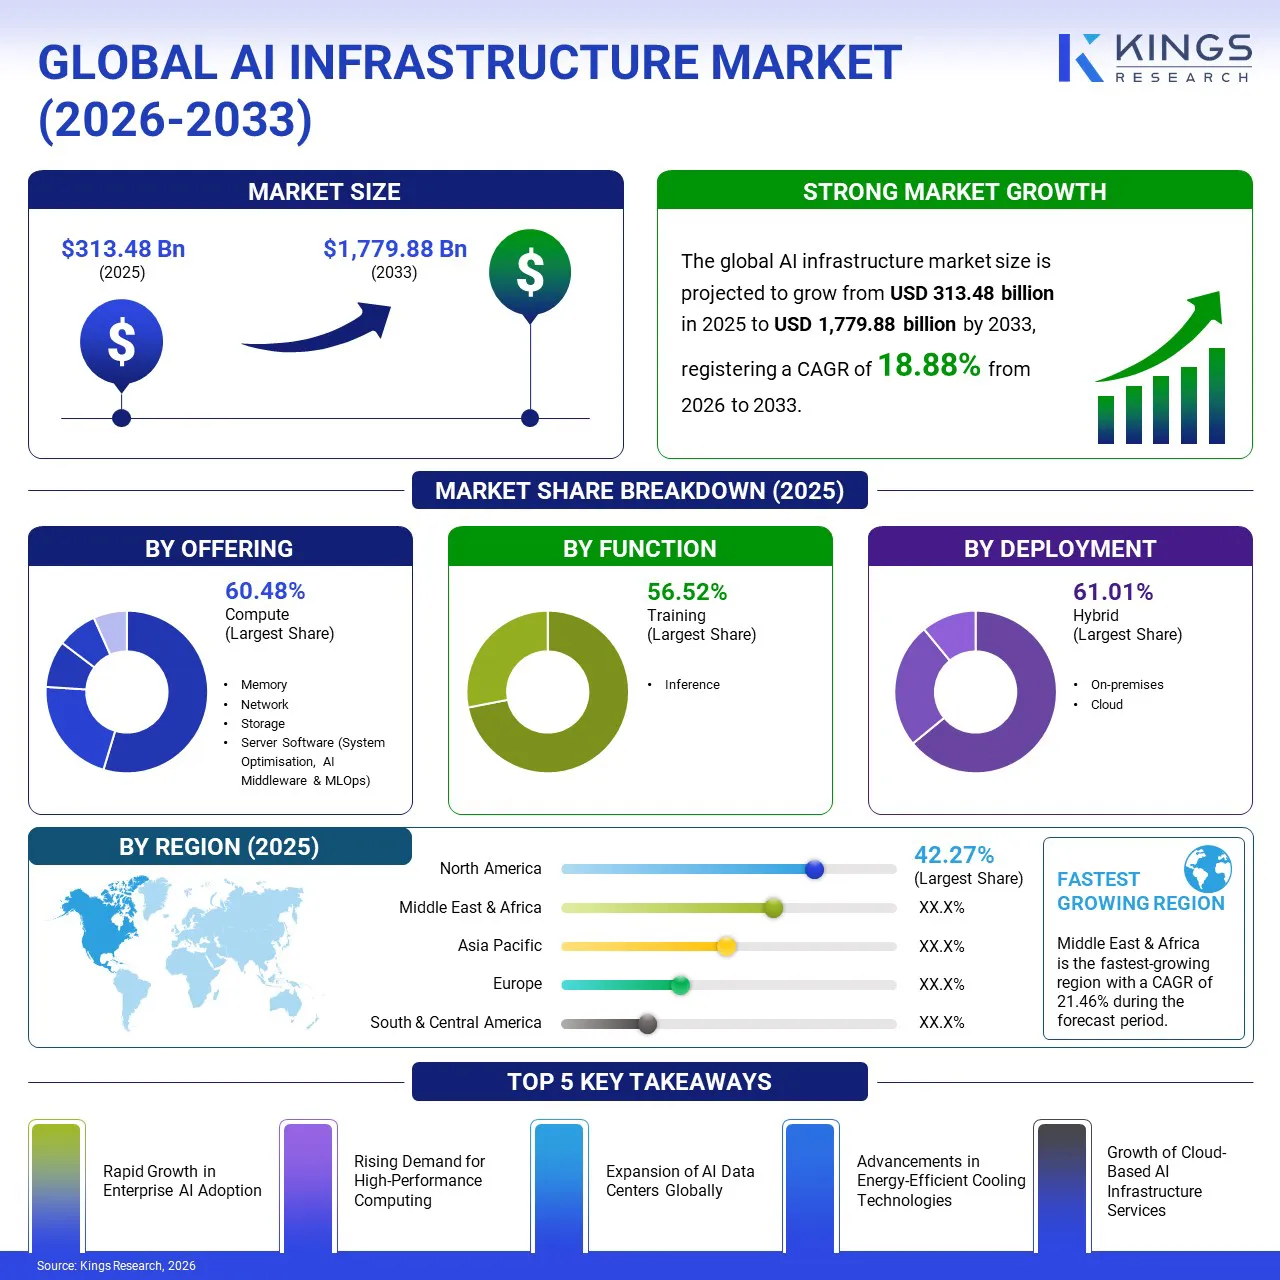
According to Kings Research, the global AI infrastructure market size was USD 313.48 billion in 2025 and is projected to reach USD 1,779.88 billion by 2033, growing at a CAGR of 18.88% from 2026 to 2033.
AI infrastructure comprises the hardware, software, and supporting facilities required to develop, train, deploy, and operate AI workloads. Growing adoption of generative AI, machine learning, and AI-powered applications is driving demand for high-performance computing, specialized processors, high-bandwidth memory, scalable storage, and high-speed networking. These technologies support efficient model training, real-time inference, and large-scale data processing.
This report covers compute, memory, networking, storage, and server software used for AI training and inference. The growth of cloud computing, AI applications, and data centers is driving demand for scalable and flexible infrastructure.
Rising data security, regulatory compliance, and sovereignty concerns are driving localized and hybrid solutions. Reliable power, advanced cooling, and strong connectivity are essential for large-scale AI computing. Technological advancements and investments by technology providers, cloud operators, and governments are strengthening the AI infrastructure ecosystem.
Rising AI adoption is boosting demand for high-performance computing. Hyperscaler capital spending highlights this trend. Based on guidance accompanying first-quarter 2026 earnings, Amazon raised its full-year 2026 cash capital expenditure (Capex) guidance to approximately USD 220 billion, primarily driven by investments in AWS and AI infrastructure. Similarly, Microsoft projected infrastructure commitments of approximately USD 175 billion to USD 190 billion for data centers, energy grids, liquid cooling, and custom AI silicon. These investments support Azure and OpenAI workloads, fuelling AI infrastructure market expansion. AI agents, coding assistants, and larger models are further increasing computing requirements, while data security, regulatory compliance, and data sovereignty requirements are encouraging investment in local AI infrastructure.
According to UNCTAD, announced greenfield investment in AI infrastructure grew by an average of 47% annually between 2020 and 2025, with cumulative investment expected to reach nearly USD 8 trillion by 2030 across data centers, connectivity, and supporting digital infrastructure. AI infrastructure accounted for 60% of greenfield investment in strategic sectors, highlighting its major role in global capital allocation, particularly through public-private partnerships in emerging markets. For instance, the U.S. Department of Energy (DOE) is evaluating federal sites for partnership with the private sector to develop next-generation AI infrastructure and energy projects.
In March 2026, the DOE announced a partnership with SoftBank and AEP Ohio to develop a data center campus at the former Portsmouth uranium enrichment site in Ohio (U.S.), supported by 10 GW of new power generation. It is among the country's largest announced integrated data center and power projects.
The shift of AI from training to everyday applications and inference is becoming a larger workload, prompting cloud providers to develop custom chips that reduce operating costs. AWS launched its Trainium3 chip in December 2025, while Microsoft introduced its Maia 200 accelerator in January 2026, joining Google's TPUs and Meta's in-house MTIA chips. This shift is expanding demand beyond GPUs to custom accelerators, high-bandwidth memory, and high-speed networking.
AI and data center expansion are straining power grids. Training advanced AI models requires thousands of graphics processing units (GPUs) operating continuously, increasing electricity consumption. The International Energy Agency (IEA) estimates that global data center electricity consumption will rise from 415 TWh in 2024 to about 945 TWh by 2030, driven largely by AI and high-performance servers. Sudden fluctuations in data center loads can also strain grid stability, causing voltage disturbances, transformer overloads, and, in the worst case, outages. Equipment shortages further complicate expansion, with lead times for high-capacity power transformers reaching up to four years.
In July 2026, a sudden loss of over 3 GW of data center electricity demand in Northern Virginia (U.S.) caused a major voltage disturbance across the PJM grid after a transmission line outage prompted facilities to switch to backup power. Similarly, in May 2025, a remote transient fault caused a 387 MW drop in data center load in Ireland, triggering emergency stability measures. These incidents highlight the grid stability risks of abrupt changes in AI workloads. Although energy use per query is declining, it remains significant at scale. In August 2025, Google reported that median Gemini text prompts use about 0.24 Wh, while OpenAI has cited about 0.34 Wh for an average ChatGPT query. Across billions of daily requests, inference creates substantial and growing electricity demand.
High-bandwidth memory (HBM) and DRAM have become supply bottlenecks. In October 2025, SK Hynix reported that its DRAM, NAND, and HBM supply for 2026 was sold out. Samsung Electronics and SK Hynix also reportedly proposed 60–70% increases in server DRAM prices for Q1 2026. Tight memory supply is increasing system costs and extending AI server delivery times.
U.S. export controls limit access to advanced AI chips in certain markets. Under a January 2026 Bureau of Industry and Security (BIS) policy, NVIDIA H200-class chip sales to China require case-by-case licensing, carry a 25% fee, and are capped at 50% of U.S. sales for each model. These restrictions influence where AI capacity is developed and which suppliers can serve Chinese buyers.
Advances in AI hardware and changing workloads are reshaping infrastructure design and deployment. AI inference is expanding beyond centralized data centers into hybrid cloud, edge, and on-device architectures to address latency, privacy, and network efficiency. This is increasing demand for compact, task-specific models and low-power, low-cost chips such as embedded AI systems-on-chip (SoCs), neural processing units (NPUs), micro-accelerators, and power management integrated circuits (PMICs), where energy efficiency is more important than peak performance.
Memory innovations are also creating opportunities. Advances in high-bandwidth memory (HBM) and next-generation DRAM are enabling taller stacks, better energy efficiency, and closer integration with compute cores. Meanwhile, memory hierarchies combining SRAM, DRAM, and persistent memory help reduce data movement.
In June 2026, Samsung Electronics showcased its next-generation HBM4E memory at COMPUTEX 2026, featuring speeds of up to 14 Gbps per pin, bandwidth exceeding 4 TB/s, and over 30% higher capacity than its predecessor. The company also introduced Heat Path Block (HPB) technology to enhance thermal management and operational stability, strengthening its AI memory and storage portfolio for next-generation AI infrastructure.
Specialized GPU cloud providers, known as neoclouds, are securing large, long-term contracts. In April 2026, CoreWeave expanded its agreement with Meta to about USD 21 billion in AI cloud capacity through 2032. In September 2025, Nebius signed a contract with Microsoft worth about USD 17 billion. Governments are also investing in national AI capacity. The EU's InvestAI initiative aims to mobilize EUR 200 billion for AI, including EUR 20 billion for AI gigafactories, while Saudi Arabia and the UAE are building large AI campuses with global technology partners.
Investors are assessing whether returns will justify the substantial spending on AI infrastructure. Demand for AI adoption remains strong, supported by rising model-provider revenues. For instance, Anthropic raised USD 30 billion in its Series G round at a post-money valuation of USD 380 billion, led by GIC and Coatue, to accelerate AI research, product development, and infrastructure expansion. The funding reflects strong enterprise demand for Claude, particularly Claude Code, and growing adoption of its AI solutions. This momentum is strengthening investor confidence despite concerns about whether infrastructure investments will generate sufficient returns.
|
Segmentation |
Details |
|
|
By Offering |
Compute, Memory, Network, Storage, and Server Software (System Optimization, AI Middleware & MLOps) |
|
|
By Function |
Training and Inference |
|
|
By Deployment |
On-Premises, Cloud, and Hybrid |
|
|
By Application |
Generative AI, Machine Learning, Natural Language Processing, and Computer Vision |
|
|
By End User |
Cloud Service Providers, Enterprises, and Government & Defense |
|
|
By Region |
North America |
U.S., Canada, and Mexico |
|
Europe |
France, UK, Spain, Germany, Italy, Russia, and Rest of Europe |
|
|
Asia Pacific |
China, Japan, India, Australia, ASEAN, South Korea, and Rest of Asia Pacific |
|
|
Middle East & Africa |
Turkey, U.A.E., Saudi Arabia, South Africa, and Rest of Middle East & Africa |
|
|
South & Central America |
Brazil, Argentina, and Rest of South & Central America |
|
The compute segment accounted for the largest share of 60.48% in 2025, valued at USD 189.59 billion. This growth is attributable to increasing demand for high-performance computing resources, including GPUs, CPUs, and AI accelerators that support the training and deployment of complex AI models. The surge in adoption of generative AI, large language models (LLMs), and data-intensive workloads further drives investment in compute infrastructure, while cloud providers' custom accelerators are gaining a larger share of new deployments.
The hybrid deployment segment is expected to grow at the fastest CAGR of 23.46% from 2026 to 2033, driven by demand for flexible and scalable AI infrastructure that combines private cloud security and control with public cloud scalability and cost efficiency. The rising demand for data privacy, regulatory compliance, and optimized AI workload management is further accelerating adoption across enterprises.
The enterprise segment is expected to grow at a CAGR of 20.63% from 2026 to 2033. This rapid growth is fueled by the increasing adoption of AI technologies across enterprises to automate business processes, enhance operational efficiency, and improve decision-making. Rising investments in generative AI, machine learning, and AI-powered applications, coupled with the need for scalable computing infrastructure to manage data-intensive workloads, are further accelerating segmental growth.
By region, the market is segmented into North America, Europe, Asia Pacific, the Middle East & Africa, and South & Central America.
North America held the largest share of 42.27% in 2025. This dominance is reinforced by the growing demand for computing power, data center capacity, high-speed connectivity, and reliable electricity. AI infrastructure development increasingly depends on physical assets such as data centers, fiber-optic networks, power generation facilities, transmission lines, substations, and cooling systems.
The U.S. remains at the forefront of this expansion, supported by significant investments in data center construction and integrated energy infrastructure, driven by increasing data consumption and generative AI adoption. The country is the leading hub for AI development. America's AI Action Plan, released in July 2025, establishes a national framework for AI infrastructure and federal policy, including streamlined permitting for AI data centers and the supporting power infrastructure.
In September 2025, Microsoft announced an investment of more than USD 7 billion across two facilities for its Fairwater data center project in Wisconsin. Designed to support advanced AI model training, the project combines large-scale GPU computing, high-speed fiber connectivity, and energy-efficient cooling while strengthening regional AI capabilities, workforce development, and sustainable digital infrastructure.
The Middle East & Africa is expected to register the fastest CAGR of 21.46% over the forecast period, emerging as a global AI computing hub through government-led investment, abundant energy resources, and partnerships with leading technology companies.
Saudi Arabia and the UAE are driving this transformation through initiatives such as Saudi Vision 2030 and the UAE Energy Strategy 2050, which aim to diversify their economies and strengthen digital capabilities. The region's renewable energy potential, expanding data center capacity, and strategic location between Asia, Europe, and Africa are attracting AI infrastructure investment.
Riyadh (Saudi Arabia) is emerging as an AI infrastructure hub, attracting partnerships with companies such as NVIDIA, AMD, Cisco, AWS, Microsoft, and Qualcomm. For instance, in November 2025, AMD, Cisco, and HUMAIN announced plans for a joint venture targeting up to 1 GW of AI infrastructure capacity by 2030, starting with a 100 MW deployment in Saudi Arabia. The initiative combines advanced GPU computing, data center capacity, and networking solutions to deliver scalable, cost-efficient AI infrastructure and strengthen the region’s AI capabilities.
Asia Pacific is a major market for AI infrastructure, supported by rapid digitalization, rising AI adoption, and substantial investments in data centers, AI servers, and cloud infrastructure. China is designated as the largest AI infrastructure market in the region. The country has established eight national computing hubs under its East Data, West Computing program, which increased its intelligent computing capacity to about 780 EFLOPS by August 2025, making it the world's second-largest, according to China's National Data Administration.
In India, the IndiaAI Mission, with an outlay of USD 1.25 billion, had onboarded more than 38,000 GPUs on its shared compute portal by May 2026, providing startups and researchers with subsidized access to AI computing.
In Europe, rising AI computing demand, data center expansion, and high-speed connectivity are driving AI infrastructure investment. Government initiatives such as the EU's AI Continent Action Plan (April 2025), the InvestAI initiative (February 2025), and the European Chips Act, alongside demand for secure and energy-efficient infrastructure, support regional growth.
In South & Central America, rising AI adoption, expanding cloud services, and investment in digital infrastructure are contributing significantly to market expansion. Growing demand for data processing and improved connectivity, alongside programs such as the Inter-American Development Bank's South Connection program, is expected to create opportunities for AI infrastructure deployment.
The AI market spans chips, memory, servers and systems, networking, cloud and neocloud capacity, data centers, power, and cooling, with distinct leaders across each layer. High capital requirements, access to power and advanced packaging, and long-term supply contracts create significant entry barriers. Established players are using investments, partnerships, joint ventures, acquisitions, and capacity agreements to expand infrastructure, accelerate deployment, and secure customers.
Key players spanning the main layers of AI infrastructure include:
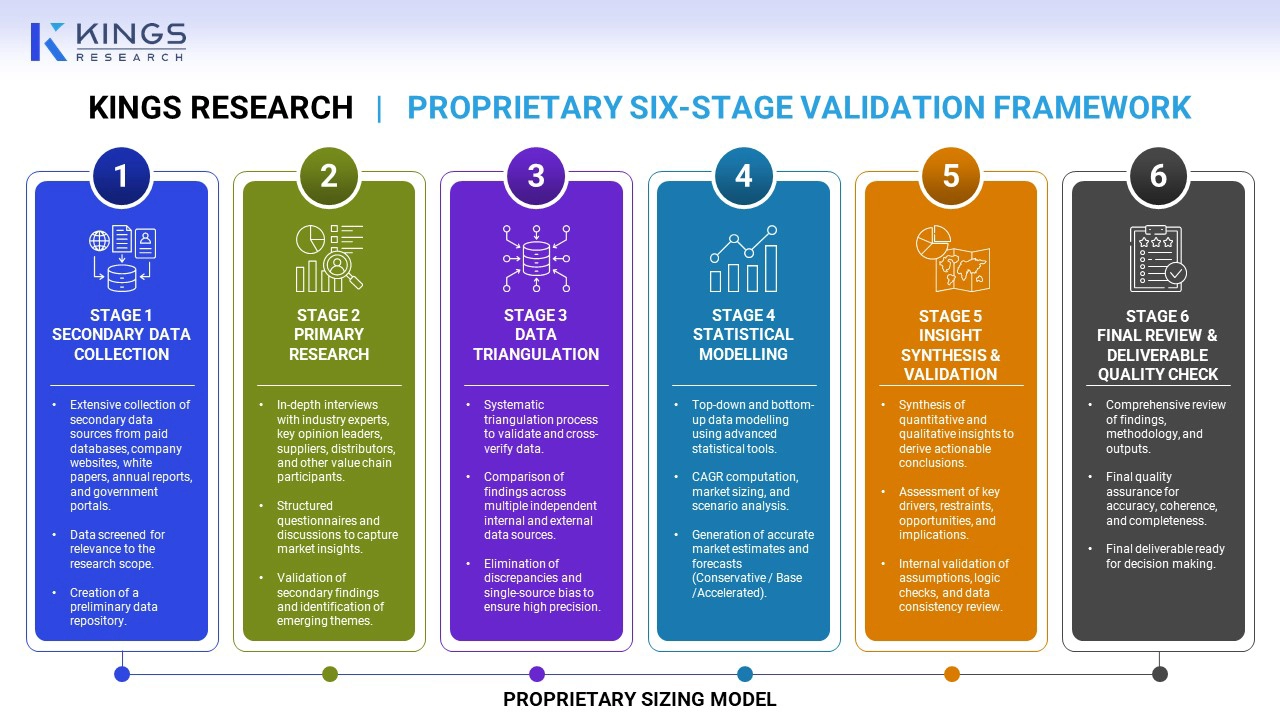
Our methodology triangulates insights from multiple independent and publicly available research databases, which are further validated against regulatory filings and public company disclosures. All estimates are cross-verified; no single-source data is presented without validation.
We deliver tailored, data-driven intelligence and strategic guidance to help organizations identify, evaluate, and capitalize on key market opportunities.
Frequently Asked Questions

Faizy brings over four years of experience in market research and consulting, with a proven ability to support strategic engagements across diverse industries and business environments. His work focuses on understanding complex market structures, identifying emerging opportunities, and translating research findings into clear, commercially relevant insights. With strong analytical capabilities and a structured approach to problem-solving, he evaluates industry trends, competitive landscapes, customer dynamics, and evolving business models. His expertise encompasses market research, competitive intelligence, market sizing and forecasting, industry assessment, company benchmarking, and strategic analysis. Faizy combines technical proficiency with a strong research orientation, enabling him to interpret both qualitative and quantitative information effectively. He has contributed to projects that help organizations assess growth potential, strengthen market positioning, and evaluate strategic priorities. His adaptable approach allows him to work across sectors while maintaining a consistent focus on accuracy, relevance, and delivering insights that support informed decision-making for clients and stakeholders.
Habi is a seasoned research and consulting leader with renowned experience in guiding clients on strategic growth and transformation initiatives across global markets. He has led high-performing research teams that deliver actionable insights on market expansion, M&A strategies, opportunity assessment, new business development, and product launches. His project portfolio spans large petrochemical producers, electronic device manufacturers, lubricants companies, and other leading enterprises across diverse industrial and consumer sectors. He currently heads the research department at Kings Research, where he is responsible for setting the research agenda, mentoring analysts, and ensuring client-ready deliverables that support executive decision-making. With extensive experience in market intelligence, strategic research, and consulting, Habi brings a strong understanding of evolving industry dynamics, competitive landscapes, emerging opportunities, and business growth challenges. His expertise includes developing research frameworks, translating complex market data into actionable strategic recommendations, and working closely with senior stakeholders to address critical business questions. He has also contributed to building research capabilities, strengthening analytical methodologies, and driving a culture of quality and insight-led decision-making within research teams. His cross-industry exposure enables him to connect market trends with broader business implications and provide perspectives that help organizations identify opportunities, mitigate risks, and make informed strategic decisions.


